

Informational content only. Not legal, tax, or financial advice. Private Student Relief is a consulting organization, not a law firm. Debt validation services are executed by an attorney-backed partner provider. Sallie Mae debt forgiveness options depend on loan characteristics, current holder or servicer, borrower circumstances, and jurisdiction. Sallie Mae Bank is a subsidiary of SLM Corporation (NYSE:SLM). Last reviewed: September 2026.
Written by Henry Silva
Private Student Loan Debt Specialist · 10+ years experience specifically with Sallie Mae portfolios: Sallie Mae Bank (SLM Corporation NYSE:SLM) settlement negotiation, Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) bankruptcy discharge precedent application, Sallie Mae Loan Modification Program qualification, cosigner release program (12 consecutive on-time principal-and-interest payments), NCSLT (National Collegiate Student Loan Trust) chain of assignment challenges for Sallie Mae-originated loans, statute of limitations analysis across states, and coordinated multi-path sallie mae debt forgiveness strategy. Last reviewed: September 2026.
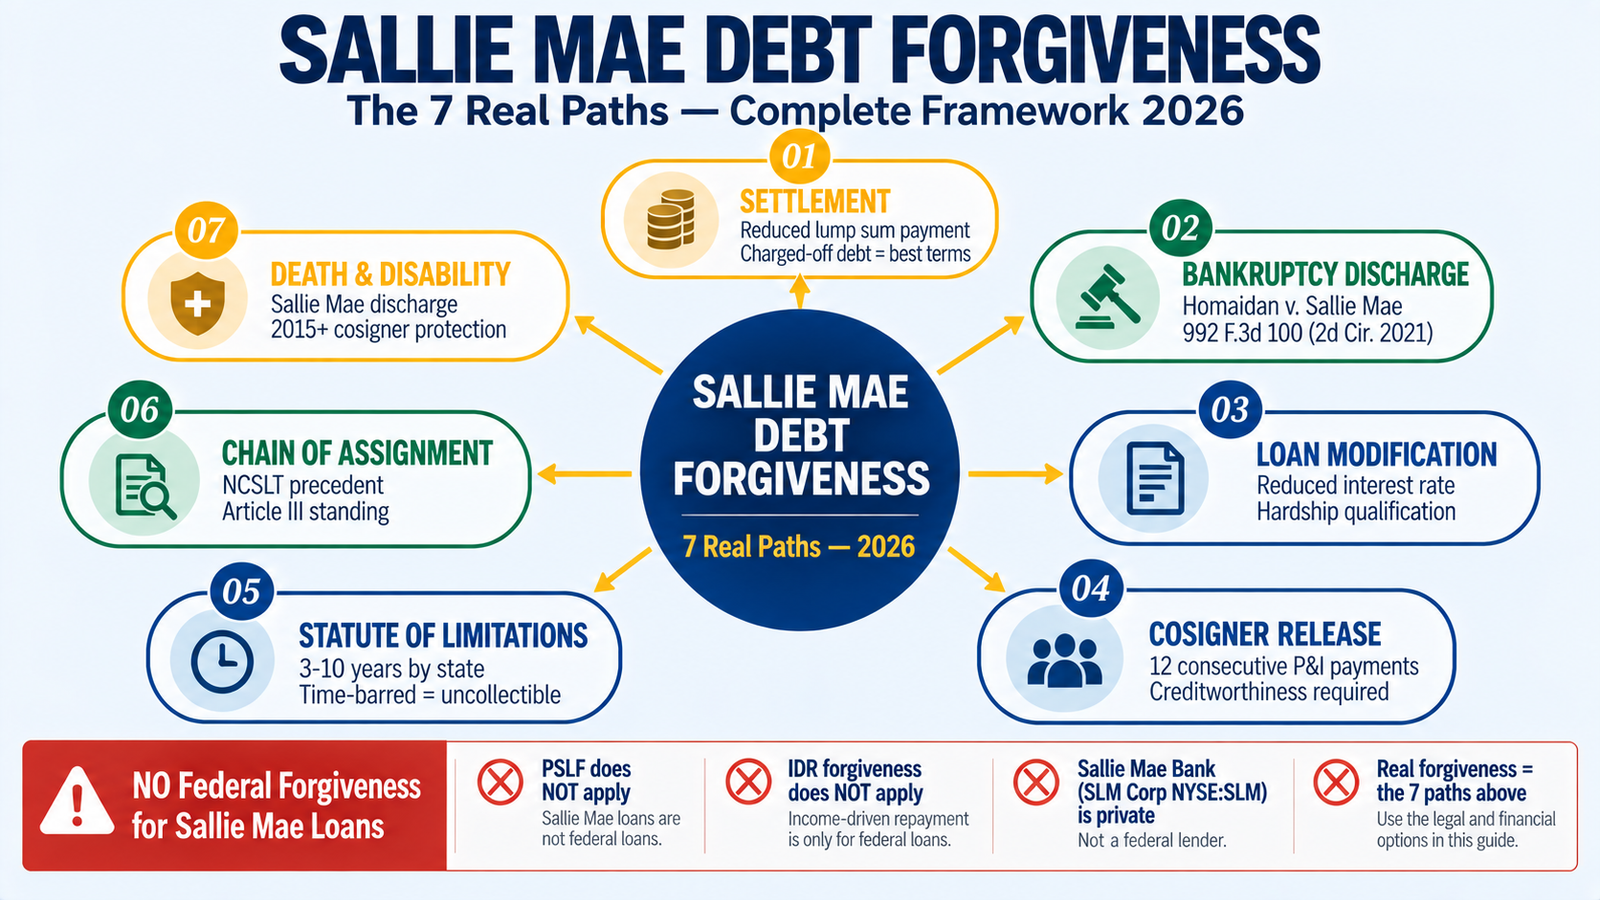
Sallie Mae debt forgiveness is one of the most searched topics for borrowers with private student loans — and one of the most misunderstood. Sallie Mae Bank, a subsidiary of SLM Corporation (NYSE:SLM), is the largest originator of private student loans in the United States. Many borrowers ask “how to get rid of Sallie Mae loans” or “how to get Sallie Mae loans forgiven” expecting a federal-style forgiveness program — but no such program exists for private loans. What DOES exist are seven real paths to get sallie mae student loans forgiven: settlement with Sallie Mae Bank for less than full balance, bankruptcy discharge under 11 U.S.C. §523(a)(8) with the landmark Homaidan v. Sallie Mae Second Circuit precedent, Sallie Mae’s own Loan Modification and hardship programs, cosigner release, statute of limitations, chain of assignment defense for NCSLT-related debt, and death/disability discharge. This complete guide walks through every legitimate path to sallie mae loan forgiveness in 2026.
Quick Answer
Sallie Mae debt forgiveness is achieved through seven established paths (federal forgiveness programs like PSLF and IDR do NOT apply to Sallie Mae private loans): (1) settlement negotiation with Sallie Mae Bank (SLM Corporation NYSE:SLM) for less than full balance, particularly effective for delinquent or charged-off loans; (2) bankruptcy discharge under 11 U.S.C. §523(a)(8) with Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) precedent making non-qualified Sallie Mae education loans dischargeable without undue hardship showing; (3) Sallie Mae Loan Modification Program with reduced interest rates and payments for qualifying borrowers demonstrating hardship; (4) statute of limitations expiration under state SOL (3-15 years by state) making time-barred Sallie Mae debt uncollectible; (5) Sallie Mae cosigner release program after 12 consecutive on-time principal-and-interest payments plus creditworthiness criteria; (6) chain of assignment defense on standing grounds particularly for NCSLT-related Sallie Mae-originated loans; (7) Sallie Mae’s death and disability discharge programs. The right path depends on loan status (current, delinquent, charged-off, in litigation), current holder or servicer, and borrower circumstances.
Read the complete framework below.
In this complete Sallie Mae forgiveness guide:
Understanding Sallie Mae — corporate profile and loan universe
SLM Corporation history, 2014 split from Navient, current portfolio
Path 1: Settlement — get Sallie Mae loans forgiven for less
How settlement works with Sallie Mae, realistic outcomes, timing
Path 2: Bankruptcy discharge — Homaidan Sallie Mae precedent
The Second Circuit case that changed Sallie Mae bankruptcy discharge
Path 3: Sallie Mae Loan Modification and hardship programs
Rate reductions, interest-only periods, hardship forbearance
Path 4: Sallie Mae cosigner release program
12-payment threshold, creditworthiness criteria, refinance alternative
Path 5: Statute of limitations for Sallie Mae debt
State-by-state SOL analysis, revival concerns, defensive application
Path 6: Chain of assignment defense — NCSLT and Sallie Mae
Article III standing challenges for NCSLT-related Sallie Mae debt
Path 7: Sallie Mae death and disability discharge
Death discharge for borrowers and cosigners, disability discharge
Choosing your Sallie Mae debt forgiveness path
Decision framework, common myths, professional resources
Understanding Sallie Mae — corporate profile and loan universe
Before exploring specific sallie mae debt forgiveness paths, it helps to understand what Sallie Mae actually is today, because the corporate structure directly affects which forgiveness paths apply to which loans. Many borrowers use “Sallie Mae” as shorthand for a broader concept of private student loan debt, but the actual entity and its historical predecessors matter significantly for legal analysis and settlement strategy.
SLM Corporation and the 2014 split
SLM Corporation (originally the Student Loan Marketing Association, established 1972 as a government-sponsored enterprise, fully privatized 2004) split into two companies in April 2014: Sallie Mae Bank (SLM Corporation NYSE:SLM) — kept the Sallie Mae name and continued the private student loan origination business; Navient Corporation (NYSE:NAVI) — spun off with the federal loan servicing business and legacy private loan portfolio. This split is critical for forgiveness analysis: Sallie Mae Bank continues to originate NEW private student loans; Navient (later selling its private loan portfolio to third parties in various transactions) holds older Sallie Mae-branded loans that were originated before or around the 2014 split. When someone has a “Sallie Mae loan,” the actual current holder or servicer may be Sallie Mae Bank, Navient/Earnest, a securitized trust like NCSLT, or a debt buyer that acquired the loan after charge-off.
Sallie Mae Bank today
Sallie Mae Bank (SLM Corporation NYSE:SLM, headquartered Newark, DE) is the largest originator of private student loans in the United States, with a substantial book of Smart Option Student Loans, Sallie Mae Parent Loans, and Graduate Loan products. The bank services loans it originates directly through its Wilkes-Barre, PA operations. For sallie mae loan forgiveness analysis, loans originated after 2014 are typically still held and serviced by Sallie Mae Bank directly; loans originated before 2014 may be with Navient/Earnest, in a securitization trust, or with a debt buyer.
The NCSLT connection
Many Sallie Mae-originated private student loans, particularly those from 2001-2007, were pooled into National Collegiate Student Loan Trusts (NCSLT). These trusts have been the subject of extensive litigation regarding chain of assignment defects, standing challenges, and improper enforcement practices. If a borrower’s “Sallie Mae debt” is now held by NCSLT (typically evident from the plaintiff name in any collection lawsuit or the current owner named in credit reporting), the chain of assignment framework becomes particularly powerful — the Third Circuit’s March 19, 2024 decision and subsequent SCOTUS cert denial in December 2024 established covered persons analysis with substantial precedent for challenging NCSLT enforcement. See our related resource on private student loan forgiveness for the complete seven-path framework.
Identifying your actual Sallie Mae holder
The first step in any sallie mae debt forgiveness strategy is identifying who currently holds and services your debt. Sources of this information: (1) most recent loan statement — names both holder and servicer; (2) credit reports from all three bureaus — shows current furnisher; (3) prior collection letters — identifies collector but may not be current holder; (4) court filings if lawsuit exists — plaintiff is the party claiming ownership; (5) formal debt validation request under FDCPA 15 U.S.C. §1692g — requires complete debt documentation. This identification determines which specific forgiveness paths apply and to whom settlement or defensive filings should be directed.
Path 1: Settlement — get Sallie Mae loans forgiven for less than balance
Settlement is typically the most accessible path to get sallie mae student loans forgiven for a substantial portion of the balance. Rather than paying the full amount owed, the borrower negotiates with Sallie Mae Bank (or the current holder if the loan has been sold) to pay a reduced lump sum in full satisfaction of the debt. Settlement produces immediate loan forgiveness sallie mae at agreed reduced amounts and is legally binding once documented properly.
Sallie Mae Bank’s settlement posture
Sallie Mae Bank’s willingness to settle varies significantly based on loan status: Current or early delinquent — Sallie Mae typically pushes hardship programs, rate modifications, and payment plans rather than settlement, because the loan remains a performing asset; 90-180 days delinquent — settlement conversations become possible as the loan approaches charge-off; Charged-off status (typically 180+ days delinquent) — Sallie Mae may retain internal collection efforts or sell the debt to third-party debt buyers, with settlement opportunities at both stages; Sold to debt buyer — often the best settlement discounts because debt buyers purchased at pennies on the dollar; Pre-litigation — settlement typically preferred by both sides; Post-litigation or judgment — settlement still possible but from more constrained defensive position.
Realistic Sallie Mae settlement outcomes
Settlement outcomes with Sallie Mae vary based on loan status, defensive framework strength, borrower’s ability to pay lump sum, and specific circumstances. Approaching settlement from a position of defensive leverage — chain of assignment analysis (particularly relevant if NCSLT-related), statute of limitations status, credible bankruptcy alternative under Homaidan precedent — often produces materially better outcomes than passive settlement approaches. Working through legal counsel or a consulting firm familiar with the complete Sallie Mae defensive framework typically produces better outcomes than direct debtor-creditor negotiation from a passive posture.
Documenting Sallie Mae settlement
Any Sallie Mae settlement must be properly documented before payment. Essential settlement agreement elements: (1) exact settlement amount and payment terms; (2) explicit “full satisfaction” release language stating the payment satisfies the entire debt including principal, accrued interest, late fees, collection costs; (3) tradeline update instructions specifying how Sallie Mae will report to Experian, Equifax, and TransUnion following payment; (4) release of cosigner if the loan was cosigned (critical — settlement of the debt should release cosigner liability); (5) any specific covenants regarding disparagement, non-solicitation, or confidentiality if applicable. Never make a settlement payment without written settlement agreement signed by authorized Sallie Mae representative.
Tax implications of Sallie Mae settlement forgiveness
The forgiven portion of a Sallie Mae settlement is reported by Sallie Mae on Form 1099-C to the IRS as cancellation of debt income. This can create taxable income in the year of cancellation. IRC §108 provides important exclusions: Insolvency exclusion (IRC §108(a)(1)(B)) — cancelled debt is excluded from income to the extent the borrower was insolvent (liabilities exceeded assets) immediately before the cancellation; many borrowers pursuing settlement qualify because their financial distress often means they are insolvent; Bankruptcy exclusion (IRC §108(a)(1)(A)) — debt cancelled in Chapter 7 or 13 bankruptcy is excluded from income entirely. A CPA or tax professional experienced with debt cancellation should analyze §108 applicability before finalizing settlement.
Path 2: Bankruptcy discharge — Homaidan v. Sallie Mae precedent
Bankruptcy discharge is one of the most powerful — and most misunderstood — paths to sallie mae debt forgiveness. The prevailing myth that “student loans can never be discharged in bankruptcy” is outdated, particularly for Sallie Mae private loans following the landmark Second Circuit precedent Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021). Understanding how §523(a)(8) actually applies to Sallie Mae loans is essential to evaluating bankruptcy discharge as a forgiveness path.
The §523(a)(8) framework applied to Sallie Mae
11 U.S.C. §523(a)(8) makes certain educational loans non-dischargeable in bankruptcy unless “undue hardship” is shown. The categories: §523(a)(8)(A)(i) — loans made, insured, or guaranteed by governmental unit (Sallie Mae private loans generally NOT in this category since 2010 when SLM’s federal FFEL business ended); §523(a)(8)(A)(ii) — “obligation to repay funds received as an educational benefit, scholarship, or stipend” (Homaidan established this is narrow, excluding many private loans); §523(a)(8)(B) — “qualified education loan” as defined in IRC §221(d)(1) (has specific requirements many Sallie Mae loans fail to meet). Sallie Mae loans NOT falling into any of these categories are dischargeable in bankruptcy WITHOUT any undue hardship showing.
The Homaidan case — landmark for Sallie Mae borrowers
Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) is arguably the most important private student loan bankruptcy case of the last decade for Sallie Mae borrowers specifically. The plaintiff, Hilal Homaidan, filed Chapter 7 bankruptcy that included his Sallie Mae direct-to-consumer loans. Homaidan later brought an adversary proceeding contending that the loans had been discharged in the Chapter 7 (because they were not §523(a)(8)-protected) and that Sallie Mae’s continued collection efforts violated the discharge injunction. The Second Circuit affirmed the bankruptcy court’s ruling that Sallie Mae’s “direct-to-consumer” loans (loans made directly to students without school certification of the cost of attendance) do NOT qualify as “educational benefit” under §523(a)(8)(A)(ii) — meaning they are dischargeable without undue hardship showing. This precedent is binding in the Second Circuit (NY, CT, VT) and highly persuasive in other circuits.
Which Sallie Mae loans qualify under Homaidan
Sallie Mae loans potentially dischargeable without undue hardship under Homaidan analysis include: (1) direct-to-consumer loans without school certification of cost of attendance; (2) loans exceeding the cost of attendance limit for the applicable enrollment period; (3) loans for non-title IV eligible programs (some vocational programs, bar prep courses, non-degree programs); (4) loans made to students not enrolled at least half-time in eligible programs; (5) loans failing other IRC §221(d)(1) “qualified education loan” requirements. Each specific Sallie Mae loan requires case-by-case analysis of its origination documents and disbursement records to determine Homaidan eligibility.
Qualified Sallie Mae loans and Brunner undue hardship
Sallie Mae loans qualifying under §523(a)(8) require undue hardship showing. Most circuits apply the Brunner test from Brunner v. New York State Higher Education Services Corp. 831 F.2d 395 (2d Cir. 1987): (1) debtor cannot maintain minimal standard of living while repaying the loan; (2) additional circumstances indicate this situation is likely to persist for a significant portion of the repayment period; (3) debtor has made good faith efforts to repay. Recent case law including In re Rosenberg 594 B.R. 22 (Bankr. S.D.N.Y. 2020) and DOJ guidance on undue hardship (November 2022) have moderated the historically harsh Brunner application, making discharge somewhat more accessible for qualifying Sallie Mae loans.
Chapter 7 vs Chapter 13 for Sallie Mae discharge
Chapter 7 provides discharge in approximately 3-4 months of most unsecured debts including Sallie Mae loans qualifying under Homaidan analysis or with successful undue hardship showing. Chapter 13 involves 3-5 year payment plan with discharge under 11 U.S.C. §1328 at plan completion. Chapter selection depends on: means test qualification (Chapter 7 requires income below state median or successful means test analysis); asset preservation needs; whether payment plan restructuring benefits the overall situation; specific bankruptcy jurisdiction. Sallie Mae bankruptcy discharge requires bankruptcy counsel familiar with §523(a)(8) adversary proceeding practice.
Path 3: Sallie Mae Loan Modification and hardship programs
Sallie Mae Bank offers several formal hardship programs that provide meaningful sallie mae student loan relief for qualifying borrowers. While not “forgiveness” in the strictest sense, these programs can create breathing room, prevent charge-off, and support longer-term forgiveness strategy. Understanding Sallie Mae’s specific hardship programs is essential to comprehensive relief planning.
Sallie Mae Loan Modification Program
The Sallie Mae Loan Modification Program offers reduced interest rates and temporarily reduced payments for qualifying borrowers demonstrating hardship. Program elements typically include: reduced interest rate (often 4-6% depending on original rate and hardship documentation); reduced monthly payment for defined period; capitalization of unpaid interest or restructuring of accrued charges; ongoing eligibility review at defined intervals. Application requires: hardship documentation (job loss, medical hardship, income reduction, family circumstances); current financial statement showing income, expenses, assets, liabilities; supporting documentation for hardship claim. The program is discretionary — Sallie Mae is not obligated to approve any specific application.
Sallie Mae Rate Reduction Program
The Sallie Mae Rate Reduction Program provides temporary interest rate reduction for shorter periods (typically 12 months) with less extensive hardship documentation than full Loan Modification. This can be useful for borrowers experiencing temporary hardship rather than long-term financial distress. Rate reductions typically bring the rate down to 4-5% during the reduction period, then return to the original rate after the reduction period expires.
Sallie Mae Interest-Only Payment Program
The Sallie Mae Interest-Only Payment Program allows borrowers to pay only accrued interest for a defined period (typically 3-12 months) rather than principal-and-interest amortized payments. This significantly reduces monthly payment amount during the interest-only period but does not reduce the principal balance. Useful for temporary cash flow relief during hardship, but extends overall repayment timeline. Program is subject to Sallie Mae’s discretionary approval.
Sallie Mae Hardship Forbearance
Sallie Mae Hardship Forbearance temporarily suspends required monthly payments for qualifying borrowers. Standard availability is typically up to 12 months cumulative over the life of the loan, in 3-month increments requiring reapplication and updated documentation. During forbearance, interest continues to accrue and capitalize onto the principal balance at the end of the forbearance period — meaning forbearance provides temporary payment relief but increases overall debt cost. Forbearance should be a short-term bridge to more permanent solutions rather than a long-term strategy.
Application coordination with settlement or bankruptcy analysis
Hardship program applications should coordinate with the broader forgiveness framework: (1) hardship documentation supports later bankruptcy undue hardship showing if pursued; (2) hardship denial evidence supports later settlement discussions; (3) hardship approval provides breathing room to develop chain of assignment or SOL analysis; (4) forbearance can bridge to statute of limitations expiration in some cases. Uncoordinated hardship applications can inadvertently harm defensive framework — for example, making written acknowledgments of debt during hardship application when SOL has already expired can potentially revive time-barred debt in some jurisdictions.
Path 4: Sallie Mae cosigner release program
For cosigned Sallie Mae loans (which represent the majority of undergraduate Sallie Mae Smart Option Student Loans), cosigner release is a form of partial sallie mae loan forgiveness — the cosigner is legally released from continuing obligation on the debt, though the primary borrower remains liable. Sallie Mae offers one of the more accessible cosigner release programs among major private lenders.
Sallie Mae cosigner release eligibility criteria
Sallie Mae cosigner release requires meeting all of the following criteria: (1) 12 consecutive on-time principal-and-interest payments — payments must be full scheduled amount, must be on time (no more than late by Sallie Mae’s defined grace period), and interest-only payments during in-school or grace period generally do NOT count; the 12 consecutive payments must be in the standard repayment phase; (2) borrower creditworthiness demonstration — borrower must independently qualify for the loan based on current income, credit history, and debt-to-income ratio without cosigner support; (3) account in good standing — no delinquency, no forbearance during the qualifying period, no modification of terms; (4) completion of any required education program — for loans still in in-school or grace status, program completion is typically required.
Application process
Cosigner release application through Sallie Mae involves: (1) confirming eligibility through Sallie Mae online account or customer service; (2) completing formal cosigner release application; (3) submitting supporting income documentation for borrower creditworthiness review; (4) Sallie Mae underwriting review typically 30-60 days; (5) approval or denial notification with reasons. If denied, borrower can typically reapply after 12 additional months of qualifying payments and improved financial situation. If approved, the cosigner is legally released from further obligation on the loan.
Refinance to eliminate Sallie Mae cosigner
Refinance in the primary borrower’s name alone eliminates the Sallie Mae cosigner entirely. The Sallie Mae loan is paid in full through refinance proceeds, and the new loan (with a different lender or Sallie Mae’s own refinance product) is issued to the borrower alone. Refinance requirements typically include: adequate borrower income for independent qualification; acceptable credit profile (typically 680+ credit score); debt-to-income ratio within lender parameters. Refinance offers cosigner release regardless of whether the current Sallie Mae loan qualifies for the formal release program — useful for borrowers who cannot meet the 12-consecutive-payment threshold or the creditworthiness criteria.
Cosigner release through settlement or discharge
Settlement or bankruptcy discharge of the underlying Sallie Mae loan also effectively releases the cosigner because the underlying debt is eliminated. For cosigners primarily concerned with their own liability exposure, supporting the primary borrower’s pursuit of settlement or bankruptcy discharge under Homaidan analysis may be the most effective cosigner release path — particularly if the formal cosigner release program is not accessible due to payment history or creditworthiness issues.
Related resources — Sallie Mae debt forgiveness ecosystem
Private Student Loan Forgiveness 2026: Complete Guide (PILAR)
The complete seven-path framework covering all private student loans including Sallie Mae, Navient/Earnest, Discover/Firstmark, SoFi, Citizens, Ascent.
Private Student Loan Bankruptcy Discharge Guide 2026
Complete §523(a)(8) framework with Homaidan Second Circuit precedent analysis, Brunner test, and adversary proceeding practice.
Private Student Loan Chain of Assignment Defense 2026
Article III standing challenges for NCSLT-related Sallie Mae debt with Third Circuit precedent and post-judgment application.
Path 5: Statute of limitations for Sallie Mae debt
Statute of limitations expiration is a powerful path to sallie mae loan relief for older Sallie Mae debt. When the SOL expires under applicable state law, Sallie Mae or the current holder loses the legal ability to file a lawsuit to collect the debt. Understanding SOL analysis for Sallie Mae debt requires identifying the applicable state law, the accrual date, and any factors that may have restarted or tolled the SOL clock.
Applicable state law for Sallie Mae debt SOL
SOL analysis begins with identifying which state’s law applies. Sallie Mae loan promissory notes typically include a choice-of-law provision (often Delaware where Sallie Mae Bank is chartered, or Utah where some Sallie Mae products originated). However, borrower’s state of residence and state where any lawsuit is filed also affect the analysis under conflict-of-laws principles. Courts have reached varying conclusions on whether borrower state SOL or contract choice-of-law state SOL applies for Sallie Mae debt — the specific analysis depends on jurisdiction and facts.
SOL by common borrower states
SOL periods for written contract debt (Sallie Mae loans) by common borrower states: Texas 4 years under Tex. Civ. Prac. & Rem. Code §16.004(a)(3); New York 3 years under CPLR §214(2) per the Consumer Credit Fairness Act (CCFA) effective April 7, 2022 (reduced from 6 years — a major change for NY Sallie Mae borrowers); Pennsylvania 4 years under 42 Pa.C.S. §5525; Ohio 6 years under Ohio R.C. §2305.06 (reduced from 8 years effective 2021); Illinois 10 years under 735 ILCS 5/13-206; Georgia 6 years under O.C.G.A. §9-3-24; California 4 years under CCP §337; Florida 5 years under Fla. Stat. §95.11(2)(b); Delaware 3 years under 10 Del. C. §8106 (relevant given Sallie Mae Bank’s Delaware charter). Accrual is typically date of first default or last payment depending on state.
Revival concerns specific to Sallie Mae debt
Borrowers with older Sallie Mae debt should avoid actions that could restart or extend the SOL clock: making any payment on the debt (even a small “goodwill” payment) may restart the SOL clock in many states; written acknowledgment of the debt including hardship program applications, settlement offers, or promise to pay may create restart; new agreement or written promise to pay resets the timing. Sallie Mae collectors and debt buyers sometimes solicit small payments or written communications specifically to revive time-barred debt. Consulting with legal counsel before communicating with Sallie Mae or its debt collectors on old debt is essential to avoid inadvertent revival.
Defensive application when Sallie Mae SOL has expired
When SOL has expired on Sallie Mae debt: (1) the debt still legally exists but Sallie Mae/current holder cannot legally file suit to collect; (2) collection calls and letters can be disputed and limited under FDCPA if third-party collector involved; (3) if lawsuit is filed on time-barred debt, motion to dismiss based on SOL expiration typically succeeds and may support FDCPA counterclaim; (4) credit reporting continues under 7-year FCRA reporting period regardless of SOL; (5) settlement or resolution of time-barred debt should proceed carefully to avoid revival. The SOL expiration effectively provides debt forgiveness for private student loans by making the debt uncollectible through litigation.
Path 6: Chain of assignment defense — NCSLT and Sallie Mae
Chain of assignment defense is particularly powerful for older Sallie Mae debt that has been securitized into National Collegiate Student Loan Trusts (NCSLT) or sold to third-party debt buyers. Article III standing requires the plaintiff to demonstrate a complete chain of ownership from Sallie Mae as original lender through any intermediate holders to the current plaintiff. Defects in this chain provide grounds for dismissal — effectively achieving how to get rid of sallie mae loans through legal proceedings.
Article III standing doctrine applied to Sallie Mae debt
Article III standing established in Lujan v. Defenders of Wildlife 504 U.S. 555 (1992), refined in Spokeo, Inc. v. Robins 578 U.S. 330 (2016), and further developed in TransUnion LLC v. Ramirez 594 U.S. 413 (2021) requires: (1) concrete and particularized injury; (2) causally connected to defendant’s conduct; (3) redressable by court decision. For a plaintiff to sue on Sallie Mae debt, they must establish ownership through complete assignment documentation from Sallie Mae through any intermediate holders to themselves. Standing is jurisdictional and can be raised at any stage of proceedings, including post-judgment through motion to vacate.
NCSLT-specific analysis for Sallie Mae borrowers
National Collegiate Student Loan Trusts (NCSLT) hold substantial portfolios of Sallie Mae-originated loans, particularly from 2001-2007. NCSLT litigation has developed extensive precedent for chain of assignment challenges. Key developments include: the Third Circuit’s March 19, 2024 decision establishing “covered persons” analysis under the Consumer Financial Protection Act; SCOTUS cert denial in December 2024 leaving the Third Circuit precedent in place; various stipulated resolutions and consent orders through 2026. Borrowers with Sallie Mae debt now held by NCSLT have documented pathways to challenge creditor standing, potentially achieving complete debt forgiveness for private student loans through motion to dismiss or motion to vacate judgment on standing grounds.
Debt buyer chain analysis
Sallie Mae debt sold to third-party debt buyers after charge-off often has documentation gaps between the original Sallie Mae ownership and the current debt buyer’s asserted ownership. Common defects: missing intermediate assignment documentation showing continuous ownership chain; assignments executed without adequate documentation of the specific debts included in the bulk sale; blank endorsements without allonge chain establishing endorsement history; discrepancies between Sallie Mae servicing records and asserted debt buyer ownership. Debt buyers typically purchase Sallie Mae portfolios at pennies on the dollar and may not have obtained complete assignment documentation for individual loans — creating standing challenges.
Post-judgment application
Because standing is jurisdictional, chain of assignment challenges are preserved even after judgment has been entered on Sallie Mae debt. Motion to vacate under FRCP 60(b)(4) (void judgment) can be filed at any time if the underlying judgment was entered without proper plaintiff standing. This is particularly relevant for older default judgments where the borrower did not appear or contest at the time — the standing challenge remains available years or decades later. Recent Sallie Mae/NCSLT judgment vacation successes have established practical framework for this approach.
Path 7: Sallie Mae death and disability discharge
Sallie Mae Bank offers death and disability discharge programs for qualifying situations, providing sallie mae loan forgiveness through contract terms rather than statutory forgiveness. These programs are important for family financial planning and for borrowers facing serious disability situations.
Sallie Mae death discharge policy
Sallie Mae discharges the borrower’s remaining balance on death upon submission of required documentation (death certificate typically required within 60 days of death). For cosigned loans originated in 2015 or later, the cosigner is also released from further obligation upon borrower’s death — an important protection that many older cosigners on pre-2015 Sallie Mae loans do NOT have. Estate administrators should promptly notify Sallie Mae of borrower death with proper documentation to activate discharge processing. Families should not make payments on Sallie Mae loans of a deceased borrower before confirming the discharge has been processed — such payments may be reclaimable but complicate the discharge process.
Sallie Mae Total and Permanent Disability discharge
Sallie Mae offers Total and Permanent Disability (TPD) discharge for qualifying borrowers who become permanently disabled and unable to work. Documentation requirements typically include: physician certification of permanent disability meeting Sallie Mae’s specific criteria (which may or may not exactly match federal TPD standards); medical records supporting the disability determination; income and employment status verification. Sallie Mae’s TPD program is discretionary and requires case-by-case evaluation — borrowers denied on initial application can appeal with additional documentation.
Estate and family planning considerations
Death and disability discharge policies affect family financial planning: (1) Sallie Mae death discharge means the borrower’s death eliminates the debt, protecting family assets; (2) for cosigned loans originated 2015 or later, cosigner is also protected; (3) for older cosigned Sallie Mae loans, cosigner exposure may continue after borrower death — cosigner should evaluate release options during borrower’s lifetime; (4) life insurance coordination with debt considerations provides additional protection regardless of discharge policies; (5) coordination with overall estate planning addresses these considerations comprehensively.
Choosing your Sallie Mae debt forgiveness path
Decision framework by Sallie Mae loan status
The right sallie mae debt forgiveness path depends on specific circumstances: Current but struggling — Sallie Mae Loan Modification Program, Rate Reduction, potentially Interest-Only Payment Program; evaluate cosigner release if 12 payments completed; refinance if independent qualification possible; Recently delinquent (30-90 days) — hardship forbearance to prevent charge-off, then evaluate longer-term forgiveness options; Charged-off Sallie Mae debt — settlement negotiation typically most cost-effective, chain of assignment analysis if held by NCSLT or debt buyer, SOL analysis; Lawsuit filed by Sallie Mae or successor — motion to dismiss on standing (chain of assignment), SOL defense if time-barred, settlement from defensive position, bankruptcy analysis; Judgment entered on Sallie Mae debt — motion to vacate on standing grounds preserved under FRCP 60(b)(4), settlement negotiation; Long-standing Sallie Mae debt near or past SOL — careful SOL analysis, avoid revival, potential settlement with time-barred debt awareness; Serious financial distress — bankruptcy analysis including Homaidan §523(a)(8) framework for Sallie Mae direct-to-consumer loans; Death or permanent disability — Sallie Mae discharge application.
Combining multiple Sallie Mae forgiveness paths
Effective Sallie Mae relief often combines multiple paths: chain of assignment analysis creating settlement leverage if NCSLT-held; SOL analysis creating urgency for settlement; bankruptcy analysis under Homaidan as credible alternative supporting settlement negotiation; hardship program buying time to evaluate longer-term options; cosigner release combined with refinance analysis. The best how to get sallie mae loans forgiven outcome often emerges from coordinated multi-path strategy rather than pursuing any single path in isolation.
Working with professional resources
Given the complexity of the seven paths and Sallie Mae-specific considerations, working with professional resources typically produces better outcomes than DIY approaches. Options include: bankruptcy counsel familiar with Homaidan precedent application for §523(a)(8) analysis; state-licensed attorneys for chain of assignment challenges (particularly NCSLT-related); consulting firms with Sallie Mae portfolio experience for settlement negotiation; CPAs for §108 tax analysis around settlement forgiveness. Private Student Relief’s attorney-backed partner provider network coordinates these resources for comprehensive sallie mae student loan relief analysis.
Common Sallie Mae debt forgiveness myths and misconceptions
Myth 1
“Sallie Mae loans qualify for PSLF, IDR forgiveness, or new federal programs”
Reality: Sallie Mae is a private lender (SLM Corporation NYSE:SLM). Federal forgiveness programs — Public Service Loan Forgiveness (PSLF), Income-Driven Repayment (IDR) forgiveness, Teacher Loan Forgiveness, and executive-action forgiveness proposals — apply ONLY to federal loans. Sallie Mae private loans are NOT eligible for any of these programs. Real sallie mae debt forgiveness requires the seven paths covered in this guide (settlement, bankruptcy discharge under Homaidan, Sallie Mae Loan Modification, cosigner release, statute of limitations, chain of assignment, death/disability discharge).
Myth 2
“Sallie Mae loans cannot be discharged in bankruptcy”
Reality: Many Sallie Mae loans ARE dischargeable in bankruptcy following the Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) Second Circuit precedent. Sallie Mae direct-to-consumer loans (without school certification of cost of attendance) are dischargeable without undue hardship showing. Sallie Mae loans that qualify under §523(a)(8) require undue hardship showing through Brunner or totality of circumstances test, but recent case law has made this more accessible. The outdated myth that “student loans can never be discharged” is not accurate for many Sallie Mae loans.
Myth 3
“Sallie Mae will not settle for less than the full balance”
Reality: Sallie Mae Bank and successors do settle Sallie Mae debt for less than full balance, particularly for charged-off accounts or accounts sold to debt buyers. Settlement outcomes depend on loan status, defensive framework strength, and negotiation approach. Approaching Sallie Mae settlement from position of defensive leverage (chain of assignment analysis, SOL status, bankruptcy alternative under Homaidan) typically produces better results than passive settlement approaches. Settlement is one of the most accessible forms of loan forgiveness sallie mae borrowers achieve.
Myth 4
“There’s a special government Sallie Mae forgiveness program you can apply to”
Reality: There is NO government program that forgives Sallie Mae private loans on application. Any company or website claiming to have “government approved” Sallie Mae forgiveness programs is misrepresenting the law. Real sallie mae student loans forgiven outcomes work through the seven paths in this guide — negotiated settlement, bankruptcy discharge under Homaidan, Sallie Mae’s own hardship programs, statute of limitations, chain of assignment challenges. Be alert to scam operators exploiting confusion about federal versus private loan forgiveness.
Frequently asked questions about Sallie Mae debt forgiveness
1. Can Sallie Mae loans really be forgiven?
Yes, sallie mae debt forgiveness is achievable through seven established paths: settlement with Sallie Mae Bank or current holder for less than full balance; bankruptcy discharge under 11 U.S.C. §523(a)(8) with Homaidan v. Sallie Mae Second Circuit precedent for direct-to-consumer and non-qualified loans; Sallie Mae Loan Modification Program with reduced interest rates and payments; statute of limitations expiration under state law; Sallie Mae cosigner release program; chain of assignment defense particularly for NCSLT-held debt; death and disability discharge. What is NOT available is federal-style forgiveness (PSLF, IDR) which does not apply to Sallie Mae private loans.
2. How do I get rid of Sallie Mae loans that I cannot afford?
Path depends on situation. If current but struggling: Sallie Mae Loan Modification Program, Rate Reduction, or Interest-Only Payment Program provide payment relief. If delinquent or charged-off: settlement negotiation typically achieves substantial discount; chain of assignment analysis for NCSLT-related debt may achieve complete dismissal. If facing lawsuit: motion to dismiss on standing or SOL grounds; settlement from defensive position. If serious financial distress: bankruptcy analysis under Homaidan for Sallie Mae direct-to-consumer loans potentially achieves full discharge without undue hardship showing. Professional evaluation identifies the best path for specific circumstances.
3. Does Sallie Mae have a loan forgiveness program?
Sallie Mae Bank does not have a “loan forgiveness program” in the federal PSLF/IDR sense. Sallie Mae does offer several relief programs: Loan Modification Program with reduced interest rates and payments; Rate Reduction Program for shorter-term relief; Interest-Only Payment Program; Hardship Forbearance; Cosigner Release Program (after 12 consecutive on-time principal-and-interest payments plus criteria); Death Discharge; Total and Permanent Disability Discharge. Additionally, external paths to sallie mae loan forgiveness include settlement negotiation, bankruptcy discharge under Homaidan §523(a)(8), statute of limitations, and chain of assignment defense.
4. Will Sallie Mae ever forgive my loans?
Sallie Mae will not forgive loans through federal-style programs (which don’t exist for private loans), but real sallie mae student loan relief is achievable through the seven paths. Settlement forgives the portion above the settlement payment (often 40-70% discount depending on circumstances). Bankruptcy discharge under Homaidan can eliminate the debt entirely for qualifying Sallie Mae loans. Statute of limitations expiration makes debt uncollectible. Chain of assignment defense can dismiss cases entirely. Cosigner release forgives cosigner exposure. Death/disability discharge forgives debt in qualifying situations. The specific forgiveness that works depends on the specific circumstances.
5. How do I get Sallie Mae loans forgiven if they’re in collection?
Sallie Mae debt in collection typically means the debt has been charged off and referred to internal or external collection, or sold to a debt buyer. Options: (1) settlement negotiation — collection status often produces better settlement terms because collectors and debt buyers acquired at discounts; (2) chain of assignment challenge — collection sales often have documentation gaps supporting standing challenges; (3) statute of limitations analysis — check whether SOL has expired under applicable state law; (4) bankruptcy discharge under Homaidan if qualifying; (5) formal debt validation request under FDCPA 15 U.S.C. §1692g to require complete debt documentation. Working with attorney or specialist familiar with private student loan collection defense produces better outcomes than DIY approaches.
6. Can I discharge Sallie Mae loans in bankruptcy?
Yes, many Sallie Mae loans can be discharged in bankruptcy following the Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) Second Circuit precedent. Sallie Mae direct-to-consumer loans (made directly to students without school certification of cost of attendance) qualify for discharge without undue hardship showing because they don’t fall within §523(a)(8) categories. Sallie Mae qualified education loans under IRC §221(d)(1) require undue hardship showing through Brunner test — accessible but requires adversary proceeding. Chapter 7 provides discharge in approximately 3-4 months; Chapter 13 involves 3-5 year plan with §1328 discharge at completion. Bankruptcy counsel familiar with Homaidan precedent application is essential.
7. What is Sallie Mae’s cosigner release program?
Sallie Mae’s cosigner release program releases the cosigner from further obligation on a Sallie Mae Smart Option Student Loan after all of the following are met: (1) 12 consecutive on-time principal-and-interest payments (interest-only payments in in-school or grace period generally don’t count; payments must be full scheduled amount and on time within Sallie Mae’s grace period); (2) borrower independently demonstrates creditworthiness based on current income, credit history, and debt-to-income ratio; (3) account in good standing with no delinquency or forbearance during qualifying period. Application through Sallie Mae online account or customer service, underwriting review typically 30-60 days. If denied, borrower can reapply after 12 additional months. Alternative: refinance in borrower’s name only eliminates cosigner regardless of program eligibility.
Need Sallie Mae Debt Forgiveness or Relief?
Free specialist review of your Sallie Mae forgiveness options.
Settlement negotiation analysis with Sallie Mae Bank or current holder, bankruptcy discharge evaluation under Homaidan §523(a)(8) precedent, Sallie Mae Loan Modification qualification, cosigner release strategy, statute of limitations by state, chain of assignment defensive framework for NCSLT-related debt, and coordinated approach across all seven paths to sallie mae debt forgiveness. Free eligibility review with attorney-backed partner provider — no upfront fees.
Get a free eligibility review →
5-minute review · No obligation · Zero upfront fees · Since 2015 · 48 states served
About the author
Henry Silva — Private Student Loan Debt Specialist
10+ years experience specifically with Sallie Mae portfolios including Sallie Mae Bank (SLM Corporation NYSE:SLM) direct settlement negotiation, Navient/Earnest Operations LLC portfolio analysis for pre-2014 Sallie Mae loans, NCSLT (National Collegiate Student Loan Trust) chain of assignment challenges for securitized Sallie Mae-originated loans, Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) bankruptcy discharge precedent application, Brunner v. New York State Higher Education Services Corp. 831 F.2d 395 (2d Cir. 1987) undue hardship analysis for qualifying Sallie Mae loans, Sallie Mae Loan Modification Program qualification, cosigner release program (12 consecutive on-time principal-and-interest payments plus creditworthiness criteria), statute of limitations analysis across all 50 states, IRC §108 tax analysis for settlement forgiveness, and coordinated multi-path sallie mae debt forgiveness strategy. Henry works with Private Student Relief’s attorney-backed partner provider network to review individual Sallie Mae relief scenarios.
Legal Disclaimer and Sources
This article is provided for informational purposes only and does not constitute legal, tax, or financial advice. Private Student Relief is a consulting and matching organization operated by Joco (555 Anton Blvd, Suite 368, Costa Mesa, CA 92626) — not a law firm, debt settlement company, debt consolidation company, or loan provider. Debt validation services are performed by an attorney-backed partner provider (Panamerican Consulting LLC, Las Vegas, NV) under independent business credentials. Ratings, BBB accreditation, and AADR membership referenced on the PSR website belong to the partner provider. Sallie Mae debt forgiveness pathway availability depends on loan characteristics, current holder or servicer, borrower circumstances, and jurisdiction. Individual results vary. Since 2015. 48 states served. Not available in South Carolina or Mississippi.
Corporate references: SLM Corporation (NYSE:SLM), headquartered Newark, Delaware — the parent of Sallie Mae Bank. April 2014 corporate split separating Sallie Mae Bank (private student loan origination) from Navient Corporation (NYSE:NAVI) which took federal loan servicing business. Navient’s private loan business now largely operated through Earnest Operations LLC (subsidiary since 2017 acquisition). National Collegiate Student Loan Trusts (NCSLT) hold substantial portfolios of Sallie Mae-originated loans, particularly from 2001-2007.
Bankruptcy Code references: 11 U.S.C. §523(a)(8) (student loan discharge exceptions with §523(a)(8)(A)(i) governmental unit, §523(a)(8)(A)(ii) educational benefit, §523(a)(8)(B) qualified education loan categories); 11 U.S.C. §362 (automatic stay); 11 U.S.C. §707(b)(2) (means test); 11 U.S.C. §1328 (Chapter 13 discharge). Key precedent: Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) — Sallie Mae direct-to-consumer loans dischargeable without undue hardship; Brunner v. New York State Higher Education Services Corp. 831 F.2d 395 (2d Cir. 1987) — undue hardship test; In re Rosenberg 594 B.R. 22 (Bankr. S.D.N.Y. 2020) — updated Brunner application; McDaniel v. Navient Solutions LLC 973 F.3d 1083 (10th Cir. 2020); Crocker v. Navient Solutions LLC 941 F.3d 206 (5th Cir. 2019). Article III standing precedent: Lujan v. Defenders of Wildlife 504 U.S. 555 (1992); Spokeo, Inc. v. Robins 578 U.S. 330 (2016); TransUnion LLC v. Ramirez 594 U.S. 413 (2021). Internal Revenue Code: IRC §221(d)(1) (qualified education loan definition); IRC §108(a)(1)(A) (bankruptcy exclusion); IRC §108(a)(1)(B) (insolvency exclusion). FDCPA: 15 U.S.C. §1692g (debt validation).
Statute of limitations for written contract debt (private student loans including Sallie Mae) by state: Texas 4 years under Tex. Civ. Prac. & Rem. Code §16.004(a)(3); New York 3 years under CPLR §214(2) per Consumer Credit Fairness Act (CCFA) effective April 7, 2022; Pennsylvania 4 years under 42 Pa.C.S. §5525; Ohio 6 years under Ohio R.C. §2305.06 (reduced 2021); Illinois 10 years under 735 ILCS 5/13-206; Georgia 6 years under O.C.G.A. §9-3-24; California 4 years under CCP §337; Florida 5 years under Fla. Stat. §95.11(2)(b); Delaware 3 years under 10 Del. C. §8106. Complete state SOL analysis should be verified against current statutes for each specific borrower situation.
Sallie Mae debt forgiveness strategy requires case-by-case analysis coordinating loan characteristics, Sallie Mae or current holder identification, chain of assignment history, borrower jurisdiction, defensive framework opportunities, and specific circumstances. This article provides general framework information; specific settlement negotiations with Sallie Mae Bank or successor holders, bankruptcy filings under Homaidan precedent, chain of assignment challenges (particularly NCSLT-related), Sallie Mae Loan Modification Program applications, cosigner release strategies, and coordinated multi-path approaches must be evaluated for each borrower’s individual situation by counsel or consulting resources familiar with the complete sallie mae debt forgiveness framework. Last reviewed: September 2026.