Informational content only. Not legal, tax, or financial advice. Private Student Relief is a consulting organization, not a law firm. Debt validation services are executed by an attorney-backed partner provider. Navient settlement outcomes depend on loan characteristics, account status, borrower circumstances, and jurisdiction. Last reviewed: October 2026.
Written by Henry Silva
Private Student Loan Debt Specialist · 10+ years negotiating Navient student loan settlement outcomes with Navient Corporation (NYSE:NAVI) and subsidiary Earnest Operations LLC (acquired 2017 for $155M) across all account statuses. Deep expertise in Navient’s corporate transformation history (2014 Sallie Mae split, 2017 Earnest acquisition, December 2021 Aidvantage transfer completing federal loan exit, January 2022 $1.85B state attorneys general settlement), defensive leverage integration using Crocker v. Navient 941 F.3d 206 (5th Cir. 2019) and McDaniel v. Navient 973 F.3d 1083 (10th Cir. 2020) §523(a)(8) precedents, Article III standing analysis (Lujan/Spokeo/TransUnion), chain of assignment challenges, Earnest-specific accommodation framework, and IRC §108 tax planning. Last reviewed: October 2026.
A Navient student loan settlement is a negotiated agreement with Navient Corporation (NYSE:NAVI) or its subsidiary Earnest Operations LLC in which the borrower pays a reduced lump sum in full satisfaction of the private student loan debt. For borrowers struggling with Navient private student loan balances, settlement typically produces 35-55% discount from the full balance for charged-off accounts — meaning a $75,000 balance might settle for $26,000-$41,000, forgiving the remainder entirely. Navient’s unique corporate history and the Crocker/McDaniel Circuit Court precedents create specific settlement dynamics distinct from Sallie Mae or other private lenders. This complete 2026 guide covers how Navient settlement actually works post-federal exit, realistic outcomes by account status, 6 proven paths to successful settlement, defensive leverage integration using Fifth and Tenth Circuit §523(a)(8) precedents, Earnest-specific framework, IRC §108 tax planning, and the complete framework for executing a Navient settlement that protects borrower interests.
Quick Answer
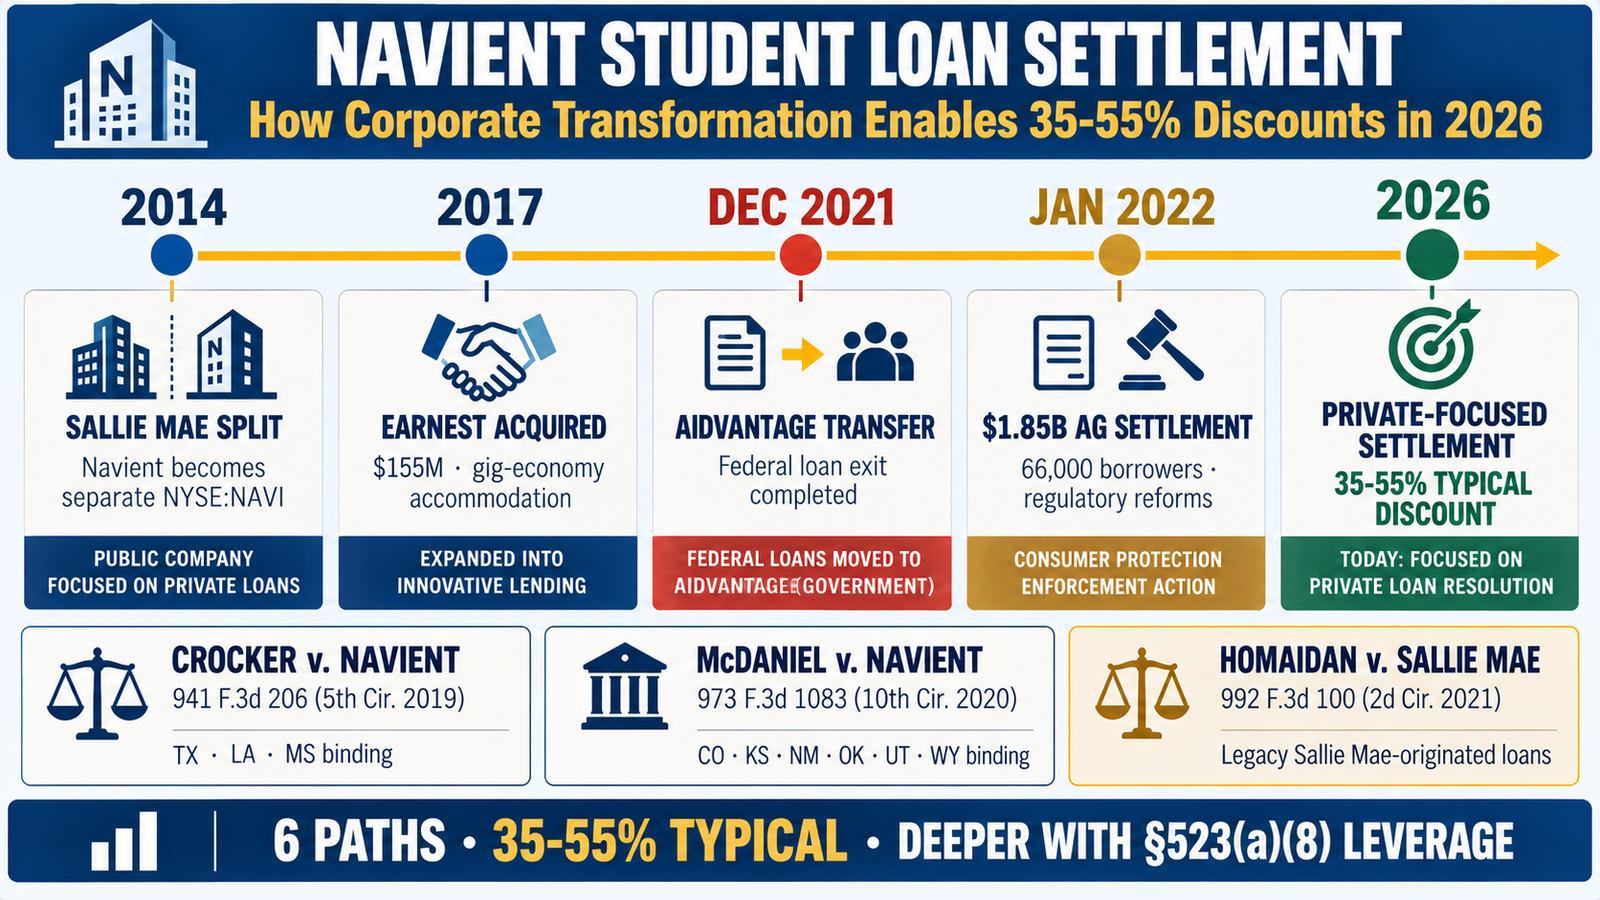
A Navient student loan settlement is a negotiated written agreement with Navient Corporation (NYSE:NAVI) or subsidiary Earnest Operations LLC where the borrower pays a reduced lump sum in full satisfaction of the private student loan debt — typically 35-55% of balance for charged-off accounts. Following Navient’s December 2021 Aidvantage transfer completing federal loan exit and January 2022 $1.85B state attorneys general settlement, Navient now focuses primarily on private student loans with distinct settlement dynamics. Six proven paths produce successful outcomes in 2026: (1) direct settlement with Navient recovery on charged-off accounts — typical range 40-55%; (2) Earnest Operations LLC settlement with gig-economy accommodation framework — typical range 45-60%; (3) defensive settlement with Crocker v. Navient 941 F.3d 206 (5th Cir. 2019) and McDaniel v. Navient 973 F.3d 1083 (10th Cir. 2020) §523(a)(8) bankruptcy alternative leverage — often 25-45%; (4) chain of assignment settlement for Navient-originated loans transferred to NCSLT trusts or debt buyers — 20-40%; (5) pre-litigation settlement before charge-off — 50-70%; (6) structured settlement with 3-6 month payment plan when full lump sum unavailable. The forgiven settlement portion is reported on IRS Form 1099-C but typically excluded from taxable income under IRC §108(a)(1)(B) insolvency exclusion. Approaching Navient settlement from defensive leverage position using Fifth/Tenth Circuit precedents produces materially better outcomes.
Read the complete Navient settlement framework below.
In this complete Navient settlement guide:
Navient’s corporate transformation and settlement implications
2014 split, 2017 Earnest, 2021 Aidvantage, 2022 $1.85B settlement
Path 1: Direct Navient recovery settlement
40-55% range outcomes for charged-off accounts
Path 2: Earnest Operations LLC settlement
45-60% range with gig-economy accommodation framework
Path 3: Defensive settlement with Crocker/McDaniel leverage
25-45% range using Fifth/Tenth Circuit §523(a)(8) precedent
Path 4: Chain of assignment for transferred Navient debt
NCSLT and debt buyer settlement when transferred from Navient
Path 5: Pre-litigation settlement before charge-off
50-70% range opportunity in late delinquency window
Path 6: Structured settlement with payment plan
3-6 month payment structure when lump sum unavailable
Navient’s corporate transformation and settlement implications
Understanding how to settle Navient loans requires understanding Navient’s corporate transformation over the past decade. The company has undergone several major structural changes that directly affect current settlement dynamics — making 2026 Navient settlement meaningfully different from Navient settlement in prior years.
2014 Sallie Mae split
Navient Corporation (NYSE:NAVI) was created in 2014 when the historical Sallie Mae organization split into two publicly traded companies: Sallie Mae Bank (NYSE:SLM) focusing on origination of new private student loans, and Navient Corporation (NYSE:NAVI) focusing on servicing of existing loan portfolios (both federal and private). Many pre-2014 Sallie Mae-originated private loans transferred to Navient as part of this corporate separation. Borrowers with older private loans originated by Sallie Mae but now serviced by Navient should understand this history when approaching settlement.
2017 Earnest acquisition
In 2017, Navient acquired Earnest Operations LLC for $155 million. Earnest had been established as a technology-focused private student loan refinance lender with more accommodating underwriting of alternative income sources (gig workers, self-employed, non-traditional credit profiles). Earnest continues operating as Navient subsidiary with distinct brand identity and somewhat distinct accommodation framework. Borrowers with Earnest-branded loans have access to settlement framework that may differ from direct Navient settlement despite common corporate parent.
December 2021 Aidvantage transfer
In December 2021, Navient transferred servicing of its federal student loan portfolio to Aidvantage (operated by Maximus Federal Services), completing Navient’s exit from federal loan servicing. Since this transition, Navient has focused entirely on private student loans. For borrowers asking about Navient settlement in 2026, this means: (1) Navient no longer services federal loans — any Navient loan is a private loan; (2) Navient’s internal operations are now oriented exclusively around private loan portfolio management; (3) private loan settlement discussions with Navient are now the central operational focus rather than a secondary activity.
January 2022 $1.85 billion state AG settlement
In January 2022, Navient reached a $1.85 billion settlement with 39 state attorneys general resolving allegations of predatory lending and improper servicing practices. This settlement included: $1.7 billion in private student loan debt cancellation for approximately 66,000 borrowers; $95 million in restitution to approximately 350,000 federal loan borrowers; and various procedural reforms. For borrowers approaching Navient settlement, this history provides context: Navient has incentive to resolve collection issues through settlement rather than face additional regulatory and litigation exposure. The 2022 settlement framework may also provide reference points for individual settlement discussions.
Path 1: Direct Navient recovery settlement
Direct Navient debt settlement on charged-off accounts is the most common path and typically produces 40-55% range outcomes. Once a Navient private student loan has been charged off (180 days past due), the account transitions to Navient’s internal recovery operations with explicit settlement authority.
Navient recovery operations structure
Navient’s recovery operations handle charged-off private student loan accounts with internal settlement authority tiered by account age and collection history. Recently charged-off accounts (6-12 months) typically settle in 45-55% range; moderately aged (12-24 months) 40-50%; older charged-off (24+ months) 35-50%. Settlement representatives have authority within these ranges; outside the normal range requires supervisor escalation. Navient’s post-federal-exit focus means recovery operations receive more organizational attention and resources than during the dual-focus period.
Legacy Sallie Mae-originated loans at Navient
Many loans currently held by Navient were originally originated by pre-2014 Sallie Mae and transferred during the corporate split. These legacy loans sometimes have documentation characteristics that support defensive leverage (direct-to-consumer characteristics, cost of attendance issues, program eligibility questions). Settlement discussions for legacy Sallie Mae-originated loans at Navient should include analysis of whether Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) framework applies — potentially adding substantial leverage beyond standard Navient settlement ranges.
Lump sum requirements and payment timing
Navient typically requires lump sum payment within 30-60 days of settlement agreement execution for best terms. Payment plans available but typically increase total settlement amount by 10-20%. Lump sum funding alternatives: personal savings; family assistance with documented terms; sale of non-essential assets; 401(k) loan with careful analysis; tax refund proceeds; year-end bonus or commission timing. Lump sum capability improves settlement outcome and should be confirmed before initiating formal negotiation.
Settlement agreement documentation requirements
Proper Navient settlement agreement must document: (1) exact settlement amount and payment deadline; (2) specific account identification with Navient loan number; (3) “full and final satisfaction” release language extinguishing all further obligations on this specific account; (4) tradeline update instructions to Experian, Equifax, TransUnion marking account as “settled”; (5) cosigner release for cosigned loans; (6) 1099-C reporting disclosure; (7) release of any pending collection activities. Never execute payment without receiving executed settlement agreement in writing from Navient.
Path 2: Earnest Operations LLC settlement
Earnest settlement approach applies to Earnest-branded loans held by Earnest Operations LLC (Navient subsidiary since 2017 acquisition). Earnest maintains distinct brand identity and somewhat distinct accommodation framework despite common corporate parent, with settlement outcomes typically 45-60% range for charged-off accounts.
Earnest’s distinct accommodation framework
Earnest Operations LLC maintains more accommodating practices than direct Navient for alternative income sources: gig economy workers (rideshare, delivery, freelance); self-employed professionals with 1099 income; borrowers with non-traditional credit profiles; borrowers whose income varies by month or season. This accommodation extends to settlement discussions where documented alternative income sources are credited rather than dismissed as insufficient. For borrowers with non-W-2 income facing Earnest-branded loan default, this framework often produces more favorable settlement outcomes than standard private lender approaches would suggest.
Earnest hardship accommodation programs
Before pursuing Earnest settlement, consider Earnest’s hardship programs: skip-a-payment feature (one skipped payment per 12-month period available for current accounts); hardship forbearance; modified payment plans. For borrowers who could sustain reduced payments but not current full payments, modification may provide better long-term outcome than settlement. For borrowers unable to sustain even modified payments, settlement typically produces better resolution.
Earnest cosigner release
Earnest offers cosigner release after qualifying payment period (typically 36 consecutive on-time principal-and-interest payments plus creditworthiness criteria). For current accounts with cosigners, pursuing cosigner release through this program may be preferable to settlement. For accounts already in default where cosigner release program is not available, settlement with explicit cosigner release provisions (addressed in settlement agreement) becomes essential for cosigner protection.
Earnest death discharge
Earnest offers death discharge on borrower death — contract-based provision that discharges the loan balance entirely upon qualifying borrower death. Estate administrators should promptly notify Earnest with proper documentation (death certificate, estate identification) to activate discharge processing. This provision provides family financial protection separate from settlement discussions.
Path 3: Defensive settlement with Crocker/McDaniel leverage
Defensive settle Navient loans approach using Fifth and Tenth Circuit §523(a)(8) precedents produces the deepest Navient settlement discounts — often 25-45% range. The Crocker v. Navient and McDaniel v. Navient precedents directly address Navient-held loans, creating specific bankruptcy discharge threat as settlement leverage.
Crocker v. Navient Fifth Circuit precedent
Crocker v. Navient Solutions LLC 941 F.3d 206 (5th Cir. 2019) established that private education loans may be dischargeable under 11 U.S.C. §523(a)(8) when they do not meet specific statutory requirements. The Fifth Circuit’s analysis specifically addressed Navient-held loans, creating Navient-specific precedent for bankruptcy discharge of qualifying private loans. This precedent applies to loans in Texas, Louisiana, and Mississippi (Fifth Circuit jurisdiction). For borrowers in these states or whose loan characteristics fit Crocker’s framework, bankruptcy discharge threat is credible and produces substantial settlement leverage.
McDaniel v. Navient Tenth Circuit precedent
McDaniel v. Navient Solutions LLC 973 F.3d 1083 (10th Cir. 2020) similarly addressed Navient private loans in the Tenth Circuit (Colorado, Kansas, New Mexico, Oklahoma, Utah, Wyoming). The Tenth Circuit held that certain Navient-held private loans do not meet §523(a)(8)(A)(ii) “educational benefit” criteria and are therefore dischargeable without undue hardship showing. For borrowers in these states or whose loan characteristics fit McDaniel’s framework, this precedent provides substantial bankruptcy-alternative settlement leverage.
Homaidan v. Sallie Mae application
For loans originally originated by pre-2014 Sallie Mae and now held by Navient (common pattern for older private loans), Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) framework also applies. The Second Circuit’s precedent on direct-to-consumer loans without school certification of cost of attendance supports bankruptcy discharge for qualifying loans — adding another defensive leverage layer for Navient settlement discussions.
Establishing credible bankruptcy alternative
Credible bankruptcy alternative requires: (1) bankruptcy counsel consultation documentation with specific §523(a)(8) analysis citing Crocker, McDaniel, or Homaidan as applicable; (2) means test qualification analysis under 11 U.S.C. §707(b)(2); (3) Circuit precedent analysis showing loan dischargeability for borrower’s jurisdiction and loan characteristics; (4) financial hardship documentation supporting bankruptcy viability. When presented in Navient settlement discussions, this framework communicates that borrower will pursue complete discharge through adversary proceeding if favorable settlement isn’t reached — producing substantial settlement discount beyond standard ranges.
Defensive settlement outcomes
Defensive Navient settlement outcomes typically produce: 30-45% range for strong Crocker/McDaniel/Homaidan cases with documented qualifying characteristics; 25-35% range combined with insolvency documentation; 20-30% range for borrowers actively pursuing Chapter 7 with Navient settling to avoid §523(a)(8) adversary proceeding. These outcomes significantly exceed standard Navient settlement discounts and reflect Navient’s incentive to settle rather than face complete discharge through Circuit-precedent-supported adversary proceeding.
Path 4: Chain of assignment for transferred Navient debt
If your Navient loan has been transferred to a third-party owner — NCSLT trust, debt buyer, or collection law firm — navient private student loan settlement dynamics change substantially. The current holder (not Navient) has settlement authority, and chain of assignment analysis becomes central to leverage.
Navient-originated loans transferred to NCSLT
Some Navient-serviced loans (particularly those originally originated by pre-2014 Sallie Mae and transferred through Navient) ultimately ended up in National Collegiate Student Loan Trusts (NCSLT 2003-1 through NCSLT 2007-4). If your account was originated in the pre-2014 Sallie Mae period and has been in default for years, current holder may be an NCSLT trust rather than Navient. Settlement with NCSLT uses Third Circuit March 19, 2024 “covered persons” precedent as leverage; typical outcomes 20-35% range.
Debt buyer transfers from Navient
Navient sometimes sells charged-off private student loan accounts to third-party debt buyers specializing in private student loan debt. If current holder is a debt buyer rather than Navient, chain of assignment leverage under Article III standing doctrine (Lujan/Spokeo/TransUnion) typically produces 25-40% range settlements — deeper than direct Navient settlements due to debt buyer’s lower cost basis and documentation vulnerabilities. Chain of assignment analysis requires tracing ownership from original lender (Sallie Mae or Navient) through intermediate transfers to current debt buyer.
Identifying current holder
Before approaching settlement, identify current holder: (1) check credit reports from Experian, Equifax, TransUnion for current furnisher identification; (2) request debt validation under FDCPA 15 U.S.C. §1692g if contacted by third party; (3) analyze any correspondence received for named plaintiff; (4) request chain of assignment documentation if any party claims current ownership. Settlement with wrong party doesn’t resolve the debt — ensure settlement execution with legally correct current holder.
Path 5: Pre-litigation settlement before charge-off
Pre-litigation navient settlement approach works best for accounts in late delinquency (90-180 days past due) but not yet charged off. Settlement in this window often produces 50-70% range outcomes while avoiding further credit damage from charge-off reporting.
The pre-charge-off opportunity
Before charge-off occurs at 180 days delinquent, Navient has internal pressure to resolve the account to avoid charge-off impact on quarterly financial reporting. Navient’s hardship accommodation team has authority to accept partial payment arrangements, modified loan terms, or outright settlement. Approaching Navient in days 120-170 of delinquency with documented hardship and lump sum funding offer often produces favorable settlement before full charge-off damage.
Documented hardship presentation
Pre-litigation settlement effectiveness depends on proper hardship documentation: (1) income statements showing current situation (pay stubs, 1099s, tax returns); (2) expense breakdown demonstrating cash flow constraints; (3) medical documentation if health-related hardship; (4) employment documentation if job loss or reduction; (5) family circumstance documentation if applicable; (6) alternative pathway documentation (bankruptcy consultation with Crocker/McDaniel analysis). Well-documented hardship presentation moves settlement discussions toward Navient’s hardship accommodation framework rather than standard collection posture.
Modification programs as alternative
Before pursuing settlement, consider Navient’s modification alternatives: hardship forbearance; modified payment plans; interest rate reduction programs. For borrowers who could sustain lower payments but not full balance settlement, modification may provide better long-term outcome. For borrowers unable to sustain even modified payments, settlement typically produces better resolution.
Path 6: Structured settlement with payment plan
When full lump sum funding isn’t available, structured settlement with payment plan becomes an alternative navient debt settlement path. Navient typically accepts payment plans in 3-6 month range for settlement amounts, though total settlement typically increases 10-20% versus straight lump sum.
Typical Navient structured settlement terms
Navient structured settlement typical terms: (1) 3-6 month payment plans with monthly payments totaling settlement amount; (2) initial down payment of 20-30% with balance paid over defined period; (3) automatic payment setup required; (4) default consequences specified (reversion to full balance, accelerated collection); (5) interest-free or minimal interest on payment plan amount. Longer payment plans occasionally available but typically require escalation and increase total settlement amount further.
Default risk considerations
Structured settlement carries significant default risk: if borrower misses a payment during the plan period, Navient typically reverses the settlement and reverts to full balance (potentially with accelerated collection). Borrowers should only commit to structured settlement with high confidence in payment capacity throughout the term. Lump sum settlement, when possible, eliminates this risk entirely while typically producing better total cost.
Related resources — complete Navient resolution ecosystem
Private Student Loan Settlement 2026: Complete Guide (PILAR)
The 7-path master framework covering all private student loan settlement mechanisms including Navient and other major lenders.
Private Loan Forgiveness Navient Guide 2026
6 proven forgiveness paths for Navient borrowers including Crocker/McDaniel precedent application.
Sallie Mae Settlement 2026: How It Works
Complete Sallie Mae settlement framework (relevant for pre-2014 Sallie Mae-originated loans now held by Navient).
IRC §108 tax planning for Navient settlement
The forgiven portion of Navient settlement is reported on IRS Form 1099-C and generally taxable as ordinary income. However, Internal Revenue Code §108 provides important exclusions that typically eliminate most or all of this tax liability for borrowers in settlement situations.
Insolvency exclusion application
IRC §108(a)(1)(B) excludes cancelled debt from taxable income to the extent the borrower was insolvent (total liabilities exceeded total assets) immediately before the debt cancellation. For many borrowers in Navient default situations, insolvency is readily documented. The exclusion amount equals the lesser of: cancelled debt amount, or amount by which liabilities exceeded assets at time of cancellation. Documentation requires Form 982 filing with tax return.
Bankruptcy exclusion for coordinated resolution
IRC §108(a)(1)(A) excludes debt cancelled in Chapter 7 or Chapter 13 bankruptcy entirely from taxable income — regardless of insolvency analysis. For borrowers whose Navient resolution is part of broader bankruptcy strategy (combining Crocker/McDaniel §523(a)(8) discharge with other debt resolution), this exclusion provides complete tax protection on cancelled debt income.
Pre-settlement CPA consultation
CPA consultation BEFORE finalizing Navient settlement provides: insolvency calculation worksheet establishing exclusion basis; timing analysis for year-end versus year-start settlements; coordination with other debt cancellations in same year; Form 982 preparation guidance; state tax implications analysis. CPA fees typically $300-800 are modest investment protecting against potentially substantial unexpected tax liability on the forgiven portion of Navient settlement.
Decision framework for Navient settlement
By current loan status
Which navient student loan settlement path applies depends on current loan status: Current but struggling — pursue Navient’s hardship forbearance or modification programs first; Current with Earnest-branded loan — pursue Earnest’s skip-a-payment or hardship accommodation; Recently delinquent (90-180 days) — pre-litigation settlement (Path 5) in 50-70% range OR hardship programs; Charged-off (180+ days) with Navient — direct settlement (Path 1) in 40-55% range with Crocker/McDaniel leverage integration; Charged-off with Earnest — Earnest settlement (Path 2) in 45-60% range; Loans with Crocker/McDaniel/Homaidan characteristics — defensive settlement (Path 3) in 25-45% range; Transferred to NCSLT or debt buyer — chain of assignment settlement (Path 4) in 20-40% range; Lawsuit filed by Navient or assignee — defensive position settlement combining Paths 3 and 4; Limited lump sum funding — structured settlement (Path 6) as backup.
By borrower jurisdiction
Jurisdiction affects defensive leverage availability: Fifth Circuit (TX, LA, MS) — Crocker v. Navient precedent directly binding, strongest leverage; Tenth Circuit (CO, KS, NM, OK, UT, WY) — McDaniel v. Navient precedent directly binding, strongest leverage; Second Circuit (CT, NY, VT) — Homaidan v. Sallie Mae precedent applies to Sallie Mae-originated loans transferred to Navient; Third Circuit (DE, NJ, PA) — NCSLT “covered persons” precedent from March 19, 2024 for transferred loans; Other circuits — Crocker, McDaniel, and Homaidan are persuasive but not binding; still provide meaningful settlement leverage.
Multi-path coordination
Effective Navient settlement typically combines multiple paths: Path 1 (direct settlement) + Path 3 (Crocker/McDaniel leverage) + Path 4 (chain of assignment analysis if NCSLT-held) + IRC §108 tax planning. Multi-path coordination produces materially better outcomes than any single path alone. Professional representation ensures proper coordination across paths.
Common Navient settlement myths
Myth 1
“Navient’s 2022 $1.85B settlement already forgave my loans”
Reality: The January 2022 state attorneys general settlement with Navient included $1.7 billion in private student loan debt cancellation for approximately 66,000 borrowers meeting specific criteria (primarily subprime loans at certain for-profit schools). Only borrowers in the specific cancellation pool received direct forgiveness. The vast majority of Navient borrowers did NOT receive debt cancellation through this settlement. If your Navient loans remain active, you need to pursue settlement through the 6 paths in this guide rather than assume the 2022 settlement resolved your debt. Check with Navient directly to confirm whether your account was included in the 2022 cancellation pool.
Myth 2
“Navient only services federal loans — settlement doesn’t apply”
Reality: This myth is outdated. Navient completed its federal loan portfolio exit in December 2021 with transfer to Aidvantage (Maximus Federal Services). Since then, Navient has focused exclusively on PRIVATE student loans. If your account is still at Navient in 2026, it is a private loan — and private loans ARE subject to settlement through the 6 paths in this guide. Navient’s post-federal-exit focus means private loan settlement discussions receive more organizational attention and resources than during the dual-focus period. Settlement framework for private Navient loans is active and well-developed.
Myth 3
“Crocker/McDaniel precedents only apply to specific states”
Reality: While Crocker v. Navient 941 F.3d 206 (5th Cir. 2019) is binding precedent in Fifth Circuit states (TX, LA, MS) and McDaniel v. Navient 973 F.3d 1083 (10th Cir. 2020) is binding in Tenth Circuit states (CO, KS, NM, OK, UT, WY), these precedents are PERSUASIVE in other jurisdictions and routinely cited by bankruptcy courts nationwide. Combined with Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) binding in Second Circuit (CT, NY, VT) and persuasive elsewhere, the §523(a)(8) discharge framework for Navient private loans has substantial national application. Settlement leverage using these precedents works in all jurisdictions, though with varying degrees of binding authority.
Myth 4
“Earnest loans can’t be settled because Earnest is a refinance lender”
Reality: Earnest Operations LLC (Navient subsidiary since 2017) settles charged-off private student loan accounts just like any other private lender. Earnest’s refinance-focused origination model doesn’t change settlement framework once loans are in default — the same 45-60% range typically applies for charged-off Earnest accounts. Earnest’s more accommodating approach to alternative income sources (gig workers, self-employed, variable income) actually produces somewhat more favorable settlement framework than standard private lenders for borrowers with non-W-2 income. Don’t assume Earnest can’t be settled — the opposite is often true.
Frequently asked questions
1. What is a Navient student loan settlement?
A Navient student loan settlement is a negotiated written agreement with Navient Corporation (NYSE:NAVI) or subsidiary Earnest Operations LLC in which the borrower pays a reduced lump sum in full satisfaction of the private student loan debt. Typical outcomes: 40-55% for charged-off Navient accounts; 45-60% for charged-off Earnest accounts; 25-45% with Crocker v. Navient 941 F.3d 206 (5th Cir. 2019), McDaniel v. Navient 973 F.3d 1083 (10th Cir. 2020), or Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) §523(a)(8) bankruptcy alternative leverage. The forgiven portion is reported on IRS Form 1099-C but typically excluded from taxable income under IRC §108(a)(1)(B) insolvency exclusion. Settlement agreement must include full satisfaction release language, cosigner release provisions, and tradeline update instructions.
2. How much will Navient settle for?
Navient settlement percentages depend on account status and leverage: pre-charge-off accounts typically 50-70% of balance; recently charged-off (6-12 months) 45-55%; moderately aged (12-24 months) 40-50%; older charged-off (24+ months) 35-50%; Earnest-branded loans 45-60%; with Crocker/McDaniel/Homaidan leverage 30-45%; combined with insolvency documentation 25-35%; borrowers actively pursuing Chapter 7 may see 20-30% range as Navient settles to avoid §523(a)(8) adversary proceeding. Specific outcome depends on account documentation, borrower circumstances, Circuit jurisdiction, defensive leverage available, lump sum funding capability, and negotiation preparation.
3. How do I settle with Navient?
How to settle Navient: (1) confirm current loan status (current, delinquent, charged-off); (2) identify current holder (Navient internal, Earnest, NCSLT trust if transferred, or debt buyer); (3) analyze loan characteristics for Crocker/McDaniel/Homaidan §523(a)(8) qualification based on borrower’s Circuit; (4) prepare documented financial hardship presentation; (5) secure lump sum funding; (6) contact appropriate Navient department (hardship team pre-charge-off, recovery department post-charge-off, Earnest for Earnest-branded loans); (7) present specific written settlement offer with supporting documentation; (8) negotiate counter-offers; (9) obtain written settlement agreement with all required elements including cosigner release; (10) execute payment and verify tradeline updates. Legal representation typically produces materially better outcomes than DIY approach.
4. Does Crocker v. Navient apply to my loan?
Crocker v. Navient Solutions LLC 941 F.3d 206 (5th Cir. 2019) is binding precedent in Fifth Circuit states (Texas, Louisiana, Mississippi) for Navient private loans. The precedent is PERSUASIVE in other jurisdictions and routinely cited by bankruptcy courts nationwide. Crocker’s framework applies to private education loans that don’t meet all §523(a)(8) statutory requirements — making them potentially dischargeable without undue hardship. Loan characteristics that support Crocker application: direct-to-consumer loans without school certification; loans exceeding cost of attendance; loans for non-title IV eligible programs; loans to less-than-half-time students. Detailed loan analysis determines whether specific loan qualifies. For borrowers outside Fifth Circuit, combined citation of Crocker (5th Cir.), McDaniel (10th Cir.), and Homaidan (2d Cir.) creates substantial persuasive authority.
5. What’s the difference between settling with Navient vs Earnest?
Navient Corporation (NYSE:NAVI) and Earnest Operations LLC are separate operating entities despite common corporate parent (Navient acquired Earnest in 2017 for $155M). Differences: Navient handles traditional private student loan portfolios with standard settlement framework typically 40-55% for charged-off accounts; Earnest handles its own branded loans with more accommodating approach for alternative income sources, typical outcomes 45-60% for charged-off accounts. Earnest offers skip-a-payment feature (one payment per 12 months for current accounts) that Navient doesn’t offer. Both ultimately report to Navient corporate parent but operate with distinct brand identities and settlement authorities. Determining which entity holds your specific loan requires checking account documentation.
6. Will Navient settlement affect my credit score?
Settlement credit impact depends on current account status. For accounts already charged-off (where most Navient settlements occur), the credit damage has already been incurred — settlement typically improves the account status from “charged-off” to “settled” or “paid for less than full balance.” Credit reporting under FCRA is limited to 7 years from original delinquency regardless of settlement timing. Most borrowers see credit score recovery within 12-24 months of settlement completion. Credit score concerns should not prevent exploring Navient settlement when the alternative is continued default, potential Navient lawsuit, and ongoing credit damage. For pre-charge-off accounts, settlement before charge-off (Path 5) may minimize additional credit damage.
7. How long does Navient settlement take?
Typical Navient settlement timeline: initial contact to recovery department 1-2 weeks; first counter-offer exchange 2-3 weeks; final agreement negotiation 2-4 weeks; written agreement review and execution 1-2 weeks; payment processing and release documentation 1-2 weeks; credit tradeline updates 30-60 days post-payment. Total timeline typically 2-4 months from initial engagement to full completion. Faster timelines (6-8 weeks) occur with proper preparation: defensive leverage ready (Crocker/McDaniel/Homaidan analysis complete), funding confirmed, reasonable opening offer, professional representation coordinating. Complex situations (NCSLT trusts, active litigation, cross-Circuit defensive leverage) may extend to 4-9 months.
Need a Navient Student Loan Settlement?
Free specialist review of all 6 settlement paths for your Navient loans.
Direct settlement with Navient recovery department, Earnest Operations LLC settlement with gig-economy accommodation framework, defensive settlement using Crocker v. Navient (5th Cir. 2019) and McDaniel v. Navient (10th Cir. 2020) §523(a)(8) bankruptcy alternative leverage, Homaidan v. Sallie Mae (2d Cir. 2021) framework for legacy Sallie Mae-originated loans transferred to Navient, chain of assignment settlement for NCSLT-transferred or debt-buyer-transferred Navient debt, pre-litigation and structured settlement options, IRC §108 tax planning. Free eligibility review with attorney-backed partner provider — no upfront fees.
Get a free eligibility review →
5-minute review · No obligation · Zero upfront fees · Since 2015 · 48 states served
About the author
Henry Silva — Private Student Loan Debt Specialist
10+ years negotiating Navient student loan settlement outcomes with Navient Corporation (NYSE:NAVI) and subsidiary Earnest Operations LLC (acquired 2017 for $155M) across all account statuses and situations. Deep expertise in Navient’s corporate transformation (2014 Sallie Mae split, 2017 Earnest acquisition, December 2021 Aidvantage transfer completing federal loan exit, January 2022 $1.85B state attorneys general settlement) and the resulting post-federal-exit focus on private student loans. Defensive leverage integration: bankruptcy discharge analysis under 11 U.S.C. §523(a)(8) with Crocker v. Navient Solutions LLC 941 F.3d 206 (5th Cir. 2019) binding Fifth Circuit (TX, LA, MS) precedent, McDaniel v. Navient Solutions LLC 973 F.3d 1083 (10th Cir. 2020) binding Tenth Circuit (CO, KS, NM, OK, UT, WY) precedent, Homaidan v. Sallie Mae Inc. 992 F.3d 100 (2d Cir. 2021) direct-to-consumer precedent for legacy Sallie Mae-originated loans transferred to Navient, Brunner v. New York State Higher Education Services Corp. 831 F.2d 395 (2d Cir. 1987) framework for qualified loans, In re Rosenberg 594 B.R. 22 (Bankr. S.D.N.Y. 2020) updated application, DOJ November 2022 guidance on undue hardship. Article III standing doctrine (Lujan v. Defenders of Wildlife 504 U.S. 555 (1992), Spokeo, Inc. v. Robins 578 U.S. 330 (2016), TransUnion LLC v. Ramirez 594 U.S. 413 (2021)) for chain of assignment challenges on transferred Navient debt. Third Circuit March 19, 2024 “covered persons” precedent for NCSLT-held pre-2014 Sallie Mae-originated loans. Earnest-specific accommodation framework for alternative income sources (gig workers, self-employed, variable income). Statute of limitations analysis across all 50 states; FDCPA 15 U.S.C. §1692g validation and §1692e counterclaim coordination; IRC §108(a)(1)(A) bankruptcy and §108(a)(1)(B) insolvency tax exclusion with Form 982 preparation; cosigner release strategy; coordinated multi-path settlement execution. Henry works with Private Student Relief’s attorney-backed partner provider network to review individual Navient scenarios across all 6 settlement mechanisms.
Legal Disclaimer and Sources
This article is provided for informational purposes only and does not constitute legal, tax, or financial advice. Private Student Relief is a consulting and matching organization operated by Joco (555 Anton Blvd, Suite 368, Costa Mesa, CA 92626) — not a law firm, debt settlement company, debt consolidation company, or loan provider. Debt validation services are performed by an attorney-backed partner provider (Panamerican Consulting LLC, Las Vegas, NV) under independent business credentials. Ratings, BBB accreditation, and AADR (American Association for Debt Resolution) membership referenced on the PSR website belong to the partner provider. Navient settlement outcomes depend on loan characteristics, current account status, Circuit jurisdiction, defensive leverage opportunities, lump sum funding capability, and other factors. Individual results vary. Since 2015. 48 states served. Not available in South Carolina or Mississippi.
Navient Corporation (NYSE:NAVI) corporate history: 2014 split from historical Sallie Mae organization creating Navient as separate publicly traded company focused on servicing; 2017 acquisition of Earnest Operations LLC for $155 million; December 2021 transfer of federal loan portfolio to Aidvantage (operated by Maximus Federal Services) completing exit from federal loan servicing; January 2022 settlement with 39 state attorneys general for $1.85 billion including $1.7 billion in private student loan debt cancellation for approximately 66,000 borrowers and $95 million in restitution to approximately 350,000 federal loan borrowers plus procedural reforms. Since late 2021, Navient has focused exclusively on private student loans.
Earnest Operations LLC: technology-focused private student loan refinance and origination lender; acquired by Navient 2017 for $155 million; operates as Navient subsidiary with distinct brand identity; accommodation framework for alternative income sources (gig economy, self-employed, variable income); skip-a-payment feature for current accounts; cosigner release after qualifying payment period; death discharge on borrower death.
Bankruptcy Code references: 11 U.S.C. §523(a)(8) (student loan discharge exceptions with §523(a)(8)(A)(i) governmental unit, §523(a)(8)(A)(ii) educational benefit, §523(a)(8)(B) qualified education loan categories); 11 U.S.C. §362 (automatic stay); 11 U.S.C. §707(b)(2) (means test); 11 U.S.C. §1328 (Chapter 13 discharge). Key Navient-specific bankruptcy precedent: Crocker v. Navient Solutions LLC 941 F.3d 206 (5th Cir. 2019) — binding in Fifth Circuit (TX, LA, MS), persuasive elsewhere; McDaniel v. Navient Solutions LLC 973 F.3d 1083 (10th Cir. 2020) — binding in Tenth Circuit (CO, KS, NM, OK, UT, WY), persuasive elsewhere. Related precedent for legacy Sallie Mae-originated loans transferred to Navient: Homaidan v. Sallie Mae Inc. 992 F.3d 100 (2d Cir. 2021) — binding in Second Circuit (CT, NY, VT), persuasive elsewhere. Additional bankruptcy precedent: Brunner v. New York State Higher Education Services Corp. 831 F.2d 395 (2d Cir. 1987); In re Rosenberg 594 B.R. 22 (Bankr. S.D.N.Y. 2020). Article III standing precedent: Lujan v. Defenders of Wildlife 504 U.S. 555 (1992); Spokeo, Inc. v. Robins 578 U.S. 330 (2016); TransUnion LLC v. Ramirez 594 U.S. 413 (2021). Federal Rules of Civil Procedure: FRCP 60(b)(4) (void judgment). Internal Revenue Code: IRC §221(d)(1) (qualified education loan definition); IRC §108(a)(1)(A) (bankruptcy exclusion); IRC §108(a)(1)(B) (insolvency exclusion); Form 982 (reduction of tax attributes due to discharge of indebtedness). FDCPA: 15 U.S.C. §1692g (debt validation); 15 U.S.C. §1692e (deceptive practices); 15 U.S.C. §1692f (unfair practices). Federal tax reporting: IRS Form 1099-C (cancellation of debt).
NCSLT precedent for pre-2014 Sallie Mae-originated loans transferred to NCSLT trusts (National Collegiate Student Loan Trusts 2003-1 through 2007-4) that passed through Navient servicing: Third Circuit decision March 19, 2024 addressing NCSLT “covered persons” status under Consumer Financial Protection Act; SCOTUS cert denial December 2024 leaving Third Circuit precedent in place.
Statute of limitations for written contract debt (private student loans including Navient-held and Earnest-held) by state: Texas 4 years under Tex. Civ. Prac. & Rem. Code §16.004(a)(3); New York 3 years under CPLR §214(2) per Consumer Credit Fairness Act (CCFA) effective April 7, 2022; Pennsylvania 4 years under 42 Pa.C.S. §5525; Ohio 6 years under Ohio R.C. §2305.06 (reduced 2021); Illinois 10 years under 735 ILCS 5/13-206; Georgia 6 years under O.C.G.A. §9-3-24; California 4 years under CCP §337; Florida 5 years under Fla. Stat. §95.11(2)(b); Delaware 3 years under 10 Del. C. §8106.
Navient settlement strategy requires case-by-case analysis coordinating loan characteristics, Navient vs Earnest holder identification, current account status, Circuit jurisdiction for Crocker/McDaniel/Homaidan precedent application, chain of assignment history (whether loan remains with Navient/Earnest or has been transferred to NCSLT or debt buyer), borrower jurisdiction, defensive leverage opportunities, lump sum funding capability, IRC §108 tax exclusion qualification, cosigner coordination, and coordinated multi-path approach. This article provides general framework information; specific settlement negotiations, Crocker/McDaniel/Homaidan bankruptcy-alternative analysis, chain of assignment challenges, cosigner release strategy, FDCPA counterclaim preservation, and coordinated multi-path approaches must be evaluated for each borrower’s individual Navient or Earnest situation by counsel or consulting resources familiar with the complete Navient student loan settlement framework. Last reviewed: October 2026.