Informational content only. Not legal, tax, or financial advice. Private Student Relief is a consulting organization, not a law firm. Debt validation services are executed by an attorney-backed partner provider. Private student loan forgiveness pathway availability depends on loan characteristics, lender terms, borrower circumstances, and jurisdiction. Last reviewed: October 2026.
Written by Henry Silva
Private Student Loan Debt Specialist · 10+ years explaining why borrowers asking will private student loans ever be forgiven through federal programs are usually asking the wrong question — and delivering the real answer through settlement negotiation with major private lenders (Sallie Mae Bank NYSE:SLM, Navient/Earnest Operations LLC, Discover/Firstmark Services, SoFi Bank NA, Citizens Bank NA, Ascent), bankruptcy discharge under 11 U.S.C. §523(a)(8) with Homaidan v. Sallie Mae Second Circuit precedent, statute of limitations analysis across all 50 states, chain of assignment challenges under Article III standing (Lujan/Spokeo/TransUnion), and coordinated multi-path forgiveness strategy. Last reviewed: October 2026.
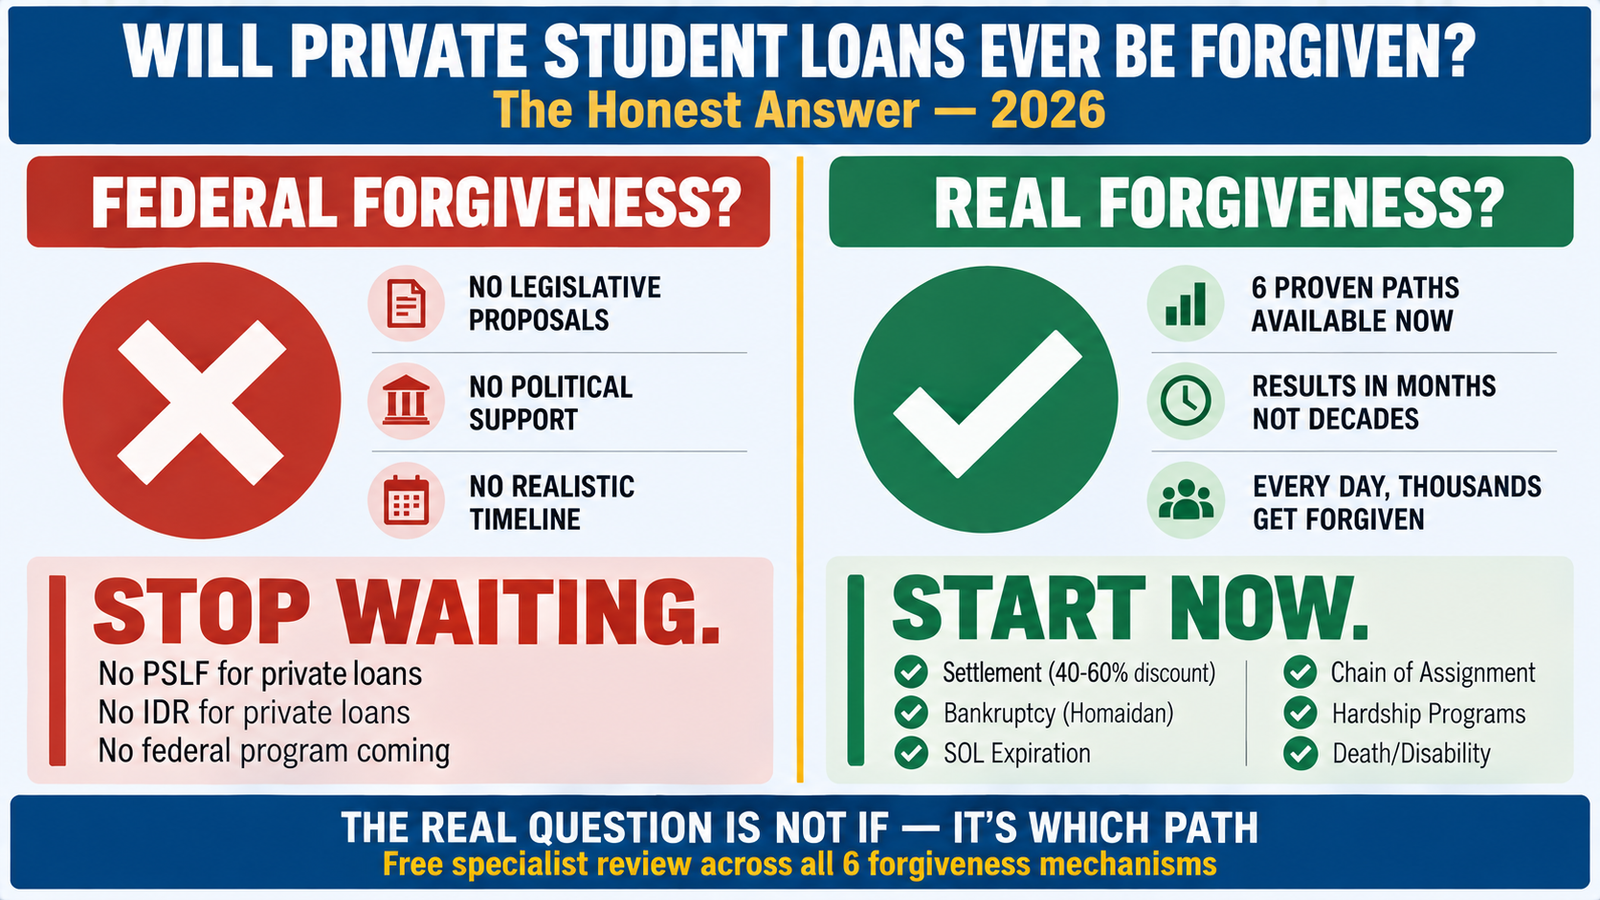
The question will private student loans ever be forgiven is one of the most searched queries in student debt — and the honest answer requires distinguishing between two very different things. If you’re asking whether Congress will ever pass a federal forgiveness program covering private student loans (like PSLF or IDR forgiveness extended to private debt), the answer is: no credible legislative proposal exists, and extending federal forgiveness to private loans would require federal purchase or payment to private lenders with no legislative support. But if you’re asking whether real forgiveness mechanisms exist for private student loans RIGHT NOW in 2026, the answer is: absolutely yes — through 6 proven legal paths that produce real forgiveness outcomes every day. This complete guide explains both answers honestly and shows you the 6 paths that actually work.
Quick Answer
Will private student loans ever be forgiven through a federal program? No — there are no credible legislative proposals to extend federal forgiveness programs (PSLF under 20 U.S.C. §1087e(m), IDR forgiveness, Teacher Loan Forgiveness) to private student loans. Federal forgiveness is specifically tied to federal loan statutes under the Higher Education Act (20 U.S.C. §1001 et seq.). Extending federal forgiveness to private loans would require federal purchase or payment to private lenders with no legislative support. However, private student loans ARE forgiven every day through 6 proven legal mechanisms that exist in 2026: (1) settlement negotiation with current holder — typically 40-60% discount for charged-off accounts; (2) bankruptcy discharge under 11 U.S.C. §523(a)(8) with Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) precedent making non-qualified private loans dischargeable without undue hardship; (3) statute of limitations expiration under state SOL (3-15 years by state); (4) chain of assignment defense on Article III standing grounds (Lujan/Spokeo/TransUnion) particularly effective against NCSLT and debt-buyer-held debt; (5) lender hardship programs reducing payment burden; (6) death and disability discharge from most private lenders. Waiting for federal forgiveness that will not come costs borrowers years of unnecessary interest, late fees, and credit damage. The 6 real paths are available now and produce measurable results.
Read the complete honest answer below.
In this complete 2026 guide:
The honest answer about federal forgiveness for private loans
Why federal programs don’t apply and won’t be extended to private debt
The cost of waiting for forgiveness that won’t come
What delay actually costs in interest, fees, and lost opportunities
Real forgiveness path 1: Settlement
How settlement produces real forgiveness outcomes now
Real forgiveness path 2: Bankruptcy discharge
Homaidan precedent, Brunner for qualified loans
Real forgiveness paths 3-4: SOL and chain of assignment
Time-based and standing-based forgiveness mechanisms
Real forgiveness paths 5-6: Lender programs and discharge
Hardship programs and death/disability discharge
The honest answer about federal forgiveness for private loans
The question will private student loans ever be forgiven through a federal government program deserves an honest answer rather than vague hope. The direct answer: no, there are no credible legislative proposals currently in Congress or being developed by federal agencies that would extend federal forgiveness programs to cover private student loans. Understanding why this is unlikely to change helps borrowers make better decisions about their actual options.
Why federal programs can’t simply be extended
Federal forgiveness programs like Public Service Loan Forgiveness (PSLF) under 20 U.S.C. §1087e(m), Income-Driven Repayment (IDR) forgiveness, and Teacher Loan Forgiveness are specifically tied to federal loan statutes under the Higher Education Act (20 U.S.C. §1001 et seq.). These programs work because the federal government owns or guarantees the loans — forgiveness means the government is simply writing off its own debt. Private loans are owned by private corporations (Sallie Mae Bank NYSE:SLM, Navient Corporation NYSE:NAVI, SoFi Bank NA, Citizens Bank NA NYSE:CFG, etc.). Federal “forgiveness” of these loans would require federal purchase of private debt or federal payment to private lenders using taxpayer funds — a fundamentally different policy that has no legislative support.
Historical attempts and current status
Several proposals have been introduced over the past decade addressing private student loan debt, but none have gained meaningful traction: (1) proposals to restore full bankruptcy discharge for private student loans (removing §523(a)(8) protection) have been introduced repeatedly but have not advanced; (2) proposals for federal refinancing of private loans at lower interest rates have been proposed but not enacted; (3) broader student debt cancellation proposals have focused almost exclusively on federal loans. The political and fiscal obstacles to federal payment of private debt remain substantial — the question will private student loans ever be forgiven federally in a meaningful way should be answered honestly: unlikely in any foreseeable timeframe.
What has actually changed in recent years
While federal forgiveness programs have not expanded to cover private loans, significant developments HAVE improved private student loan forgiveness through other mechanisms: Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) establishing broad bankruptcy dischargeability for non-qualified private loans; Crocker v. Navient 941 F.3d 206 (5th Cir. 2019) and McDaniel v. Navient 973 F.3d 1083 (10th Cir. 2020) extending similar framework; Third Circuit’s March 19, 2024 decision on NCSLT “covered persons” analysis; DOJ November 2022 guidance moderating Brunner undue hardship test. These developments provide real private student loans forgiveness mechanisms that have expanded substantially even as federal legislative action has not materialized.
The real cost of waiting for forgiveness that won’t come
The practical consequence of asking will private student loans ever be forgiven and then waiting indefinitely for federal action is substantial — delay costs borrowers real money, credit damage, and lost opportunities every month. Understanding what waiting actually costs helps clarify why the 6 real forgiveness paths available now typically produce better outcomes than passive waiting.
Interest accumulation during delay
Private student loan interest rates typically range from 6% to 14% depending on loan type, cosigner status, and origination terms. For a $80,000 private student loan balance at 10% average interest, each year of waiting adds approximately $8,000 in accrued interest. Over 5 years of waiting for federal action that may never come, this adds $40,000+ to the total debt burden. Meanwhile, real forgiveness mechanisms available in 2026 (settlement typically producing 40-60% discount on charged-off accounts) would have eliminated most of the original debt long before this interest accumulation.
Credit damage during delay
Delinquent private student loans continue damaging credit scores throughout the delay period. Credit reporting under the Fair Credit Reporting Act (FCRA) continues for 7 years from original delinquency date. Each additional month of delinquency affects housing applications, auto loan rates, employment background checks, and other financial decisions. Settling or discharging the debt through private student loan forgiveness mechanisms available now starts the credit recovery process immediately — waiting for federal action that may never come extends the credit damage period indefinitely.
Litigation risk during delay
Private student loan lenders file lawsuits against delinquent borrowers regularly. Each month of delay increases the probability of lawsuit filing before statute of limitations expiration. Default judgments (if the borrower doesn’t appear) result in wage garnishment, bank account levies, and property liens that can take years to address and often require more complex legal intervention than proactive engagement would have required. Waiting for federal forgiveness that may never come significantly increases these litigation risks.
Opportunity cost of delayed debt resolution
Beyond direct financial costs, delayed debt resolution carries substantial opportunity costs: postponed home purchases requiring clean credit; delayed career changes requiring background check clearance; postponed family planning due to financial uncertainty; delayed retirement contributions during years of debt focus; impaired business opportunities requiring credit lines or financing. The question will private student loans ever be forgiven federally has become — for many borrowers — the question that prevented them from pursuing real forgiveness options that would have resolved the debt years ago.
Real forgiveness path 1: Settlement — producing forgiveness now
Settlement is the most frequently used mechanism for can private student loans be forgiven questions — and the answer is yes, every day. In settlement, the borrower and current holder agree that payment of a specific reduced amount satisfies the entire debt. The difference between the balance and settlement payment is forgiven — producing real, measurable private student debt forgiveness immediately upon completion.
How settlement produces real forgiveness
Settlement works through voluntary agreement: borrower pays specified lump sum (less than full balance); current holder accepts this payment in full satisfaction of entire debt; remaining balance above settlement payment is extinguished through written agreement. For a borrower with $80,000 charged-off private student loan who settles for $32,000, this is immediate forgiveness of $48,000. The forgiven amount is reported on IRS Form 1099-C and may be excluded from income under IRC §108 (insolvency or bankruptcy exclusions). This is real forgiveness happening now — not waiting for federal programs that may never come.
Settlement outcomes by lender
Settlement outcomes vary by current holder and loan status: Sallie Mae Bank NYSE:SLM — pre-charge-off typically 50-70% of balance, post-charge-off 40-55% of balance; Navient/Earnest Operations LLC — similar framework to Sallie Mae; Discover/Firstmark Services (post-July 2024 Carlyle+KKR sale) — continues Discover framework; SoFi Bank NA (NMLS #696891) — less flexibility typically, often 60-75% of balance; Citizens Bank NA NYSE:CFG — standard private lender ranges; Ascent Student Loans — moderate flexibility, varies by loan type; NCSLT-held debt — often substantial discounts when chain of assignment weaknesses documented. Approaching settlement from defensive leverage position produces materially better outcomes.
IRC §108 tax planning for settlement forgiveness
The forgiven portion is reported on Form 1099-C and generally taxable as ordinary income — but IRC §108 exclusions typically eliminate most or all of this liability. Insolvency exclusion (IRC §108(a)(1)(B)) excludes cancelled debt to extent borrower was insolvent (liabilities exceeded assets) immediately before cancellation — many borrowers in default qualify. Bankruptcy exclusion (IRC §108(a)(1)(A)) excludes debt cancelled in Chapter 7 or Chapter 13 bankruptcy entirely. CPA analysis before finalizing settlement produces optimal tax outcome.
Real forgiveness path 2: Bankruptcy discharge — complete forgiveness
Bankruptcy discharge produces the most complete answer to are private student loans forgivable — yes, through court order eliminating the entire debt. The widespread myth that “private student loans can never be discharged in bankruptcy” is factually incorrect following key Circuit Court precedents. Understanding when and how bankruptcy discharge produces complete forgiveness is essential for borrowers asking whether their private debt can ever be forgiven.
The §523(a)(8) framework
11 U.S.C. §523(a)(8) makes certain educational loans non-dischargeable in bankruptcy unless “undue hardship” is shown. The statute has three categories: §523(a)(8)(A)(i) — loans made, insured, or guaranteed by a governmental unit (federal loans); §523(a)(8)(A)(ii) — “obligation to repay funds received as educational benefit, scholarship, or stipend”; §523(a)(8)(B) — “qualified education loan” as defined in IRC §221(d)(1). Private loans that do NOT fall into any of these three categories are dischargeable in bankruptcy WITHOUT any undue hardship showing — just like ordinary credit card debt.
The Homaidan Second Circuit precedent
Homaidan v. Sallie Mae Inc. 992 F.3d 100 (2d Cir. 2021) established that “educational benefit” under §523(a)(8)(A)(ii) is narrow. The Second Circuit held that Sallie Mae’s direct-to-consumer loans (made directly to students without school certification of cost of attendance) do NOT qualify as “educational benefit” and are therefore dischargeable WITHOUT undue hardship. Similar precedents in Fifth Circuit (Crocker v. Navient 941 F.3d 206, 5th Cir. 2019) and Tenth Circuit (McDaniel v. Navient 973 F.3d 1083, 10th Cir. 2020). This precedent provides direct answer to will private student loans ever be forgiven for borrowers eligible for bankruptcy — yes, right now, through court order.
Which private loans discharge under Homaidan
Private loans potentially dischargeable without undue hardship: (1) direct-to-consumer loans without school certification of cost of attendance; (2) loans exceeding “cost of attendance” limit for enrollment period; (3) loans for non-title IV eligible programs (vocational schools, bar prep, non-degree programs); (4) loans to students not enrolled at least half-time; (5) loans failing other IRC §221(d)(1) requirements. Many Sallie Mae, Navient/Earnest, Discover, SoFi, Citizens, and Ascent loans meet at least one of these criteria upon detailed analysis.
Qualified loans and Brunner test
Private loans qualifying under §523(a)(8) require undue hardship showing. Most circuits apply Brunner test from Brunner v. New York State Higher Education Services Corp. 831 F.2d 395 (2d Cir. 1987): (1) debtor cannot maintain minimal standard of living while repaying; (2) additional circumstances indicate situation will persist for significant portion of repayment period; (3) debtor has made good faith efforts to repay. Recent case law (In re Rosenberg 594 B.R. 22, Bankr. S.D.N.Y. 2020) and DOJ November 2022 guidance have moderated application, making discharge more accessible than historical practice suggested.
Real forgiveness path 3: Statute of limitations expiration
Statute of limitations expiration creates time-based private loan forgiveness for older private student loan debt. When state SOL expires, the current holder loses the legal ability to file a lawsuit to collect the debt. While the debt still legally exists, it becomes effectively uncollectible through litigation — producing practical forgiveness of enforcement for aged defaults.
State SOL periods for private student loan debt
SOL periods for written contract debt vary by state: Texas 4 years under Tex. Civ. Prac. & Rem. Code §16.004(a)(3); New York 3 years under CPLR §214(2) per Consumer Credit Fairness Act effective April 7, 2022; Pennsylvania 4 years under 42 Pa.C.S. §5525; Ohio 6 years under R.C. §2305.06 (reduced 2021); Illinois 10 years under 735 ILCS 5/13-206; Georgia 6 years under O.C.G.A. §9-3-24; California 4 years under CCP §337; Florida 5 years under Fla. Stat. §95.11(2)(b); Delaware 3 years under 10 Del. C. §8106. Accrual typically starts on date of first default or last payment, depending on state law.
Revival concerns for older debt
Borrowers with older debt must avoid actions that could restart the SOL clock: any payment (even small “goodwill” payments) may restart; written acknowledgment (hardship applications, settlement offers, promise to pay) may create restart; new agreement resets timing. Collectors sometimes specifically solicit small payments or written communications designed to revive time-barred debt. Consulting counsel before communicating with creditors on old private student loan debt prevents inadvertent revival.
Defensive application when SOL expires
When SOL has expired: (1) debt legally exists but cannot be enforced through litigation; (2) collection calls can be disputed under FDCPA 15 U.S.C. §1692g if third-party collector involved; (3) lawsuit filed on time-barred debt typically dismissed on motion and may support FDCPA counterclaim under 15 U.S.C. §1692e; (4) credit reporting continues under 7-year FCRA reporting period; (5) settlement of time-barred debt should proceed carefully to avoid revival. SOL expiration provides effective private student loans forgiveness of enforcement by making the debt uncollectible.
Real forgiveness path 4: Chain of assignment defense
Chain of assignment defense produces one of the most powerful forms of private student debt forgiveness — case dismissal on standing grounds that effectively eliminates the debt when the current plaintiff cannot demonstrate right to enforce. Under Article III of the U.S. Constitution, plaintiffs must have standing to bring a lawsuit, requiring proof of complete chain of ownership from original lender.
Article III standing framework
Article III standing requires: (1) concrete and particularized injury; (2) causally connected to defendant’s conduct; (3) redressable by court decision. Framework established in Lujan v. Defenders of Wildlife 504 U.S. 555 (1992), refined in Spokeo, Inc. v. Robins 578 U.S. 330 (2016), and further developed in TransUnion LLC v. Ramirez 594 U.S. 413 (2021). For a plaintiff to sue on private student loan debt, they must establish complete chain of ownership from original lender to themselves. Standing is jurisdictional and can be raised at any stage of litigation, including post-judgment through motion to vacate under FRCP 60(b)(4).
NCSLT-specific application
National Collegiate Student Loan Trusts (NCSLT) hold substantial portfolios of pre-2014 Sallie Mae-originated loans, now subject to enforcement by NCSLT. Third Circuit’s March 19, 2024 decision established “covered persons” analysis under the Consumer Financial Protection Act; SCOTUS cert denial in December 2024 left Third Circuit precedent in place. Borrowers with private student loan debt held by NCSLT have documented pathways to complete debt elimination through motion to dismiss on standing grounds — producing real answer to will private student loans ever be forgiven through immediate case dismissal.
Debt buyer chain defects
Private student loan debt sold to third-party debt buyers after charge-off often has documentation gaps between original lender ownership and current debt buyer’s asserted ownership. Common defects: missing intermediate assignment documentation; assignments executed without adequate documentation of specific debts included in bulk portfolio sales; blank endorsements without proper allonge chain; discrepancies between servicing records and asserted debt buyer ownership. These defects support standing challenges that can achieve case dismissal and effective debt elimination.
Post-judgment vacation
Because standing is jurisdictional, chain of assignment challenges are preserved even after judgment entry. Motion to vacate under FRCP 60(b)(4) (void judgment) can be filed at any time if the underlying judgment was entered without proper plaintiff standing. Particularly relevant for older default judgments where the borrower did not appear — the standing challenge remains available years or decades later, providing forgiveness through judgment vacation.
Related resources — complete private student loan forgiveness ecosystem
Private Student Loan Forgiveness 2026: Complete Guide (PILAR)
The 7-path master framework covering all private student loan forgiveness mechanisms available in 2026.
Debt Forgiveness for Private Student Loans: What Works 2026
6-mechanism framework for real debt forgiveness including tax planning under IRC §108.
Private Student Loan Debt Help: Your Options 2026
Complete help framework with 6 real options for borrowers facing private student loan debt.
Real forgiveness path 5: Lender hardship programs
Major private student loan lenders offer contract-based hardship programs providing meaningful debt relief. While not statutory forgiveness, these programs can reduce overall debt cost, prevent charge-off, and support longer-term forgiveness strategy. For borrowers asking will private student loans ever be forgiven, lender programs provide immediate relief while longer-term forgiveness mechanisms are evaluated.
Sallie Mae programs
Sallie Mae Bank (NYSE:SLM) offers Loan Modification Program with reduced interest rate (often 4-6%) and reduced payments; Rate Reduction Program for shorter-term relief; Interest-Only Payment Program for 3-12 months; Hardship Forbearance up to 12 months cumulative. Cosigner release after 12 consecutive on-time principal-and-interest payments plus creditworthiness. Death discharge on all Sallie Mae loans; cosigner discharge on borrower death for 2015-and-later loans. Total and Permanent Disability discharge available.
Citizens Bank, SoFi, Earnest, Ascent, Firstmark programs
Citizens Bank NA (NYSE:CFG) offers hardship forbearance and modified payment plans; cosigner release after 36 consecutive on-time payments. SoFi Bank NA (NMLS #696891) offers Unemployment Protection Program up to 3 months paused payments; no cosigner release available. Earnest Operations LLC (Navient subsidiary since 2017) offers skip-a-payment feature; accommodates alternative income sources. Ascent Student Loans offers up to 24 months cumulative hardship forbearance; cosigner release after 24-36 payments. Firstmark Services (Nelnet NYSE:NNI subsidiary, servicing former Discover loans post-July 2024 Carlyle+KKR sale) continues Discover hardship framework.
Real forgiveness path 6: Death and disability discharge
Death and disability discharge are contract-based private loan forgiveness mechanisms offered by most major private lenders. These programs operate through the loan’s own terms, discharging the debt entirely on qualifying death or permanent disability.
Private lender death discharge policies
Death discharge policies vary by lender: Sallie Mae — discharges borrower’s balance on death; cosigner discharge on borrower death for 2015-and-later loans. Discover / Firstmark — discharges on borrower death. SoFi — discharges on borrower death. Earnest — discharges on borrower death. Citizens Bank — discharges on borrower death. Ascent — discharges on borrower death. Specific terms should be verified against current lender documentation.
Private lender disability discharge policies
Disability discharge less consistently offered than death discharge. Sallie Mae — Total and Permanent Disability discharge for qualifying borrowers. Ascent — disability discharge available. Other lenders have varying policies verified case-by-case. Documentation typically requires physician certification of permanent disability meeting lender-specific criteria.
The honest decision framework for borrowers
Stop waiting, start evaluating
If you’ve been asking will private student loans ever be forgiven federally for years, the honest answer is to stop waiting and start evaluating the real forgiveness mechanisms available now. Federal forgiveness extension to private loans has no legislative support and is not reasonably likely in any foreseeable timeframe. Meanwhile, the 6 real forgiveness paths produce measurable results every day. The question is not whether forgiveness exists for your private loans — it does, through these 6 mechanisms — but which specific path(s) fit your situation.
Decision framework by current status
Which real forgiveness path applies depends on your specific circumstances: Current but struggling — lender hardship programs (Path 5) for immediate relief, evaluate longer-term options; Recently delinquent — hardship forbearance to prevent charge-off, early settlement if lump sum available; Charged-off accounts — settlement negotiation (Path 1) typically most cost-effective, chain of assignment analysis (Path 4) for NCSLT/debt-buyer debt, SOL analysis (Path 3); Lawsuit filed — motion to dismiss on standing or SOL grounds, settlement from defensive position, bankruptcy analysis (Path 2); Judgment entered — motion to vacate on standing grounds under FRCP 60(b)(4); Long-standing debt near SOL — careful SOL analysis, avoid revival; Serious financial distress — bankruptcy including Homaidan §523(a)(8); Death or disability — lender-specific discharge application (Path 6).
Multi-path coordination for maximum forgiveness
Effective private student loan forgiveness outcomes typically combine multiple paths: chain of assignment analysis creating settlement leverage; SOL analysis creating urgency for current holder; bankruptcy analysis under Homaidan as credible alternative; hardship program buying time while longer strategy develops; cosigner release combined with refinance. Coordinated multi-path strategy typically produces materially better outcomes than any single path alone — and vastly better outcomes than continued waiting for federal programs that will not materialize.
Common myths about will private student loans ever be forgiven
Myth 1
“Congress will eventually extend federal forgiveness to private loans”
Reality: No credible legislative proposals currently exist to extend federal forgiveness programs to private student loans. Federal forgiveness is fundamentally tied to federal loan statutes under the Higher Education Act. Extending federal forgiveness to private loans would require federal purchase of private debt or federal payment to private lenders — a policy with no meaningful legislative support across multiple administrations and congressional sessions. Borrowers waiting for this expansion are waiting for something that is not reasonably likely to happen. The real forgiveness paths exist now and should not be postponed in hope of federal action.
Myth 2
“Private student loans can never be discharged — only federal loans qualify”
Reality: This widespread myth is factually incorrect. Private student loans ARE regularly discharged through multiple mechanisms available in 2026: bankruptcy discharge under §523(a)(8) with Homaidan v. Sallie Mae Second Circuit precedent (non-qualified loans dischargeable without undue hardship); settlement producing partial forgiveness; chain of assignment challenges producing case dismissal; statute of limitations expiration making debt uncollectible; death and disability discharge from most lenders. The myth persists because many lenders and collectors benefit from borrowers believing nothing can be done — but legally, significant private student debt forgiveness mechanisms exist and are used every day.
Myth 3
“If I just wait long enough, something will come along to help”
Reality: Passive waiting for broad private loan forgiveness that may never come carries substantial real costs: continued interest accumulation at 6-14% annually; continued credit damage during the waiting period; increased litigation risk including potential default judgments; opportunity costs of delayed home purchases, career changes, and family planning; psychological burden of unresolved debt. Meanwhile, the real forgiveness paths available in 2026 produce measurable results in months rather than decades. The question is not whether to pursue forgiveness — it’s which path, and how soon to start.
Myth 4
“Private student loan forgiveness isn’t ‘real’ because it’s not a federal program”
Reality: Forgiveness is forgiveness regardless of its legal mechanism. A borrower whose $80,000 private student loan is settled for $32,000 has received $48,000 in real forgiveness — just as real as any federal program would provide. A borrower whose private loans are discharged in bankruptcy under Homaidan precedent has achieved complete elimination of the debt through court order — functionally equivalent to any federal discharge. The question is not whether private forgiveness is “real” but whether it fits the borrower’s specific situation. For most borrowers struggling with private student loans, the 6 real paths produce better outcomes than waiting for federal programs that will not come.
Frequently asked questions
1. Will private student loans ever be forgiven by the government?
No, there are no credible legislative proposals to extend federal forgiveness programs (PSLF under 20 U.S.C. §1087e(m), IDR forgiveness, Teacher Loan Forgiveness) to private student loans. Federal forgiveness is fundamentally tied to federal loan statutes under the Higher Education Act (20 U.S.C. §1001 et seq.) and would require federal purchase or payment to private lenders using taxpayer funds — a policy with no meaningful legislative support. However, private student loans forgiveness absolutely exists through 6 real mechanisms available now: settlement, bankruptcy discharge under §523(a)(8) with Homaidan precedent, SOL expiration, chain of assignment defense, lender hardship programs, and death/disability discharge.
2. Can private student loans be forgiven at all?
Yes, can private student loans be forgiven is answered yes through 6 proven legal mechanisms: (1) settlement negotiation with current holder producing partial forgiveness (typically 40-60% of balance for charged-off accounts); (2) bankruptcy discharge under 11 U.S.C. §523(a)(8) with Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) precedent making non-qualified private loans dischargeable without undue hardship; (3) statute of limitations expiration under state SOL (3-15 years by state); (4) chain of assignment defense on Article III standing grounds (Lujan/Spokeo/TransUnion); (5) lender hardship programs modifying debt terms; (6) death and disability discharge from most private lenders. Which path applies depends on specific circumstances.
3. Are private student loans forgivable in bankruptcy?
Yes, are private student loans forgivable in bankruptcy is answered yes for most private loans following Circuit Court precedents. Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) established that direct-to-consumer loans without school certification of cost of attendance do NOT qualify as “educational benefit” under §523(a)(8)(A)(ii) and are therefore dischargeable WITHOUT undue hardship showing. Similar precedents in Fifth Circuit (Crocker v. Navient 941 F.3d 206) and Tenth Circuit (McDaniel v. Navient 973 F.3d 1083). Private loans that DO qualify under §523(a)(8) can still discharge through Brunner undue hardship test (Brunner v. New York State HESC 831 F.2d 395), moderated by In re Rosenberg 594 B.R. 22 (Bankr. S.D.N.Y. 2020) and DOJ November 2022 guidance.
4. What is private student debt forgiveness in 2026?
Private student debt forgiveness in 2026 refers to the legal mechanisms that reduce or eliminate private student loan debt owed to private lenders (Sallie Mae Bank NYSE:SLM, Navient/Earnest Operations LLC, Discover/Firstmark Services, SoFi Bank NA, Citizens Bank NA, Ascent, others). It operates entirely outside federal forgiveness programs (which only apply to federal loans). The 6 real mechanisms are settlement, bankruptcy discharge, SOL expiration, chain of assignment defense, lender hardship programs, and death/disability discharge. Each mechanism produces real debt reduction when applied correctly, and most borrowers qualify for at least one.
5. How long will it take for private student loan forgiveness to pass?
Federal legislation extending forgiveness programs to private student loans is not reasonably likely in any foreseeable timeframe. Multiple legislative sessions have passed without such proposals gaining traction. The structural barriers (requiring federal payment to private lenders) and political obstacles have remained consistent across administrations. Rather than waiting indefinitely for legislation that may never come, borrowers should evaluate the real forgiveness mechanisms available now — settlement typically completes in 2-6 months, bankruptcy discharge in 3-4 months (Chapter 7), chain of assignment challenges in 6-18 months. The 6 real paths produce private student loan forgiveness faster than any federal program would.
6. Does Biden/Trump student loan forgiveness cover private loans?
No. All announced student loan forgiveness initiatives from recent administrations have applied exclusively to federal loans (Direct Loans, FFEL federal loans, Perkins federal loans). None have included private student loans from Sallie Mae, Navient/Earnest, Discover/Firstmark, SoFi, Citizens, Ascent, or other private lenders. Private loans fall outside the federal regulatory framework governing these forgiveness programs. If your loans are private (verify via studentaid.gov NSLDS — federal loans appear there, private loans do NOT), you need the 6 real forgiveness paths in this guide rather than federal programs.
7. Should I wait for private student loan forgiveness or act now?
Act now. Waiting for federal private student loans forgiveness that is not reasonably likely to materialize carries substantial real costs: continued 6-14% annual interest accumulation; continued credit damage; increased litigation risk; opportunity costs of delayed life decisions. The 6 real forgiveness paths available in 2026 produce measurable results in months rather than decades. For a borrower with $80,000 in private student loans, settling for $32,000 now (producing $48,000 in real forgiveness) is dramatically better than waiting indefinitely while interest accumulates and credit damage continues. The question is not whether forgiveness exists for your situation — it does — but how soon you start pursuing it.
Stop Waiting — Start Resolving
Free specialist review of all 6 real forgiveness paths for your private student loans.
Settlement negotiation analysis, bankruptcy discharge evaluation under §523(a)(8) with Homaidan precedent, statute of limitations analysis by state, chain of assignment defensive framework for NCSLT-held and debt-buyer debt, lender hardship program qualification, and coordinated multi-path approach. Honest answer about what’s actually possible for your private student loan debt — not vague promises about federal programs that won’t come. Free eligibility review with attorney-backed partner provider — no upfront fees.
Get a free eligibility review →
5-minute review · No obligation · Zero upfront fees · Since 2015 · 48 states served
About the author
Henry Silva — Private Student Loan Debt Specialist
10+ years experience giving honest answers to borrowers asking will private student loans ever be forgiven through federal programs — and delivering real results through the 6 actual forgiveness mechanisms that work in 2026: settlement negotiation with major private lenders (Sallie Mae Bank NYSE:SLM, Navient/Earnest Operations LLC, Discover/Firstmark Services after July 2024 Carlyle+KKR sale, SoFi Bank NA NMLS #696891, Citizens Bank NA NYSE:CFG, Ascent Student Loans), bankruptcy discharge analysis under 11 U.S.C. §523(a)(8) with Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) precedent, Crocker v. Navient 941 F.3d 206 (5th Cir. 2019), McDaniel v. Navient 973 F.3d 1083 (10th Cir. 2020), Brunner v. New York State Higher Education Services Corp. 831 F.2d 395 (2d Cir. 1987) framework for qualified loans, In re Rosenberg 594 B.R. 22 (Bankr. S.D.N.Y. 2020) updated application, statute of limitations analysis across all 50 states, hardship program qualification, cosigner release strategy, chain of assignment challenges under Article III standing doctrine (Lujan/Spokeo/TransUnion), NCSLT Third Circuit precedent application, IRC §108(a)(1)(A) bankruptcy and IRC §108(a)(1)(B) insolvency tax exclusion analysis, and coordinated multi-path strategy for maximum forgiveness outcomes. Henry works with Private Student Relief’s attorney-backed partner provider network to review individual scenarios across all 6 real private student loan forgiveness mechanisms.
Legal Disclaimer and Sources
This article is provided for informational purposes only and does not constitute legal, tax, or financial advice. Private Student Relief is a consulting and matching organization operated by Joco (555 Anton Blvd, Suite 368, Costa Mesa, CA 92626) — not a law firm, debt settlement company, debt consolidation company, or loan provider. Debt validation services are performed by an attorney-backed partner provider (Panamerican Consulting LLC, Las Vegas, NV) under independent business credentials. Ratings, BBB accreditation, and AADR membership referenced on the PSR website belong to the partner provider. Private student loan forgiveness pathway availability depends on loan characteristics, lender terms, borrower circumstances, and jurisdiction. Individual results vary. Since 2015. 48 states served. Not available in South Carolina or Mississippi.
Federal student loan program citations (for comparison, these do NOT apply to private student loans): Higher Education Act (20 U.S.C. §1001 et seq.); Public Service Loan Forgiveness (20 U.S.C. §1087e(m)); Income-Driven Repayment forgiveness (federal loan regulatory framework); Direct Loan death discharge (20 U.S.C. §1087); Perkins Loan death discharge (20 U.S.C. §1087dd). These federal programs apply ONLY to federal loans and no credible legislative proposals exist to extend them to private student loans.
Bankruptcy Code references: 11 U.S.C. §523(a)(8) (student loan discharge exceptions with §523(a)(8)(A)(i) governmental unit, §523(a)(8)(A)(ii) educational benefit, §523(a)(8)(B) qualified education loan categories); 11 U.S.C. §362 (automatic stay); 11 U.S.C. §707(b)(2) (means test); 11 U.S.C. §1328 (Chapter 13 discharge). Key bankruptcy precedent: Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) — direct-to-consumer private education loans dischargeable without undue hardship; Brunner v. New York State Higher Education Services Corp. 831 F.2d 395 (2d Cir. 1987) — undue hardship test; Crocker v. Navient Solutions LLC 941 F.3d 206 (5th Cir. 2019); McDaniel v. Navient Solutions LLC 973 F.3d 1083 (10th Cir. 2020); In re Rosenberg 594 B.R. 22 (Bankr. S.D.N.Y. 2020). Article III standing precedent: Lujan v. Defenders of Wildlife 504 U.S. 555 (1992); Spokeo, Inc. v. Robins 578 U.S. 330 (2016); TransUnion LLC v. Ramirez 594 U.S. 413 (2021). Federal Rules of Civil Procedure: FRCP 60(b)(4) (void judgment). Internal Revenue Code: IRC §221(d)(1) (qualified education loan definition); IRC §108(a)(1)(A) (bankruptcy exclusion); IRC §108(a)(1)(B) (insolvency exclusion). FDCPA: 15 U.S.C. §1692g (debt validation); 15 U.S.C. §1692e (deceptive practices).
Statute of limitations for written contract debt (private student loans) by state: Texas 4 years under Tex. Civ. Prac. & Rem. Code §16.004(a)(3); New York 3 years under CPLR §214(2) per Consumer Credit Fairness Act (CCFA) effective April 7, 2022; Pennsylvania 4 years under 42 Pa.C.S. §5525; Ohio 6 years under Ohio R.C. §2305.06 (reduced 2021); Illinois 10 years under 735 ILCS 5/13-206; Georgia 6 years under O.C.G.A. §9-3-24; California 4 years under CCP §337; Florida 5 years under Fla. Stat. §95.11(2)(b); Delaware 3 years under 10 Del. C. §8106. Complete state SOL analysis should be verified against current statutes for each specific borrower situation.
Lender information current as of October 2026 per publicly available documentation: Sallie Mae Bank NYSE:SLM; Navient Corporation NYSE:NAVI (2014 Sallie Mae split; 2017 Earnest acquisition $155M; December 2021 Aidvantage transfer federal exit; January 2022 state attorneys general settlement $1.85B); Earnest Operations LLC (Navient subsidiary since 2017); Discover student loans acquired by Carlyle Group and KKR July 2024 with servicing transitioned to Firstmark Services (Nelnet NYSE:NNI subsidiary); SoFi Bank NA NMLS #696891 (chartered as national bank 2022); Citizens Bank NA NYSE:CFG; Ascent Student Loans with June 5, 2023 originated loans having contractual §523(a)(8) discharge waiver. Specific lender program details subject to change and should be verified directly with current lender documentation.
The question will private student loans ever be forgiven requires honest distinction between federal programs (not reasonably likely to extend to private loans) and the 6 real forgiveness mechanisms available now (settlement, bankruptcy discharge, SOL expiration, chain of assignment defense, lender programs, death/disability discharge). This article provides general framework information; specific settlement negotiations, bankruptcy filings under Homaidan precedent, chain of assignment challenges, hardship program applications, cosigner release strategies, and coordinated multi-path approaches must be evaluated for each borrower’s individual situation by counsel or consulting resources familiar with the complete private student loan forgiveness framework. Last reviewed: October 2026.