

Informational content only. Not legal, tax, or financial advice. Private Student Relief is a consulting organization, not a law firm. Debt validation services are executed by an attorney-backed partner provider. Debt forgiveness pathway availability depends on loan characteristics, lender terms, borrower circumstances, and jurisdiction. Last reviewed: September 2026.
Written by Henry Silva
Private Student Loan Debt Specialist · 10+ years experience delivering real debt forgiveness for private student loans: settlement negotiation with Sallie Mae Bank (NYSE:SLM), Navient/Earnest Operations LLC, Discover/Firstmark Services, SoFi Bank NA, Citizens Bank NA, and Ascent Student Loans; bankruptcy discharge under 11 U.S.C. §523(a)(8) with Homaidan v. Sallie Mae Second Circuit precedent; chain of assignment challenges under Article III standing doctrine; NCSLT-specific defensive frameworks; and coordinated multi-path private loan forgiveness strategy. Last reviewed: September 2026.
The most common question borrowers ask is: does debt forgiveness for private student loans actually exist? The honest answer is yes — but not through the federal programs most people think of (PSLF, IDR forgiveness). Federal forgiveness programs apply ONLY to federal loans. For private loans from Sallie Mae, Navient/Earnest, Discover/Firstmark, SoFi, Citizens, Ascent, and other private lenders, private loan forgiveness works through six real legal mechanisms that this guide covers in detail. What actually works: settlement negotiation for less than balance, bankruptcy discharge under 11 U.S.C. §523(a)(8), statute of limitations expiration, chain of assignment defense on standing grounds, lender-specific hardship modification programs, and death/disability discharge. What doesn’t work: waiting for federal forgiveness that will never come, paying for “government-approved” scams, or believing myths about private student debt being permanent. This is the complete framework of what real private student loan debt forgiveness looks like in 2026.
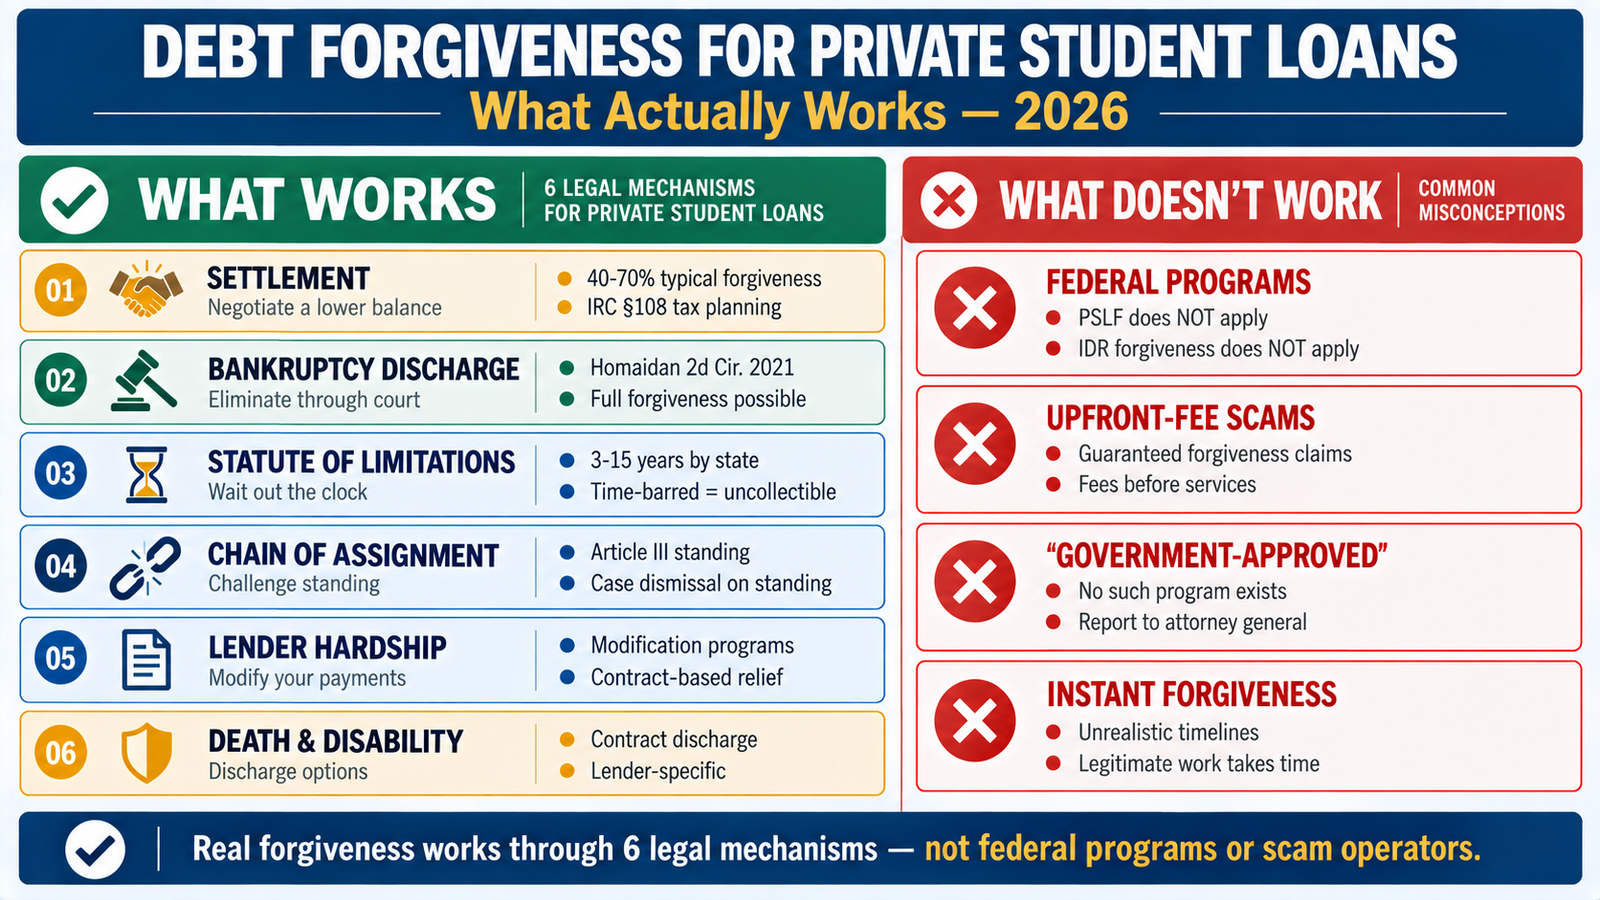
Quick Answer
Debt forgiveness for private student loans works through six real mechanisms (federal programs like PSLF and IDR do NOT apply): (1) Settlement — negotiating with the current holder to pay a reduced lump sum in full satisfaction, with the difference forgiven and reported on Form 1099-C (potential IRC §108 exclusions apply); (2) Bankruptcy discharge under 11 U.S.C. §523(a)(8) — non-qualified loans dischargeable without undue hardship under Homaidan v. Sallie Mae Second Circuit precedent (992 F.3d 100, 2d Cir. 2021); qualified loans dischargeable with undue hardship showing through Brunner test; (3) Statute of limitations expiration — state SOL (3-15 years) making time-barred debt uncollectible; (4) Chain of assignment defense — challenging creditor standing under Article III doctrine when documentation is defective, particularly effective for NCSLT-held debt; (5) Lender hardship programs — Sallie Mae Loan Modification, Citizens hardship forbearance, SoFi Unemployment Protection, Earnest skip-a-payment, Ascent 24-month cumulative forbearance, Firstmark deferment; (6) Death and disability discharge — offered by most private lenders as contract-based forgiveness. What actually works depends on loan status, holder, borrower circumstances, and defensive framework opportunities.
Read the complete framework below.
In this complete debt forgiveness guide:
What “debt forgiveness for private student loans” really means
Legal definitions, tax treatment, and outcomes that qualify as forgiveness
Mechanism 1: Settlement forgiveness — what actually works
How settlement forgives portion above payment, tax planning, timing
Mechanism 2: Bankruptcy discharge — the full-forgiveness path
Homaidan precedent, non-qualified loans, Brunner test framework
Mechanism 3: Statute of limitations — time-based forgiveness
State SOL analysis, revival concerns, defensive application
Mechanism 4: Chain of assignment — standing-based forgiveness
Article III challenges, NCSLT precedent, debt buyer chain defects
Mechanism 5: Lender hardship programs — contractual relief
Sallie Mae, Citizens, SoFi, Earnest, Ascent, Firstmark specifics
Mechanism 6: Death and disability discharge — lender contract terms
Which private lenders offer discharge and specific requirements
What doesn’t work — myths and scams to avoid
Federal program confusion, scam operators, unrealistic expectations
What “debt forgiveness for private student loans” really means
Before exploring what works, it helps to define what debt forgiveness for private student loans actually means legally. “Forgiveness” in the private loan context is different from federal forgiveness. Federal forgiveness (PSLF, IDR forgiveness) is a statutory program where the U.S. Department of Education discharges federal loan debt through defined eligibility criteria — the debt is eliminated by federal action. Private loan forgiveness has no statutory equivalent — instead, it’s achieved through legal mechanisms that eliminate, reduce, or make uncollectible private debt through negotiation, court proceedings, contract terms, or defensive framework.
Legal outcomes that qualify as forgiveness
Six legal outcomes qualify as loan forgiveness private loans: (1) Settlement — the debt above the settlement payment is legally forgiven, reported on Form 1099-C, cannot be collected further; (2) Bankruptcy discharge — the debt is legally eliminated through court order under 11 U.S.C. §523(a)(8), regardless of whether it’s a “qualified education loan” per Homaidan analysis; (3) Statute of limitations expiration — the debt still legally exists but becomes uncollectible through litigation; (4) Chain of assignment dismissal — the case is dismissed and the current plaintiff cannot re-file, effectively orphaning the debt; (5) Contractual discharge — the lender’s own program terms discharge the debt (death, disability); (6) Modification-based relief — the lender modifies the debt through hardship programs, reducing overall cost. Each mechanism produces legally-binding relief that qualifies as forgiveness in practical terms.
Tax treatment of debt forgiveness
Cancellation of debt of $600 or more is reported by the creditor on Form 1099-C to the IRS. The cancelled amount is generally taxable income in the year of cancellation. Important IRC §108 exclusions: Insolvency exclusion under IRC §108(a)(1)(B) — cancelled debt is excluded to the extent borrower was insolvent (liabilities exceeded assets) immediately before cancellation; many borrowers pursuing debt forgiveness qualify because financial distress often means insolvency; Bankruptcy exclusion under IRC §108(a)(1)(A) — debt cancelled in Title 11 bankruptcy proceeding is excluded from income entirely. Consulting a CPA experienced with debt cancellation for individualized §108 analysis before finalizing settlement is essential — proper §108 planning can eliminate the tax liability that would otherwise apply to forgiven amounts.
The six mechanisms this guide covers
The remainder of this guide walks through the six real mechanisms for debt forgiveness for private student loans: Settlement (Mechanism 1) — most accessible, achievable in 2-6 months for most borrowers; Bankruptcy discharge (Mechanism 2) — most powerful, particularly under Homaidan for non-qualified loans; Statute of limitations (Mechanism 3) — passive but potent for older debt; Chain of assignment defense (Mechanism 4) — can achieve complete dismissal for NCSLT-held or debt buyer portfolios; Lender hardship programs (Mechanism 5) — contract-based relief with varying degrees of forgiveness; Death and disability discharge (Mechanism 6) — contract-based full forgiveness for qualifying circumstances.
Mechanism 1: Settlement forgiveness — what actually works
Settlement is the most accessible mechanism for private loan forgiveness for most borrowers. Rather than paying the full amount owed, the borrower negotiates with the current holder to pay a reduced lump sum in full satisfaction. The portion above the settlement payment is legally forgiven — this is real, binding debt forgiveness that produces immediate outcomes for the amount above the settlement payment.
How settlement forgiveness works legally
Settlement is a contract between borrower and current holder that: (1) specifies the settlement amount as full satisfaction of the entire debt; (2) releases the borrower from further obligation on the balance above settlement payment; (3) directs credit reporting updates to Experian, Equifax, TransUnion reflecting settlement; (4) releases cosigner for cosigned loans; (5) may include covenants regarding future collection, disparagement, or confidentiality. Once payment is made and release executed, the debt above settlement is legally eliminated. This qualifies as private student loan debt forgiveness under both legal and practical definitions.
Realistic settlement discounts by loan status
Settlement discounts vary substantially by loan status: Current or early delinquent (0-90 days) — lenders typically resist settlement, preferring hardship modification; settlement rare and unfavorable; 90-180 days delinquent — settlement becomes possible as charge-off approaches; Charged-off status (typically 180+ days) — settlement opportunities emerge, often 40-60% typical discount; Sold to debt buyer — debt buyers acquired at pennies on dollar and often accept substantial discounts, sometimes 30-50% of balance; Pre-litigation with defensive framework — chain of assignment issues or SOL status improve leverage; Post-judgment — settlement still possible but from constrained position. Approaching settlement with proper defensive framework analysis produces meaningfully better outcomes than passive settlement.
Settlement timing strategy
Timing significantly affects settlement outcomes: (1) charge-off (typically 180 days delinquent) triggers write-down on lender’s books, changing internal calculus; (2) end of quarter/year timing may improve outcomes as lenders push to close cases; (3) approaching statute of limitations creates urgency for lenders to settle rather than lose litigation right; (4) approaching judgment revival deadline creates similar dynamic; (5) coordinated timing with lump sum funding availability affects negotiation position. Strategic timing analysis is part of coordinated settlement approach.
IRC §108 tax planning for settlement forgiveness
IRC §108 exclusions are critical for settlement forgiveness planning. Insolvency exclusion under IRC §108(a)(1)(B) excludes cancelled debt to the extent the borrower’s total liabilities exceeded total assets immediately before the cancellation. Insolvency is computed based on all liabilities (including the debt being cancelled and all other debts) and all assets (including retirement accounts and other assets that would otherwise be exempt from creditors). Many borrowers pursuing debt forgiveness qualify for insolvency exclusion because their financial distress often creates negative net worth. The exclusion applies dollar-for-dollar up to insolvency amount. Bankruptcy exclusion under IRC §108(a)(1)(A) excludes debt cancelled in Title 11 proceeding entirely. Proper §108 planning coordinated with settlement timing and documentation can eliminate the tax liability that would otherwise apply to forgiven amounts.
Mechanism 2: Bankruptcy discharge — the full-forgiveness path
Bankruptcy discharge is the most powerful mechanism for loan forgiveness for private loans — it can eliminate the entire debt through court order, not just reduce it. The prevailing myth that “student loans can never be discharged” is outdated for private loans following the Homaidan v. Sallie Mae Second Circuit precedent. Understanding when and how bankruptcy discharge produces private student loan forgiveness is essential.
The §523(a)(8) framework
11 U.S.C. §523(a)(8) makes certain educational loans non-dischargeable unless “undue hardship” is shown. The categories: §523(a)(8)(A)(i) — loans made, insured, or guaranteed by governmental unit (federal loans); §523(a)(8)(A)(ii) — “obligation to repay funds received as an educational benefit, scholarship, or stipend”; §523(a)(8)(B) — “qualified education loan” as defined in IRC §221(d)(1). Private loans NOT falling within these three categories are dischargeable WITHOUT undue hardship showing. This is where Homaidan becomes the critical precedent for many borrowers.
Homaidan v. Sallie Mae — the game-changing precedent
Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) established that “educational benefit” under §523(a)(8)(A)(ii) is narrow — referring to specific benefits like scholarships and stipends, not general private education loans. The Second Circuit held that Sallie Mae’s direct-to-consumer loans (made directly to students without school certification of cost of attendance) do NOT qualify as “educational benefit” and are therefore dischargeable WITHOUT undue hardship showing. Similar precedents in Fifth Circuit (Crocker v. Navient 941 F.3d 206, 5th Cir. 2019) and Tenth Circuit (McDaniel v. Navient 973 F.3d 1083, 10th Cir. 2020). This precedent produces genuine full private student loan debt forgiveness for qualifying loans.
Which private loans discharge under Homaidan
Private loans potentially dischargeable without undue hardship under Homaidan analysis: (1) direct-to-consumer loans without school certification of cost of attendance; (2) loans exceeding “cost of attendance” limit for enrollment period; (3) loans for non-title IV eligible programs (some bar prep, vocational, for-profit institution programs); (4) loans to students not enrolled at least half-time; (5) loans failing other IRC §221(d)(1) “qualified education loan” requirements. Case-by-case analysis of origination documents determines Homaidan eligibility. Many Sallie Mae, Navient/Earnest, and other private loans meet these criteria.
Qualified loans and the Brunner undue hardship test
Private loans qualifying under §523(a)(8) require undue hardship showing. Most circuits apply the Brunner test from Brunner v. New York State Higher Education Services Corp. 831 F.2d 395 (2d Cir. 1987): (1) debtor cannot maintain minimal standard of living while repaying; (2) additional circumstances indicate this will persist for significant portion of repayment period; (3) debtor has made good faith efforts to repay. First and Eighth Circuits apply “totality of circumstances” test. Recent case law (In re Rosenberg 594 B.R. 22, Bankr. S.D.N.Y. 2020) and DOJ guidance (November 2022) have moderated Brunner’s historically harsh application, making discharge more accessible for qualifying loans.
Ascent college loans — contractual discharge waiver
Ascent college loans originated June 5, 2023 or later have contractual waiver of the §523(a)(8) discharge protection per Ascent’s own terms — meaning these loans can be discharged in bankruptcy WITHOUT the undue hardship showing that normally applies to qualifying loans. This is a unique feature of Ascent college loans from this period and provides the clearest path to debt forgiveness for private student loans through bankruptcy for borrowers who have this specific loan product.
Chapter 7 vs Chapter 13 selection
Chapter 7 provides discharge of most unsecured debts including qualifying private student loans in 3-4 months. Chapter 13 involves 3-5 year payment plan with discharge under 11 U.S.C. §1328 at completion. Chapter selection depends on: means test qualification (Chapter 7 requires income below state median or successful means test under 11 U.S.C. §707(b)(2)); asset preservation needs; whether payment plan restructuring benefits overall situation; specific bankruptcy jurisdiction. Bankruptcy counsel familiar with §523(a)(8) adversary proceeding practice is essential.
Mechanism 3: Statute of limitations — time-based forgiveness
Statute of limitations expiration creates a form of time-based debt forgiveness for private student loans. When state SOL expires on a private student loan, the current holder loses the legal ability to file suit to collect the debt. While the debt still legally exists, it becomes uncollectible through litigation — effectively producing forgiveness in practical terms for older debt.
State SOL for private student loan debt
SOL periods for written contract debt (private student loans) vary significantly by state: Texas 4 years under Tex. Civ. Prac. & Rem. Code §16.004(a)(3); New York 3 years under CPLR §214(2) per Consumer Credit Fairness Act (CCFA) effective April 7, 2022 (reduced from 6 years — major change for NY private student loan borrowers); Pennsylvania 4 years under 42 Pa.C.S. §5525; Ohio 6 years under Ohio R.C. §2305.06 (reduced from 8 years effective 2021); Illinois 10 years under 735 ILCS 5/13-206; Georgia 6 years under O.C.G.A. §9-3-24; California 4 years under CCP §337; Florida 5 years under Fla. Stat. §95.11(2)(b); Delaware 3 years under 10 Del. C. §8106. Accrual is typically date of first default or last payment.
Revival concerns for older debt
Borrowers with older private student loan debt must carefully avoid actions that could restart the SOL clock: making any payment on the debt (even small “goodwill” payments) may restart the SOL; written acknowledgment of the debt including hardship program applications, settlement offers, or promise to pay may create restart; new agreement or written promise to pay resets timing. Debt collectors sometimes solicit small payments or written communications specifically to revive time-barred debt — a practice that may itself violate FDCPA 15 U.S.C. §1692e. Consulting counsel before communicating with creditors on old debt prevents inadvertent revival.
Defensive application when SOL expires
When SOL has expired: (1) debt legally exists but cannot be enforced through litigation; (2) collection calls and letters can be disputed under FDCPA 15 U.S.C. §1692g if third-party collector involved; (3) if lawsuit is filed on time-barred debt, motion to dismiss based on SOL expiration succeeds and may support FDCPA counterclaim; (4) credit reporting continues under 7-year FCRA reporting period regardless of SOL; (5) settlement of time-barred debt should proceed carefully to avoid revival. SOL expiration produces effective debt forgiveness for private student loans by making the debt uncollectible.
Mechanism 4: Chain of assignment — standing-based forgiveness
Chain of assignment defense produces one of the most powerful forms of loan forgiveness private loans — case dismissal on standing grounds that effectively eliminates the debt when the current plaintiff cannot demonstrate right to enforce. Under Article III of the U.S. Constitution, plaintiffs must have standing to bring suit. For private student loan enforcement, plaintiff must demonstrate complete chain of ownership from original lender to themselves. Defects in this chain provide grounds for dismissal.
Article III standing framework
Article III standing requires: (1) concrete and particularized injury; (2) causally connected to defendant’s conduct; (3) redressable by court decision. Established in Lujan v. Defenders of Wildlife 504 U.S. 555 (1992), refined in Spokeo, Inc. v. Robins 578 U.S. 330 (2016), and further developed in TransUnion LLC v. Ramirez 594 U.S. 413 (2021). Standing is jurisdictional and can be raised at any stage of proceedings, including post-judgment through motion to vacate under FRCP 60(b)(4).
NCSLT-specific application
National Collegiate Student Loan Trusts (NCSLT) hold substantial portfolios of private student loans, particularly Sallie Mae-originated loans from 2001-2007. NCSLT litigation has developed extensive precedent for chain of assignment challenges. Key developments: Third Circuit’s March 19, 2024 decision establishing “covered persons” analysis; SCOTUS cert denial in December 2024 leaving Third Circuit precedent in place; various stipulated resolutions through 2026. Borrowers with private student loan debt held by NCSLT have documented pathways to complete debt elimination through motion to dismiss or motion to vacate judgment on standing grounds.
Debt buyer chain defects
Private student loan debt sold to third-party debt buyers after charge-off often has documentation gaps supporting standing challenges. Common defects: missing intermediate assignment documentation; assignments executed without adequate documentation of specific debts in bulk sales; blank endorsements without allonge chain; discrepancies between servicing records and asserted debt buyer ownership. Debt buyers typically purchased at pennies on the dollar without obtaining complete assignment documentation for individual loans — creating standing challenges that produce case dismissal and effective forgiveness.
Post-judgment vacation
Because standing is jurisdictional, chain of assignment challenges are preserved even after judgment has been entered. Motion to vacate under FRCP 60(b)(4) (void judgment) or state law analog can be filed at any time if the underlying judgment was entered without proper plaintiff standing. This is particularly relevant for older default judgments where the borrower did not appear at the time — the standing challenge remains available years or decades later, potentially achieving vacation of judgment and effective forgiveness of the debt long after original entry.
Related resources — complete forgiveness framework
Private Student Loan Forgiveness 2026: Complete Guide (PILAR)
The 7-path master framework covering all private student loans — the pilar resource for all cluster posts including this one.
Sallie Mae Debt Forgiveness 2026: Real Options
Sallie Mae-specific application of the framework with Homaidan precedent, NCSLT chain analysis, and cosigner release program.
How to Get Rid of Private Student Loans 2026
5-path framework for getting rid of private student loans with decision framework by loan status.
Mechanism 5: Lender hardship programs — contractual relief
Major private student loan lenders offer contract-based hardship programs that provide meaningful relief. While not “forgiveness” in the strictest sense, these programs can reduce overall debt cost, prevent charge-off, and support longer-term forgiveness strategy. Understanding lender-specific programs is essential to comprehensive debt forgiveness for private student loans strategy.
Sallie Mae programs
Sallie Mae Bank (NYSE:SLM) offers Loan Modification Program with reduced interest rate (often 4-6%) and temporarily reduced payments for qualifying borrowers; Rate Reduction Program for shorter-term relief; Interest-Only Payment Program for 3-12 months; Hardship Forbearance up to 12 months cumulative. Sallie Mae cosigner release available after 12 consecutive on-time principal-and-interest payments plus creditworthiness. Death discharge on all Sallie Mae loans; cosigner discharge on borrower death applies to 2015-and-later loans. Total and Permanent Disability discharge available.
Citizens Bank programs
Citizens Bank NA (NYSE:CFG) offers hardship forbearance and modified payment plans through Loan Servicing Center. Citizens Education Refinance Loan program provides refinance opportunities for borrowers with strong credit. Cosigner release available after 36 consecutive on-time principal-and-interest payments plus criteria. Death discharge available.
SoFi programs
SoFi Bank NA (NMLS #696891) offers Unemployment Protection Program providing up to 3 months of paused payments for qualifying job loss, plus short-term Discretionary Forbearance for other hardship circumstances. Important: SoFi does NOT offer cosigner release — cosigner status permanent absent full refinance without cosigner. Death discharge available.
Earnest programs
Earnest Operations LLC (Navient subsidiary since 2017 acquisition) offers skip-a-payment feature (one skipped payment per 12-month period) and hardship forbearance. Generally more accommodating of alternative income sources including gig work and self-employment. Cosigner release available after qualifying period. Death discharge available.
Ascent programs
Ascent Student Loans offers up to 24 months cumulative hardship forbearance plus specific programs for job loss or medical hardship. Cosigner release after 24 or 36 consecutive on-time payments depending on product. Ascent college loans originated June 5, 2023 or later have contractual §523(a)(8) discharge waiver. Death and disability discharge available.
Discover / Firstmark Services programs
Firstmark Services (Nelnet NYSE:NNI subsidiary) services former Discover student loans following July 2024 Carlyle+KKR sale of Discover’s student loan portfolio. Firstmark offers hardship deferment and modified payment programs continuing the Discover framework. Cosigner release policies continue through Firstmark servicing. Death discharge available.
Mechanism 6: Death and disability discharge — lender contract terms
Death and disability discharge are contract-based mechanisms for debt forgiveness for private student loans offered by most major private lenders. These programs operate through the loan’s own terms rather than statutory forgiveness, discharging the debt entirely on qualifying death or permanent disability.
Federal loan discharge for comparison
For comparison, federal loans have statutory discharge on death under 20 U.S.C. §1087 (Direct Loans) and 20 U.S.C. §1087dd (Perkins Loans). Federal Total and Permanent Disability discharge is available for borrowers meeting specific criteria. These statutory federal protections do NOT apply to private loans — private loan death and disability discharge depends entirely on each specific lender’s contract terms.
Private lender death discharge policies
Death discharge policies vary by private lender: Sallie Mae — discharges borrower’s remaining balance on death; cosigner discharge on death applies to 2015-and-later loans. Discover / Firstmark — discharges on borrower death. SoFi — discharges on borrower death. Earnest — discharges on borrower death. Citizens Bank — discharges on borrower death. Ascent — discharges on borrower death. Specific terms should be verified against current lender documentation. Estate administrators should promptly notify each lender of borrower death with proper documentation (death certificate typically required within 60 days) to activate discharge processing.
Private lender disability discharge policies
Disability discharge is less consistently offered than death discharge. Sallie Mae — Total and Permanent Disability discharge for qualifying borrowers with physician certification. Ascent — disability discharge available. Other lenders have varying policies verified case-by-case. Documentation typically requires physician certification of permanent disability meeting lender-specific criteria (which may or may not match federal disability discharge standards).
Estate and family planning
Death and disability discharge policies affect family financial planning: (1) lenders offering death discharge protect family assets from debt claims after borrower death; (2) cosigner exposure may continue after borrower death for older cosigned loans; (3) life insurance coordination provides protection regardless of discharge policy; (4) coordinated estate planning addresses these considerations comprehensively. Families should not make payments on loans of deceased borrowers before confirming discharge processing — such payments may be reclaimable but complicate discharge.
What doesn’t work — myths and scams to avoid
Understanding what actually works requires understanding what doesn’t. Confusion about debt forgiveness for private student loans creates opportunities for scam operators and unrealistic expectations. Common myths and scams to avoid include federal program confusion, upfront-fee scams, “government-approved” claims, and unrealistic timeline promises.
Federal program confusion
The most common misconception is that federal forgiveness programs (PSLF, IDR forgiveness, executive-action forgiveness) apply to private loans. They do NOT. Federal forgiveness programs are codified in Higher Education Act statutes and regulations that apply only to federal loans (Direct Loans, some consolidated FFEL). Private loans from Sallie Mae, Navient/Earnest, Discover/Firstmark, SoFi, Citizens, Ascent, and other private lenders are NEVER eligible for federal forgiveness programs. Any claim otherwise is misrepresentation. Real private loan forgiveness comes through the six mechanisms in this guide.
Upfront-fee scam operators
Scam operators charge upfront fees for services that either don’t produce results or don’t require the operator at all. Warning signs: promises of “automatic” or “guaranteed” forgiveness; upfront fees before services rendered; claims of special government relationships; new “programs” for private loan forgiveness that don’t actually exist; pressure to act immediately. Legitimate private student relief providers work through actual legal frameworks (the six mechanisms in this guide), charge fees only after services rendered, and set realistic expectations. If it sounds too good to be true, it typically is.
“Government-approved” claims
Any company claiming “government-approved” private student loan forgiveness is misrepresenting the law. There is no government approval process for private student loan forgiveness — because there is no federal government program for private loans. The federal government does not approve, endorse, certify, or authorize any private company to provide private student loan forgiveness. Companies making these claims are either lying or fundamentally misunderstanding the law. Report such claims to state attorney general’s office or FTC.
Unrealistic timeline promises
Realistic timelines for the mechanisms in this guide: settlement 2-6 months from initial negotiation to completed settlement; bankruptcy Chapter 7 typically 3-4 months from filing to discharge; Chapter 13 typically 3-5 years to plan completion; chain of assignment challenges typically 6-18 months for motion practice; statute of limitations timing depends on state law (3-15 years). Promises of “instant” forgiveness, “24-hour approval”, or unrealistically fast outcomes indicate scam operators. Legitimate work takes time proportional to the complexity of the mechanism being used.
Common myths about debt forgiveness for private student loans
Myth 1
“There is no such thing as debt forgiveness for private student loans”
Reality: Debt forgiveness for private student loans IS available through six real mechanisms: settlement, bankruptcy discharge, statute of limitations, chain of assignment defense, lender hardship programs, and death/disability discharge. What is NOT available is federal-style forgiveness programs (PSLF, IDR forgiveness). Confusion between the absence of federal programs and the absence of any forgiveness creates this myth. Real debt forgiveness for private student loans exists — it just works through different legal mechanisms than federal loans.
Myth 2
“Only bankruptcy provides real forgiveness for private loans”
Reality: Bankruptcy is one mechanism among six. Settlement forgives the portion above the settlement payment (typically 40-70% discount). Statute of limitations makes debt uncollectible through litigation. Chain of assignment challenges can dismiss cases entirely. Lender hardship programs modify debt terms. Death/disability discharge eliminates debt entirely for qualifying situations. Each mechanism produces real forgiveness in specific circumstances — bankruptcy is the most powerful but not the only path.
Myth 3
“Debt forgiveness always means paying taxes on the forgiven amount”
Reality: Cancellation of debt is generally taxable, but IRC §108 provides significant exclusions. Insolvency exclusion under IRC §108(a)(1)(B) excludes cancelled debt to extent borrower was insolvent (liabilities exceeded assets) immediately before cancellation. Bankruptcy exclusion under IRC §108(a)(1)(A) excludes debt cancelled in Title 11 proceedings entirely. Many borrowers pursuing forgiveness qualify for these exclusions and pay little or no tax on forgiven amounts. Proper §108 tax planning with experienced CPA is essential for maximizing forgiveness value.
Myth 4
“You need to wait years for any forgiveness to work”
Reality: Some mechanisms work quickly — settlement typically 2-6 months from initial negotiation; bankruptcy Chapter 7 discharge in 3-4 months; motion to dismiss on standing grounds within court schedule (typically 6-18 months). Others depend on individual timelines — statute of limitations depends on state law (3-15 years); Chapter 13 involves 3-5 year plan; lender program applications typically 30-90 days for decision. The 20-25 year IDR forgiveness timeline applies only to federal loans, not private loans. Real private loan forgiveness can produce results much faster.
Frequently asked questions
1. Is there real debt forgiveness for private student loans?
Yes, real debt forgiveness for private student loans exists through six legally-established mechanisms: (1) settlement — negotiated reduced payment in full satisfaction, forgiving the balance above payment; (2) bankruptcy discharge under 11 U.S.C. §523(a)(8) with Homaidan v. Sallie Mae Second Circuit precedent for non-qualified loans; (3) statute of limitations expiration making debt uncollectible under state law; (4) chain of assignment defense on Article III standing grounds achieving case dismissal; (5) lender hardship programs modifying debt terms; (6) death and disability discharge offered by most private lenders. What is NOT available is federal-style forgiveness (PSLF, IDR) which applies only to federal loans.
2. What is the difference between debt forgiveness and settlement?
Settlement IS a form of debt forgiveness — specifically, forgiveness of the balance above the settlement payment. If you owe $50,000 and settle for $20,000, then $30,000 of debt is legally forgiven, reported on Form 1099-C, and cannot be collected further. “Debt forgiveness” is the broader concept covering multiple mechanisms including settlement, bankruptcy discharge, statute of limitations, chain of assignment dismissal, hardship modification, and death/disability discharge. Settlement is one of the most accessible forgiveness mechanisms for most borrowers, particularly for charged-off or debt-buyer-held accounts.
3. Can private student loans be completely forgiven?
Yes, complete forgiveness is achievable through: (1) bankruptcy discharge under §523(a)(8) with Homaidan precedent for qualifying non-qualified loans; (2) chain of assignment challenge succeeding in dismissal when creditor cannot demonstrate standing; (3) death or Total and Permanent Disability discharge from most private lenders; (4) statute of limitations expiration making debt legally uncollectible through litigation; (5) Ascent college loans originated June 5, 2023+ with contractual §523(a)(8) discharge waiver. Settlement typically achieves partial forgiveness (40-70% discount) rather than complete elimination. Complete forgiveness depends on specific circumstances and mechanism selection.
4. How do I get private loan forgiveness that actually works?
Steps to real private student loan debt forgiveness: (1) confirm loans are private (not federal) via studentaid.gov NSLDS check; (2) identify current holder and servicer for each loan; (3) evaluate loan status (current, delinquent, charged-off, in litigation); (4) analyze which of the six mechanisms apply — settlement for delinquent/charged-off, bankruptcy under Homaidan for qualifying loans, SOL for old debt, chain of assignment for NCSLT/debt buyer debt, hardship programs for specific situations, discharge for death/disability; (5) work with attorney or specialist to develop coordinated multi-mechanism strategy; (6) execute the plan through appropriate legal or negotiation processes. Professional guidance produces materially better outcomes than DIY approaches.
5. Will I owe taxes on debt forgiveness for private student loans?
Cancellation of debt of $600 or more is reported by the creditor on Form 1099-C and is generally taxable income in the year of cancellation. However, IRC §108 provides significant exclusions: Insolvency exclusion (IRC §108(a)(1)(B)) excludes cancelled debt to extent borrower was insolvent (liabilities exceeded assets) immediately before cancellation. Many borrowers pursuing forgiveness qualify because financial distress often means insolvency. Bankruptcy exclusion (IRC §108(a)(1)(A)) excludes debt cancelled in Chapter 7/13 bankruptcy entirely. Working with CPA experienced in debt cancellation for §108 analysis before finalizing forgiveness can eliminate or significantly reduce tax liability on forgiven amounts.
6. How long does debt forgiveness for private student loans take?
Timelines vary by mechanism: settlement typically 2-6 months from initial negotiation to completion; bankruptcy Chapter 7 typically 3-4 months from filing to discharge order (plus 60-90 days for §523(a)(8) adversary proceeding if needed); Chapter 13 typically 3-5 years to plan completion; chain of assignment challenges typically 6-18 months for motion practice; statute of limitations timing depends on state law (3-15 years from default); lender program applications typically 30-90 days for decision. Combined multi-mechanism strategy timelines depend on which mechanisms are pursued in what sequence. Realistic expectations are essential — legitimate work takes time proportional to mechanism complexity.
7. What loan forgiveness for private loans is available in 2026?
In 2026, loan forgiveness for private loans is available through the six mechanisms in this guide, all of which continue to function under current law. Recent developments enhancing accessibility include: continued application of Homaidan v. Sallie Mae Second Circuit precedent (992 F.3d 100, 2d Cir. 2021) for non-qualified loan discharge; Third Circuit’s March 19, 2024 NCSLT decision and December 2024 SCOTUS cert denial supporting chain of assignment challenges; DOJ November 2022 guidance moderating Brunner test application; Consumer Credit Fairness Act (CCFA) April 2022 reducing New York SOL to 3 years; Ascent college loans June 5, 2023+ with contractual discharge waiver. The framework of what works remains stable while precedent continues favoring borrowers.
Need Real Debt Forgiveness for Your Private Student Loans?
Free specialist review of what actually works for your situation.
Settlement negotiation analysis with your specific lender or debt buyer, bankruptcy discharge evaluation under Homaidan §523(a)(8) precedent, statute of limitations analysis by your state, chain of assignment defensive framework for NCSLT or debt buyer portfolios, lender-specific hardship program qualification, and coordinated multi-mechanism strategy for maximum debt forgiveness for private student loans outcomes. Free eligibility review with attorney-backed partner provider — no upfront fees.
Get a free eligibility review →
5-minute review · No obligation · Zero upfront fees · Since 2015 · 48 states served
About the author
Henry Silva — Private Student Loan Debt Specialist
10+ years experience across the complete six-mechanism framework for real debt forgiveness for private student loans: settlement negotiation with major private lenders (Sallie Mae Bank NYSE:SLM, Navient/Earnest Operations LLC, Discover/Firstmark Services after July 2024 Carlyle+KKR sale, SoFi Bank NA NMLS #696891, Citizens Bank NA NYSE:CFG, Ascent Student Loans), bankruptcy discharge analysis under 11 U.S.C. §523(a)(8) with Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) precedent, Crocker v. Navient 941 F.3d 206 (5th Cir. 2019), McDaniel v. Navient 973 F.3d 1083 (10th Cir. 2020), Brunner v. New York State Higher Education Services Corp. 831 F.2d 395 (2d Cir. 1987) framework, In re Rosenberg 594 B.R. 22 (Bankr. S.D.N.Y. 2020) updated application, statute of limitations analysis across all 50 states, hardship program qualification, cosigner release strategy, chain of assignment challenges under Article III standing doctrine (Lujan/Spokeo/TransUnion), NCSLT Third Circuit precedent application (March 19, 2024 covered persons decision, December 2024 SCOTUS cert denial), IRC §108(a)(1)(A) bankruptcy and IRC §108(a)(1)(B) insolvency tax exclusion analysis, and coordinated multi-mechanism strategy for maximum debt forgiveness for private student loans outcomes. Henry works with Private Student Relief’s attorney-backed partner provider network to review individual scenarios across all six forgiveness mechanisms.
Legal Disclaimer and Sources
This article is provided for informational purposes only and does not constitute legal, tax, or financial advice. Private Student Relief is a consulting and matching organization operated by Joco (555 Anton Blvd, Suite 368, Costa Mesa, CA 92626) — not a law firm, debt settlement company, debt consolidation company, or loan provider. Debt validation services are performed by an attorney-backed partner provider (Panamerican Consulting LLC, Las Vegas, NV) under independent business credentials. Ratings, BBB accreditation, and AADR membership referenced on the PSR website belong to the partner provider. Debt forgiveness pathway availability depends on loan characteristics, lender terms, borrower circumstances, and jurisdiction. Individual results vary. Since 2015. 48 states served. Not available in South Carolina or Mississippi.
Federal student loan program citations: Higher Education Act (20 U.S.C. §1001 et seq.); Public Service Loan Forgiveness (20 U.S.C. §1087e(m)); Income-Driven Repayment forgiveness (federal loan regulatory framework); Direct Loan death discharge (20 U.S.C. §1087); Perkins Loan death discharge (20 U.S.C. §1087dd). These federal programs apply ONLY to federal loans and do NOT apply to private student loans.
Bankruptcy Code references: 11 U.S.C. §523(a)(8) (student loan discharge exceptions with §523(a)(8)(A)(i) governmental unit, §523(a)(8)(A)(ii) educational benefit, §523(a)(8)(B) qualified education loan categories); 11 U.S.C. §362 (automatic stay); 11 U.S.C. §707(b)(2) (means test); 11 U.S.C. §1328 (Chapter 13 discharge). Key bankruptcy precedent: Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) — Sallie Mae direct-to-consumer loans dischargeable without undue hardship; Brunner v. New York State Higher Education Services Corp. 831 F.2d 395 (2d Cir. 1987) — undue hardship test; Crocker v. Navient Solutions LLC 941 F.3d 206 (5th Cir. 2019); McDaniel v. Navient Solutions LLC 973 F.3d 1083 (10th Cir. 2020); In re Rosenberg 594 B.R. 22 (Bankr. S.D.N.Y. 2020). Article III standing precedent: Lujan v. Defenders of Wildlife 504 U.S. 555 (1992); Spokeo, Inc. v. Robins 578 U.S. 330 (2016); TransUnion LLC v. Ramirez 594 U.S. 413 (2021). Federal Rules of Civil Procedure: FRCP 60(b)(4) (void judgment). Internal Revenue Code: IRC §221(d)(1) (qualified education loan definition); IRC §108(a)(1)(A) (bankruptcy exclusion); IRC §108(a)(1)(B) (insolvency exclusion). FDCPA: 15 U.S.C. §1692e (deceptive practices); 15 U.S.C. §1692g (debt validation).
Statute of limitations for written contract debt (private student loans) by state: Texas 4 years under Tex. Civ. Prac. & Rem. Code §16.004(a)(3); New York 3 years under CPLR §214(2) per Consumer Credit Fairness Act (CCFA) effective April 7, 2022; Pennsylvania 4 years under 42 Pa.C.S. §5525; Ohio 6 years under Ohio R.C. §2305.06 (reduced 2021); Illinois 10 years under 735 ILCS 5/13-206; Georgia 6 years under O.C.G.A. §9-3-24; California 4 years under CCP §337; Florida 5 years under Fla. Stat. §95.11(2)(b); Delaware 3 years under 10 Del. C. §8106. Complete state SOL analysis should be verified against current statutes for each specific borrower situation.
Lender information current as of September 2026 per publicly available documentation: Sallie Mae Bank NYSE:SLM; Navient/Earnest Operations LLC (subsidiary since 2017); Discover student loans acquired by Carlyle Group and KKR July 2024 with servicing transitioned to Firstmark Services (Nelnet NYSE:NNI subsidiary); SoFi Bank NA NMLS #696891 (chartered as national bank 2022); Citizens Bank NA NYSE:CFG; Ascent Student Loans with June 5, 2023 originated loans having contractual §523(a)(8) discharge waiver. Specific lender program details, cosigner release requirements, hardship programs, and death/disability discharge policies subject to change and should be verified directly with current lender documentation.
Debt forgiveness strategy for private student loans requires case-by-case analysis coordinating loan characteristics, lender identification, chain of assignment history, borrower jurisdiction, defensive framework opportunities, and specific circumstances. This article provides general framework information; specific settlement negotiations, bankruptcy filings under Homaidan precedent, chain of assignment challenges, hardship program applications, cosigner release strategies, death/disability discharge applications, and coordinated multi-mechanism approaches must be evaluated for each borrower’s individual situation by counsel or consulting resources familiar with the complete debt forgiveness for private student loans framework. Last reviewed: September 2026.