

Informational content only. Not legal, tax, or financial advice. Private Student Relief is a consulting organization, not a law firm. Debt validation services are executed by an attorney-backed partner provider. Sallie Mae student loan relief options depend on loan characteristics, current holder or servicer, borrower circumstances, and jurisdiction. Sallie Mae Bank is a subsidiary of SLM Corporation (NYSE:SLM). Last reviewed: September 2026.
Written by Henry Silva
Private Student Loan Debt Specialist · 10+ years experience delivering real sallie mae student loan relief: Sallie Mae Bank (SLM Corporation NYSE:SLM) settlement negotiation, Sallie Mae Loan Modification Program qualification, Rate Reduction Program, Interest-Only Payment Program, hardship forbearance, cosigner release program (12 consecutive on-time P&I payments), bankruptcy discharge under Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) precedent, NCSLT chain of assignment challenges for pre-2014 Sallie Mae loans, statute of limitations analysis, and coordinated multi-path sallie mae loan relief strategy. Last reviewed: September 2026.
If you’re struggling with Sallie Mae student loans and searching for real sallie mae student loan relief, you’re in the right place. Sallie Mae Bank (SLM Corporation NYSE:SLM) is the largest originator of private student loans in the United States — but that doesn’t mean you’re stuck. This complete guide walks through every legitimate sallie mae loan relief option available in 2026: Sallie Mae’s own hardship programs (Loan Modification, Rate Reduction, Interest-Only Payment, Hardship Forbearance), cosigner release program, death and disability discharge, PLUS external relief mechanisms that eliminate or reduce Sallie Mae debt — settlement negotiation, bankruptcy discharge under the game-changing Homaidan v. Sallie Mae Second Circuit precedent, statute of limitations expiration, and chain of assignment defense particularly powerful for older Sallie Mae loans securitized into NCSLT trusts. Federal forgiveness programs (PSLF, IDR) do NOT apply to Sallie Mae loans, but the 6 real relief paths in this guide DO.
Quick Answer
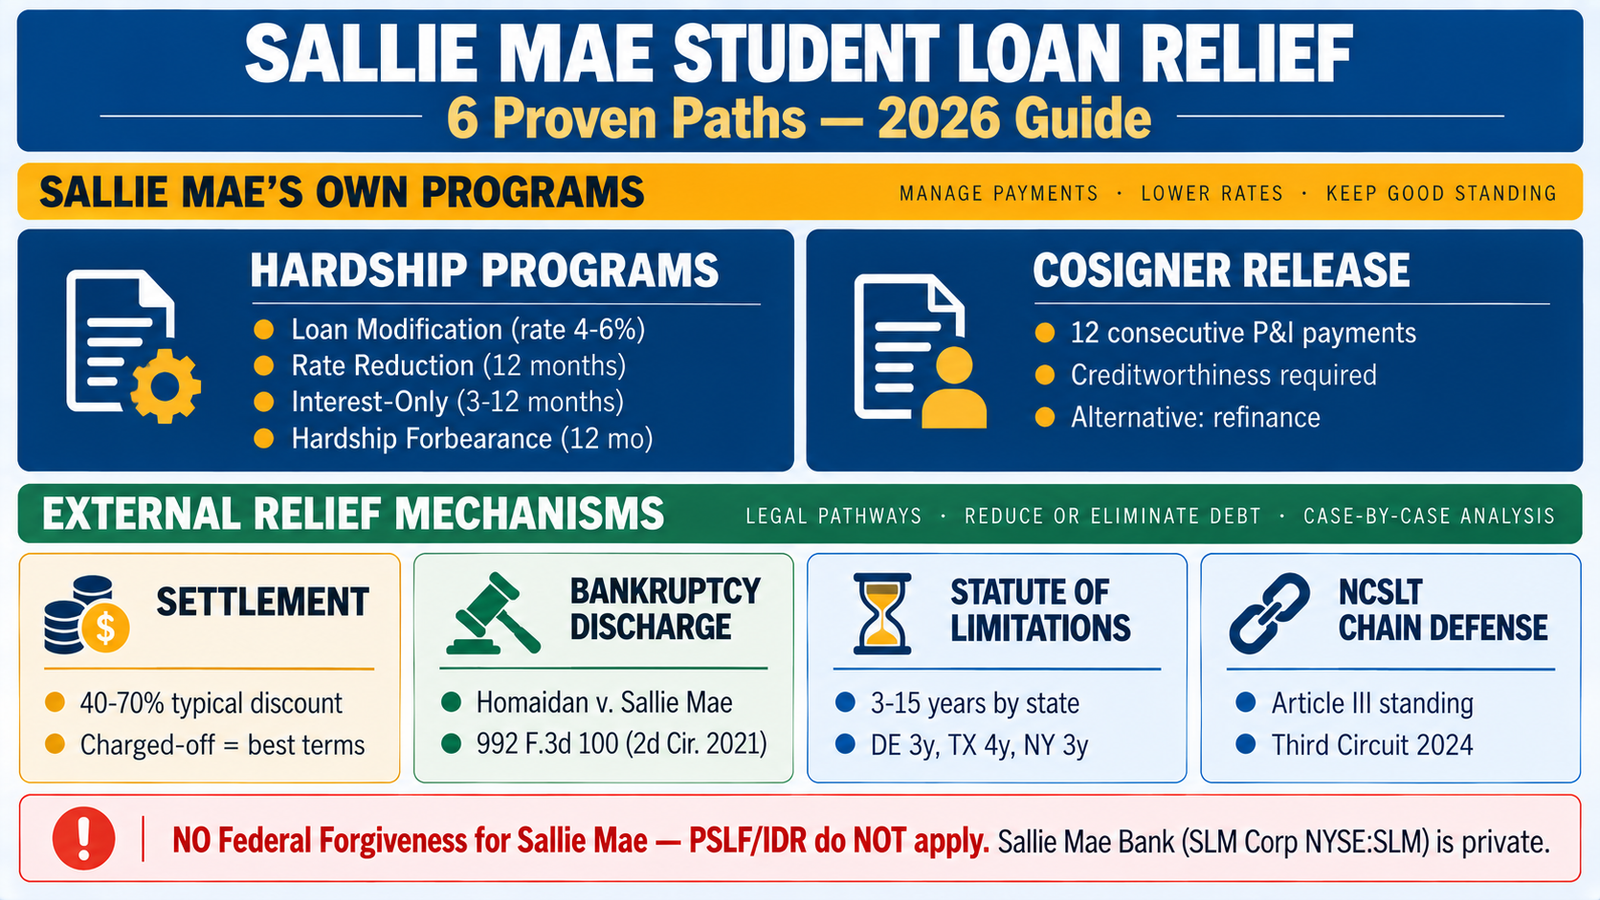
Sallie Mae student loan relief is achieved through six real paths (federal programs like PSLF/IDR do NOT apply to Sallie Mae private loans): (1) Sallie Mae’s own hardship programs — Loan Modification Program with reduced interest rates and payments, Rate Reduction Program for shorter-term relief, Interest-Only Payment Program for 3-12 months, Hardship Forbearance up to 12 months cumulative; (2) Sallie Mae cosigner release program after 12 consecutive on-time principal-and-interest payments plus creditworthiness demonstration; (3) settlement negotiation with Sallie Mae Bank or current holder for less than full balance, often 40-70% discount for delinquent or charged-off accounts; (4) bankruptcy discharge under 11 U.S.C. §523(a)(8) with Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) Second Circuit precedent — Sallie Mae direct-to-consumer loans dischargeable without undue hardship showing; (5) statute of limitations expiration under state law (3-15 years by state) making time-barred debt uncollectible; (6) chain of assignment defense on Article III standing grounds particularly for pre-2014 Sallie Mae loans securitized into NCSLT. Plus death and disability discharge for qualifying situations.
Read the complete framework below.
In this complete Sallie Mae relief guide:
Understanding Sallie Mae relief in 2026 — landscape
SLM Corporation today, 2014 Navient split, current portfolio holders
Path 1: Sallie Mae’s own hardship programs
Loan Modification, Rate Reduction, Interest-Only, Hardship Forbearance
Path 2: Sallie Mae cosigner release program
12-payment threshold, creditworthiness criteria, refinance alternative
Path 3: Settlement negotiation with Sallie Mae
Realistic outcomes by status, timing, documentation, tax planning
Path 4: Bankruptcy discharge — Homaidan precedent for Sallie Mae
The Second Circuit case, direct-to-consumer loans, adversary proceeding
Path 5: Statute of limitations analysis for Sallie Mae debt
State SOL, choice of law, revival concerns, defensive application
Path 6: NCSLT chain of assignment defense
Article III standing challenges for pre-2014 Sallie Mae loans in NCSLT
Choosing your Sallie Mae relief strategy
Decision framework by loan status, combining paths, professional resources
Understanding Sallie Mae relief in 2026 — the landscape
Before diving into specific sallie mae student loan relief paths, understanding the current Sallie Mae landscape is essential. Sallie Mae is not a monolith — the corporate structure and portfolio distribution directly affect which relief paths apply to your specific loan.
SLM Corporation today and the 2014 Navient split
SLM Corporation (originally Student Loan Marketing Association, established 1972 as government-sponsored enterprise, fully privatized 2004) split into two companies in April 2014: Sallie Mae Bank (SLM Corporation NYSE:SLM, headquartered Newark, Delaware) — kept the Sallie Mae name and continued private student loan origination; Navient Corporation (NYSE:NAVI) — spun off with federal loan servicing and legacy private loan portfolio. Navient’s private loan business now largely operated through Earnest Operations LLC (subsidiary since 2017). This split matters critically for relief analysis: loans originated after 2014 are typically still with Sallie Mae Bank directly; loans originated before 2014 may be with Navient/Earnest, in securitized trusts (NCSLT), or with debt buyers.
Identifying your Sallie Mae holder
The first step in any sallie mae loan relief strategy is identifying who currently holds and services your loan. Sources: (1) most recent loan statement names holder and servicer; (2) credit reports from Experian, Equifax, TransUnion show current furnisher; (3) prior collection letters identify collector (may not be current holder); (4) court filings if lawsuit exists — plaintiff is party claiming ownership; (5) formal debt validation request under FDCPA 15 U.S.C. §1692g requires complete debt documentation. This identification determines which specific relief paths apply.
The NCSLT connection
Many pre-2014 Sallie Mae-originated loans, particularly from 2001-2007, were pooled into National Collegiate Student Loan Trusts (NCSLT). NCSLT holdings have been the subject of extensive litigation regarding chain of assignment defects, standing challenges, and enforcement practices. Third Circuit’s March 19, 2024 decision establishing “covered persons” analysis and subsequent SCOTUS cert denial December 2024 created substantial precedent supporting borrower defensive framework. If your “Sallie Mae debt” is now held by NCSLT (evident from plaintiff name in any collection lawsuit or current furnisher in credit reporting), Path 6 becomes particularly powerful.
Path 1: Sallie Mae’s own hardship programs
Sallie Mae Bank offers several formal hardship programs that provide meaningful sallie mae student loan relief for qualifying borrowers experiencing financial difficulty. While these programs are not “forgiveness” in the strictest sense, they can reduce overall debt cost, prevent charge-off, and support longer-term relief strategy. Understanding Sallie Mae’s program details is essential to accessing available relief.
Sallie Mae Loan Modification Program
The Sallie Mae Loan Modification Program (LMP) offers reduced interest rates and temporarily reduced payments for qualifying borrowers demonstrating hardship. Program elements typically include: reduced interest rate (often 4-6% depending on original rate and hardship documentation); reduced monthly payment for defined period (typically 12-36 months initially); capitalization of unpaid interest or restructuring of accrued charges; ongoing eligibility review at defined intervals. Application requires: hardship documentation (job loss, medical hardship, income reduction, family circumstances); current financial statement showing income, expenses, assets, liabilities; supporting documentation for hardship claim. The program is discretionary — Sallie Mae is not obligated to approve any specific application, and approval decisions are made case-by-case.
Sallie Mae Rate Reduction Program
The Sallie Mae Rate Reduction Program provides temporary interest rate reduction for shorter periods (typically 12 months) with less extensive hardship documentation than full Loan Modification. Rate reductions typically bring the rate down to 4-5% during the reduction period, then return to the original rate after the reduction period expires. Useful for borrowers experiencing temporary hardship rather than long-term financial distress. Can be renewed for additional periods with continued hardship demonstration in some cases.
Sallie Mae Interest-Only Payment Program
The Sallie Mae Interest-Only Payment Program allows borrowers to pay only accrued interest for a defined period (typically 3-12 months) rather than principal-and-interest amortized payments. This significantly reduces monthly payment amount during the interest-only period but does not reduce the principal balance. Useful for temporary cash flow relief during hardship. Extends overall repayment timeline because principal reduction pauses during the interest-only period. Program is subject to Sallie Mae’s discretionary approval and typically requires hardship demonstration.
Sallie Mae Hardship Forbearance
Sallie Mae Hardship Forbearance temporarily suspends required monthly payments for qualifying borrowers. Standard availability: up to 12 months cumulative over the life of the loan, in 3-month increments requiring reapplication and updated documentation. During forbearance, interest continues to accrue and capitalizes onto principal at the end of the forbearance period — meaning forbearance provides temporary payment relief but increases overall debt cost. Should be short-term bridge to more permanent solutions rather than long-term strategy.
Application coordination with broader strategy
Hardship program applications should coordinate with the broader relief framework: (1) hardship documentation may support later bankruptcy undue hardship showing if pursued; (2) hardship denial evidence supports later settlement discussions; (3) hardship approval provides breathing room to develop other defensive analysis; (4) forbearance can bridge to statute of limitations expiration in some cases. Uncoordinated hardship applications can inadvertently harm defensive framework — for example, written acknowledgments of debt during hardship application when SOL has already expired can revive time-barred debt in some jurisdictions.
Path 2: Sallie Mae cosigner release program
For cosigned Sallie Mae loans (which represent the majority of undergraduate Sallie Mae Smart Option Student Loans), cosigner release is a critical form of sallie mae loan forgiveness — the cosigner is legally released from continuing obligation, though the primary borrower remains liable. Sallie Mae offers one of the more accessible cosigner release programs among major private lenders.
Cosigner release eligibility criteria
Sallie Mae cosigner release requires meeting all of the following criteria: (1) 12 consecutive on-time principal-and-interest payments — payments must be full scheduled amount, must be on time (no more than late by Sallie Mae’s defined grace period); interest-only payments during in-school or grace period generally do NOT count; the 12 consecutive payments must be in standard repayment phase; (2) borrower creditworthiness demonstration — borrower must independently qualify based on current income, credit history, and debt-to-income ratio without cosigner support; (3) account in good standing — no delinquency, no forbearance during qualifying period, no modification of terms; (4) completion of any required education program — for loans still in in-school or grace status, program completion is typically required.
Application process
Cosigner release application through Sallie Mae involves: (1) confirming eligibility through Sallie Mae online account or customer service; (2) completing formal cosigner release application; (3) submitting supporting income documentation for borrower creditworthiness review; (4) Sallie Mae underwriting review typically 30-60 days; (5) approval or denial notification with reasons. If denied, borrower can typically reapply after 12 additional months of qualifying payments and improved financial situation. If approved, cosigner is legally released from further obligation.
Refinance to eliminate Sallie Mae cosigner
Refinance in the primary borrower’s name alone eliminates the Sallie Mae cosigner entirely. The Sallie Mae loan is paid in full through refinance proceeds, and the new loan (with a different lender or Sallie Mae’s own refinance product) is issued to the borrower alone. Refinance requirements typically include: adequate borrower income for independent qualification; acceptable credit profile (typically 680+ credit score); debt-to-income ratio within lender parameters. Refinance offers cosigner release regardless of whether the current Sallie Mae loan qualifies for the formal release program — useful for borrowers who cannot meet the 12-payment threshold or creditworthiness criteria.
Cosigner release through settlement or discharge
Settlement or bankruptcy discharge of the underlying Sallie Mae loan also effectively releases the cosigner because the underlying debt is eliminated. For cosigners primarily concerned with their own liability exposure, supporting the primary borrower’s pursuit of settlement or bankruptcy discharge under Homaidan analysis may be the most effective cosigner release path — particularly if the formal cosigner release program is not accessible due to payment history or creditworthiness issues.
Path 3: Settlement negotiation with Sallie Mae
Settlement negotiation is often the most accessible external sallie mae debt forgiveness path for borrowers with delinquent or charged-off Sallie Mae loans. Rather than paying the full amount owed, the borrower negotiates with Sallie Mae Bank (or the current holder if the loan has been sold) to pay a reduced lump sum in full satisfaction. Settlement produces immediate elimination of the debt above the settlement amount.
Sallie Mae’s settlement posture by loan status
Sallie Mae Bank’s willingness to settle varies significantly by loan status: Current or early delinquent — Sallie Mae typically pushes hardship programs rather than settlement, because the loan remains a performing asset; 90-180 days delinquent — settlement conversations become possible as the loan approaches charge-off; Charged-off status (180+ days delinquent) — Sallie Mae may retain internal collection or sell to third-party debt buyers, both stages present settlement opportunities; Sold to debt buyer — often the best settlement discounts because debt buyers purchased at pennies on the dollar; Pre-litigation — settlement typically preferred by both sides; Post-litigation or judgment — settlement still possible but from more constrained defensive position.
Realistic settlement outcomes
Realistic Sallie Mae settlement outcomes for charged-off accounts often achieve 40-60% discount from balance; debt-buyer accounts sometimes 30-50%; pre-charge-off delinquent accounts typically less favorable. Approaching settlement from position of defensive leverage (chain of assignment analysis if NCSLT-related, SOL status, credible bankruptcy alternative under Homaidan) typically produces materially better outcomes than passive settlement.
Documenting Sallie Mae settlement
Essential settlement agreement elements: (1) exact settlement amount and payment terms; (2) explicit “full satisfaction” release language stating the payment satisfies the entire debt including principal, accrued interest, late fees, collection costs; (3) tradeline update instructions specifying how Sallie Mae will report to Experian, Equifax, TransUnion following payment; (4) release of cosigner if the loan was cosigned; (5) any specific covenants regarding disparagement, non-solicitation, or confidentiality if applicable. Never make settlement payment without written settlement agreement signed by authorized Sallie Mae representative.
Tax implications — IRC §108 planning
Sallie Mae reports the forgiven portion of a settlement on Form 1099-C to the IRS as cancellation of debt income. IRC §108 exclusions provide significant tax relief opportunities: Insolvency exclusion (IRC §108(a)(1)(B)) — cancelled debt excluded to extent borrower was insolvent (liabilities exceeded assets) immediately before cancellation; many borrowers pursuing settlement qualify; Bankruptcy exclusion (IRC §108(a)(1)(A)) — debt cancelled in Chapter 7/13 bankruptcy is excluded entirely. Working with CPA experienced in debt cancellation for §108 analysis before finalizing settlement can eliminate or significantly reduce tax liability on forgiven amounts.
Path 4: Bankruptcy discharge — Homaidan precedent for Sallie Mae
Bankruptcy discharge is one of the most powerful — and most misunderstood — sallie mae student loan relief paths. The prevailing myth that “student loans can never be discharged” is outdated for Sallie Mae loans specifically, following the landmark Second Circuit precedent Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021). This is arguably the most important private student loan bankruptcy case of the last decade for Sallie Mae borrowers.
The §523(a)(8) framework applied to Sallie Mae loans
11 U.S.C. §523(a)(8) makes certain educational loans non-dischargeable in bankruptcy unless “undue hardship” is shown. Categories: §523(a)(8)(A)(i) — loans made, insured, or guaranteed by governmental unit (Sallie Mae private loans generally NOT in this category since 2010 when SLM’s federal FFEL business ended); §523(a)(8)(A)(ii) — “obligation to repay funds received as educational benefit, scholarship, or stipend” (Homaidan established this is narrow); §523(a)(8)(B) — “qualified education loan” as defined in IRC §221(d)(1). Sallie Mae loans NOT falling into any category are dischargeable in bankruptcy WITHOUT undue hardship showing.
The Homaidan case
Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) — the plaintiff Hilal Homaidan filed Chapter 7 bankruptcy that included his Sallie Mae direct-to-consumer loans. Homaidan later brought an adversary proceeding contending that the loans had been discharged in the Chapter 7 (because they were not §523(a)(8)-protected) and that Sallie Mae’s continued collection violated the discharge injunction. The Second Circuit affirmed the bankruptcy court’s ruling that Sallie Mae’s direct-to-consumer loans (made directly to students without school certification of the cost of attendance) do NOT qualify as “educational benefit” under §523(a)(8)(A)(ii) — meaning they are dischargeable without undue hardship showing. This precedent is binding in Second Circuit (NY, CT, VT) and highly persuasive in other circuits. Similar precedents in Fifth Circuit (Crocker 941 F.3d 206, 5th Cir. 2019) and Tenth Circuit (McDaniel 973 F.3d 1083, 10th Cir. 2020).
Which Sallie Mae loans qualify under Homaidan
Sallie Mae loans potentially dischargeable without undue hardship under Homaidan analysis: (1) direct-to-consumer loans without school certification of cost of attendance; (2) loans exceeding cost of attendance limit for enrollment period; (3) loans for non-title IV eligible programs (some vocational programs, bar prep courses, non-degree programs); (4) loans to students not enrolled at least half-time; (5) loans failing other IRC §221(d)(1) “qualified education loan” requirements. Case-by-case analysis of origination documents and disbursement records is required to determine Homaidan eligibility.
Qualified Sallie Mae loans and Brunner test
Sallie Mae loans qualifying under §523(a)(8) require undue hardship showing. Most circuits apply Brunner test from Brunner v. New York State Higher Education Services Corp. 831 F.2d 395 (2d Cir. 1987): (1) debtor cannot maintain minimal standard of living while repaying; (2) additional circumstances indicate this will persist for significant portion of repayment period; (3) debtor has made good faith efforts to repay. Recent case law (In re Rosenberg 594 B.R. 22, Bankr. S.D.N.Y. 2020) and DOJ guidance (November 2022) have moderated Brunner’s historically harsh application, making discharge more accessible for qualifying Sallie Mae loans.
Chapter 7 vs Chapter 13 selection
Chapter 7 provides discharge of most unsecured debts including Sallie Mae loans qualifying under Homaidan or with successful undue hardship showing in 3-4 months. Chapter 13 involves 3-5 year payment plan with discharge under 11 U.S.C. §1328 at plan completion. Chapter selection depends on: means test qualification (Chapter 7 requires income below state median or successful means test under 11 U.S.C. §707(b)(2)); asset preservation needs; whether payment plan restructuring benefits overall situation. Sallie Mae bankruptcy discharge requires bankruptcy counsel familiar with §523(a)(8) adversary proceeding practice.
Path 5: Statute of limitations analysis for Sallie Mae debt
SOL expiration provides passive but powerful sallie mae loan relief for older Sallie Mae debt. When state SOL expires, Sallie Mae or the current holder loses the legal ability to file a lawsuit to collect. Understanding SOL analysis for Sallie Mae debt requires identifying applicable state law, accrual date, and any factors that may have restarted or tolled the SOL clock.
Choice of law considerations
Sallie Mae loan promissory notes typically include choice-of-law provisions (often Delaware where Sallie Mae Bank is chartered). However, borrower’s state of residence and state where any lawsuit is filed also affect analysis under conflict-of-laws principles. Courts have reached varying conclusions on whether borrower state SOL or contract choice-of-law state SOL applies for Sallie Mae debt — the specific analysis depends on jurisdiction and facts.
SOL by common borrower states
SOL periods for written contract debt (Sallie Mae loans) by common borrower states: Texas 4 years under Tex. Civ. Prac. & Rem. Code §16.004(a)(3); New York 3 years under CPLR §214(2) per Consumer Credit Fairness Act (CCFA) effective April 7, 2022 (reduced from 6 years); Pennsylvania 4 years under 42 Pa.C.S. §5525; Ohio 6 years under Ohio R.C. §2305.06 (reduced from 8 years effective 2021); Illinois 10 years under 735 ILCS 5/13-206; Georgia 6 years under O.C.G.A. §9-3-24; California 4 years under CCP §337; Florida 5 years under Fla. Stat. §95.11(2)(b); Delaware 3 years under 10 Del. C. §8106 (relevant given Sallie Mae Bank’s Delaware charter). Accrual typically date of first default or last payment depending on state.
Revival concerns specific to Sallie Mae debt
Borrowers with older Sallie Mae debt should carefully avoid actions that could restart the SOL clock: making any payment on the debt (even small “goodwill” payments) may restart SOL; written acknowledgment of the debt (hardship applications, settlement offers, promise to pay) may create restart; new agreement resets timing. Sallie Mae collectors and debt buyers sometimes solicit small payments or written communications specifically to revive time-barred debt. Consulting counsel before communicating with Sallie Mae or its debt collectors on old debt prevents inadvertent revival.
Defensive application when SOL has expired
When SOL has expired on Sallie Mae debt: (1) debt still legally exists but cannot be enforced through litigation; (2) collection calls and letters can be disputed under FDCPA 15 U.S.C. §1692g if third-party collector involved; (3) if lawsuit is filed on time-barred debt, motion to dismiss based on SOL expiration typically succeeds and may support FDCPA counterclaim; (4) credit reporting continues under 7-year FCRA reporting period regardless of SOL; (5) settlement of time-barred debt should proceed carefully to avoid revival. SOL expiration effectively provides sallie mae student loan relief by making the debt uncollectible through litigation.
Related resources — complete Sallie Mae relief ecosystem
The 7-path master framework covering all private student loans including Sallie Mae and other lenders.
Sallie Mae Debt Forgiveness 2026: Real Options
Sister guide focused specifically on Sallie Mae forgiveness across all seven paths with Homaidan analysis.
Debt Forgiveness for Private Student Loans: What Works 2026
6-mechanism framework for real debt forgiveness including tax planning under IRC §108.
Path 6: NCSLT chain of assignment defense
Chain of assignment defense is particularly powerful for older Sallie Mae debt securitized into National Collegiate Student Loan Trusts (NCSLT). Article III standing requires the plaintiff to demonstrate complete chain of ownership from Sallie Mae as original lender through any intermediate holders to the current plaintiff. Defects provide grounds for dismissal — potentially achieving complete how to get sallie mae loans forgiven outcomes through legal proceedings.
Article III standing doctrine
Article III standing requires: (1) concrete and particularized injury; (2) causally connected to defendant’s conduct; (3) redressable by court decision. Established in Lujan v. Defenders of Wildlife 504 U.S. 555 (1992), refined in Spokeo, Inc. v. Robins 578 U.S. 330 (2016), and further developed in TransUnion LLC v. Ramirez 594 U.S. 413 (2021). For a plaintiff to sue on Sallie Mae debt, they must establish ownership through complete assignment documentation from Sallie Mae through any intermediate holders to themselves. Standing is jurisdictional and can be raised at any stage of proceedings, including post-judgment through motion to vacate under FRCP 60(b)(4).
NCSLT-specific analysis for Sallie Mae borrowers
Many pre-2014 Sallie Mae-originated loans (particularly 2001-2007) were pooled into NCSLT trusts. NCSLT litigation has developed extensive precedent for chain of assignment challenges. Key developments include the Third Circuit’s March 19, 2024 decision establishing “covered persons” analysis under the Consumer Financial Protection Act; SCOTUS cert denial in December 2024 leaving the Third Circuit precedent in place; various stipulated resolutions continuing through 2026. Borrowers with Sallie Mae debt held by NCSLT have documented pathways to challenge creditor standing, potentially achieving complete debt elimination through motion to dismiss or motion to vacate judgment on standing grounds.
Debt buyer chain analysis
Sallie Mae debt sold to third-party debt buyers after charge-off often has documentation gaps between original Sallie Mae ownership and current debt buyer’s asserted ownership. Common defects: missing intermediate assignment documentation showing continuous ownership chain; assignments executed without adequate documentation of the specific debts included in bulk sales; blank endorsements without allonge chain; discrepancies between Sallie Mae servicing records and asserted debt buyer ownership. Debt buyers typically purchase Sallie Mae portfolios at pennies on the dollar and may not have obtained complete assignment documentation for individual loans.
Post-judgment application
Because standing is jurisdictional, chain of assignment challenges are preserved even after judgment has been entered on Sallie Mae debt. Motion to vacate under FRCP 60(b)(4) (void judgment) can be filed at any time if the underlying judgment was entered without proper plaintiff standing. Particularly relevant for older default judgments where the borrower did not appear or contest at the time — the standing challenge remains available years or decades later. Recent Sallie Mae/NCSLT judgment vacation successes have established practical framework for this approach.
Sallie Mae death and disability discharge — bonus relief mechanisms
Beyond the six main paths, Sallie Mae Bank offers contract-based death and disability discharge programs for qualifying situations, providing another form of sallie mae student loans forgiven outcome through loan contract terms rather than statutory forgiveness.
Sallie Mae death discharge
Sallie Mae discharges the borrower’s remaining balance on death upon submission of required documentation (death certificate typically required within 60 days of death). For cosigned loans originated in 2015 or later, the cosigner is also released from further obligation upon borrower’s death — an important protection that many older cosigners on pre-2015 Sallie Mae loans do NOT have. Estate administrators should promptly notify Sallie Mae of borrower death with proper documentation to activate discharge processing. Families should not make payments on Sallie Mae loans of a deceased borrower before confirming the discharge has been processed.
Sallie Mae Total and Permanent Disability discharge
Sallie Mae offers Total and Permanent Disability (TPD) discharge for qualifying borrowers who become permanently disabled and unable to work. Documentation requirements typically include: physician certification of permanent disability meeting Sallie Mae’s specific criteria (which may or may not exactly match federal TPD standards); medical records supporting the disability determination; income and employment status verification. Sallie Mae’s TPD program is discretionary and requires case-by-case evaluation — borrowers denied on initial application can appeal with additional documentation.
Choosing your Sallie Mae relief strategy
Decision framework by loan status
The right sallie mae student loan relief path depends on specific circumstances: Current but struggling — Sallie Mae Loan Modification, Rate Reduction, or Interest-Only Payment Program; evaluate cosigner release if 12 payments completed; potential refinance; Recently delinquent (30-90 days) — Hardship Forbearance to prevent charge-off, then evaluate longer-term options; Charged-off Sallie Mae debt (180+ days) — settlement negotiation typically most cost-effective, chain of assignment analysis if held by NCSLT or debt buyer, SOL analysis; Lawsuit filed by Sallie Mae or successor — motion to dismiss on standing (chain of assignment), SOL defense if time-barred, settlement from defensive position, bankruptcy analysis; Judgment entered on Sallie Mae debt — motion to vacate on standing grounds preserved under FRCP 60(b)(4), settlement negotiation; Long-standing Sallie Mae debt near or past SOL — careful SOL analysis, avoid revival, potential settlement with time-barred debt awareness; Serious financial distress — bankruptcy analysis including Homaidan §523(a)(8) framework; Death or permanent disability — Sallie Mae discharge application.
Combining multiple Sallie Mae relief paths
Effective Sallie Mae relief often combines multiple paths: chain of assignment analysis creating settlement leverage if NCSLT-held; SOL analysis creating urgency for settlement; bankruptcy analysis under Homaidan as credible alternative supporting settlement negotiation; hardship program buying time to evaluate longer-term options; cosigner release combined with refinance analysis. Best how to get sallie mae loans forgiven outcome often emerges from coordinated multi-path strategy rather than pursuing any single path in isolation.
Professional resources
Given the complexity of the six paths and Sallie Mae-specific considerations, working with professional resources typically produces better outcomes than DIY approaches. Options: bankruptcy counsel familiar with Homaidan precedent application for §523(a)(8) analysis; state-licensed attorneys for chain of assignment challenges (particularly NCSLT-related); consulting firms with Sallie Mae portfolio experience for settlement negotiation; CPAs for §108 tax analysis around settlement forgiveness. Private Student Relief’s attorney-backed partner provider network coordinates these resources for comprehensive sallie mae loan relief analysis.
Common Sallie Mae student loan relief myths
Myth 1
“Sallie Mae qualifies for PSLF, IDR, or federal relief programs”
Reality: Sallie Mae Bank (NYSE:SLM) is a private lender. Federal programs — Public Service Loan Forgiveness (PSLF), Income-Driven Repayment (IDR) forgiveness, Teacher Loan Forgiveness, and executive-action forgiveness — apply ONLY to federal loans. Sallie Mae private loans are NEVER eligible for federal forgiveness. Real sallie mae student loan relief works through Sallie Mae’s own programs plus external mechanisms (settlement, bankruptcy discharge under Homaidan, SOL, chain of assignment) — all covered in this guide.
Myth 2
“Sallie Mae’s hardship programs are the only relief available”
Reality: Sallie Mae’s own hardship programs (Loan Modification, Rate Reduction, Interest-Only, Hardship Forbearance) are ONE path among six. External relief mechanisms often produce better long-term outcomes: settlement can achieve 40-70% debt elimination; bankruptcy discharge under Homaidan can eliminate the debt entirely; SOL expiration makes debt uncollectible; chain of assignment defense can dismiss cases entirely for NCSLT-held debt. Sallie Mae hardship programs are useful but not the only option — the full framework provides more powerful outcomes.
Myth 3
“Sallie Mae loans cannot be discharged in bankruptcy”
Reality: Many Sallie Mae loans ARE dischargeable in bankruptcy following Homaidan v. Sallie Mae Second Circuit precedent (992 F.3d 100, 2d Cir. 2021). Sallie Mae direct-to-consumer loans (without school certification of cost of attendance) are dischargeable without undue hardship showing. Sallie Mae loans qualifying under §523(a)(8) require undue hardship showing through Brunner test — accessible but requires adversary proceeding. The outdated myth is not accurate for many Sallie Mae loans, particularly the direct-to-consumer variety that was the subject of the actual Homaidan case.
Myth 4
“Sallie Mae won’t settle for less than the full balance”
Reality: Sallie Mae Bank and successors do settle Sallie Mae debt for less than full balance, particularly for charged-off accounts or accounts sold to debt buyers. Settlement outcomes depend on loan status, defensive framework strength, and negotiation approach. Approaching Sallie Mae settlement from position of defensive leverage (chain of assignment analysis, SOL status, bankruptcy alternative under Homaidan) typically produces materially better results than passive settlement. Settlement is one of the most accessible sallie mae loan relief mechanisms.
Frequently asked questions about Sallie Mae relief
1. What Sallie Mae student loan relief options are available?
Sallie Mae student loan relief options include: (1) Sallie Mae’s own hardship programs — Loan Modification Program (reduced interest rates and payments), Rate Reduction Program (12-month rate reduction), Interest-Only Payment Program (3-12 months), Hardship Forbearance (up to 12 months cumulative); (2) Sallie Mae cosigner release program (12 consecutive on-time principal-and-interest payments plus creditworthiness); (3) settlement negotiation with Sallie Mae or current holder for less than full balance; (4) bankruptcy discharge under 11 U.S.C. §523(a)(8) with Homaidan precedent; (5) statute of limitations expiration under state law; (6) chain of assignment defense for NCSLT-held debt; plus death and disability discharge for qualifying situations.
2. Does Sallie Mae offer any loan relief programs?
Yes, Sallie Mae Bank (SLM Corporation NYSE:SLM) offers several formal hardship programs: Loan Modification Program with reduced interest rates (often 4-6%) and reduced payments for qualifying hardship; Rate Reduction Program for temporary shorter-term rate reduction; Interest-Only Payment Program allowing interest-only payments for 3-12 months; Hardship Forbearance up to 12 months cumulative. Plus cosigner release program after 12 consecutive on-time principal-and-interest payments plus creditworthiness. Plus death discharge and Total and Permanent Disability discharge. All programs are discretionary requiring case-by-case Sallie Mae approval.
3. How do I qualify for Sallie Mae loan modification?
Sallie Mae Loan Modification Program qualification typically requires: (1) documentation of hardship circumstances (job loss, medical hardship, income reduction, family circumstances); (2) current financial statement showing income, expenses, assets, liabilities; (3) supporting documentation for hardship claim; (4) demonstrated inability to maintain current payment schedule; (5) willingness to make modified payments under the program terms. Application through Sallie Mae online account or customer service. Sallie Mae underwriting review typically 30-90 days. Approval is discretionary — Sallie Mae is not obligated to approve any specific application. If denied, borrowers can typically reapply with additional documentation or after material change in circumstances.
4. How do I get Sallie Mae loans forgiven completely?
Complete how to get sallie mae loans forgiven paths: (1) bankruptcy discharge under §523(a)(8) with Homaidan v. Sallie Mae precedent — direct-to-consumer loans dischargeable without undue hardship, other qualifying loans require Brunner test showing; (2) chain of assignment challenge succeeding in dismissal when creditor cannot demonstrate standing (particularly for NCSLT-held loans); (3) death or Total and Permanent Disability discharge from Sallie Mae; (4) statute of limitations expiration making debt legally uncollectible through litigation. Settlement typically achieves partial forgiveness (40-70% discount). Complete forgiveness depends on specific circumstances and mechanism selection — professional evaluation identifies best path.
5. Can I settle my Sallie Mae debt for less than I owe?
Yes, Sallie Mae debt settlement for less than balance is achievable, particularly for charged-off accounts or accounts sold to debt buyers. Realistic outcomes: charged-off accounts often 40-60% discount from balance; debt-buyer accounts sometimes 30-50%; pre-charge-off delinquent accounts less favorable. Settlement documented in written agreement including full satisfaction release language, tradeline update instructions to credit bureaus, cosigner release for cosigned loans, and any other required terms. Approach settlement from position of defensive leverage (chain of assignment analysis, SOL status, bankruptcy alternative) for better outcomes. IRC §108 tax planning is essential before finalizing settlement.
6. What is the Sallie Mae cosigner release program?
Sallie Mae’s cosigner release program releases the cosigner from further obligation on a Sallie Mae Smart Option Student Loan after all criteria met: (1) 12 consecutive on-time principal-and-interest payments (interest-only payments in in-school or grace period don’t count; payments must be full scheduled amount and on time within Sallie Mae’s grace period); (2) borrower independently demonstrates creditworthiness based on current income, credit history, and debt-to-income ratio; (3) account in good standing with no delinquency or forbearance during qualifying period. Application through Sallie Mae online account, underwriting review typically 30-60 days. If denied, borrower can reapply after 12 additional months. Alternative: refinance in borrower’s name only eliminates cosigner regardless of program eligibility.
7. Are there Sallie Mae relief programs for unemployment or job loss?
Sallie Mae offers Hardship Forbearance for borrowers experiencing unemployment or income reduction, providing temporary payment suspension. Availability typically up to 12 months cumulative over life of loan, in 3-month increments with reapplication and documentation each period. Interest continues to accrue during forbearance and capitalizes at end of forbearance period. For longer-term unemployment or job loss, Loan Modification Program may provide more sustainable relief through reduced interest rates and payments. Documentation of unemployment (unemployment benefit statements, job search records, prior employer verification) supports both hardship applications and any subsequent bankruptcy undue hardship showing.
Need Sallie Mae Student Loan Relief Now?
Free specialist review of all your Sallie Mae relief options.
Sallie Mae Loan Modification qualification analysis, cosigner release strategy, settlement negotiation with Sallie Mae Bank or current holder, bankruptcy discharge evaluation under Homaidan §523(a)(8) precedent, statute of limitations analysis by your state, chain of assignment defensive framework for NCSLT-related Sallie Mae debt, and coordinated approach across all six paths to sallie mae student loan relief. Free eligibility review with attorney-backed partner provider — no upfront fees.
Get a free eligibility review →
5-minute review · No obligation · Zero upfront fees · Since 2015 · 48 states served
About the author
Henry Silva — Private Student Loan Debt Specialist
10+ years experience specifically with Sallie Mae portfolios including Sallie Mae Bank (SLM Corporation NYSE:SLM) direct settlement negotiation, Sallie Mae Loan Modification Program qualification, Rate Reduction Program, Interest-Only Payment Program, Hardship Forbearance, cosigner release program (12 consecutive on-time principal-and-interest payments plus creditworthiness criteria), Navient/Earnest Operations LLC portfolio analysis for pre-2014 Sallie Mae loans (Navient subsidiary since 2017 acquisition), NCSLT (National Collegiate Student Loan Trust) chain of assignment challenges for securitized Sallie Mae-originated loans, Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) bankruptcy discharge precedent application, Brunner v. New York State Higher Education Services Corp. 831 F.2d 395 (2d Cir. 1987) undue hardship analysis for qualifying Sallie Mae loans, statute of limitations analysis across all 50 states, IRC §108 tax analysis for settlement forgiveness, and coordinated multi-path sallie mae student loan relief strategy. Henry works with Private Student Relief’s attorney-backed partner provider network to review individual Sallie Mae relief scenarios.
Legal Disclaimer and Sources
This article is provided for informational purposes only and does not constitute legal, tax, or financial advice. Private Student Relief is a consulting and matching organization operated by Joco (555 Anton Blvd, Suite 368, Costa Mesa, CA 92626) — not a law firm, debt settlement company, debt consolidation company, or loan provider. Debt validation services are performed by an attorney-backed partner provider (Panamerican Consulting LLC, Las Vegas, NV) under independent business credentials. Ratings, BBB accreditation, and AADR membership referenced on the PSR website belong to the partner provider. Sallie Mae student loan relief pathway availability depends on loan characteristics, current holder or servicer, borrower circumstances, and jurisdiction. Individual results vary. Since 2015. 48 states served. Not available in South Carolina or Mississippi.
Corporate references: SLM Corporation (NYSE:SLM), headquartered Newark, Delaware — the parent of Sallie Mae Bank. April 2014 corporate split separating Sallie Mae Bank (private student loan origination) from Navient Corporation (NYSE:NAVI) which took federal loan servicing business. Navient’s private loan business now largely operated through Earnest Operations LLC (subsidiary since 2017 acquisition). National Collegiate Student Loan Trusts (NCSLT) hold substantial portfolios of pre-2014 Sallie Mae-originated loans, particularly from 2001-2007.
Federal student loan program citations (for comparison, these do NOT apply to Sallie Mae private loans): Higher Education Act (20 U.S.C. §1001 et seq.); Public Service Loan Forgiveness (20 U.S.C. §1087e(m)); Income-Driven Repayment forgiveness (federal loan regulatory framework); Direct Loan death discharge (20 U.S.C. §1087); Perkins Loan death discharge (20 U.S.C. §1087dd). These federal programs apply ONLY to federal loans.
Bankruptcy Code references: 11 U.S.C. §523(a)(8) (student loan discharge exceptions with §523(a)(8)(A)(i) governmental unit, §523(a)(8)(A)(ii) educational benefit, §523(a)(8)(B) qualified education loan categories); 11 U.S.C. §362 (automatic stay); 11 U.S.C. §707(b)(2) (means test); 11 U.S.C. §1328 (Chapter 13 discharge). Key precedent: Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) — Sallie Mae direct-to-consumer loans dischargeable without undue hardship; Brunner v. New York State Higher Education Services Corp. 831 F.2d 395 (2d Cir. 1987) — undue hardship test; In re Rosenberg 594 B.R. 22 (Bankr. S.D.N.Y. 2020) — updated Brunner application; McDaniel v. Navient Solutions LLC 973 F.3d 1083 (10th Cir. 2020); Crocker v. Navient Solutions LLC 941 F.3d 206 (5th Cir. 2019). Article III standing precedent: Lujan v. Defenders of Wildlife 504 U.S. 555 (1992); Spokeo, Inc. v. Robins 578 U.S. 330 (2016); TransUnion LLC v. Ramirez 594 U.S. 413 (2021). Federal Rules of Civil Procedure: FRCP 60(b)(4) (void judgment). Internal Revenue Code: IRC §221(d)(1) (qualified education loan definition); IRC §108(a)(1)(A) (bankruptcy exclusion); IRC §108(a)(1)(B) (insolvency exclusion). FDCPA: 15 U.S.C. §1692g (debt validation).
Statute of limitations for written contract debt (Sallie Mae private student loans) by state: Texas 4 years under Tex. Civ. Prac. & Rem. Code §16.004(a)(3); New York 3 years under CPLR §214(2) per Consumer Credit Fairness Act (CCFA) effective April 7, 2022; Pennsylvania 4 years under 42 Pa.C.S. §5525; Ohio 6 years under Ohio R.C. §2305.06 (reduced 2021); Illinois 10 years under 735 ILCS 5/13-206; Georgia 6 years under O.C.G.A. §9-3-24; California 4 years under CCP §337; Florida 5 years under Fla. Stat. §95.11(2)(b); Delaware 3 years under 10 Del. C. §8106. Complete state SOL analysis should be verified against current statutes for each specific borrower situation.
Sallie Mae student loan relief strategy requires case-by-case analysis coordinating loan characteristics, Sallie Mae or current holder identification, chain of assignment history, borrower jurisdiction, defensive framework opportunities, and specific circumstances. This article provides general framework information; specific Sallie Mae Loan Modification Program applications, cosigner release strategies, settlement negotiations with Sallie Mae Bank or successor holders, bankruptcy filings under Homaidan precedent, chain of assignment challenges (particularly NCSLT-related), and coordinated multi-path approaches must be evaluated for each borrower’s individual situation by counsel or consulting resources familiar with the complete sallie mae student loan relief framework. Last reviewed: September 2026.