

Informational content only. Not legal, tax, or financial advice. Private Student Relief is a consulting organization, not a law firm. Debt validation services are executed by an attorney-backed partner provider. Personal/private student loan forgiveness options depend on loan characteristics, lender terms, borrower circumstances, and jurisdiction. Last reviewed: October 2026.
Written by Henry Silva
Private Student Loan Debt Specialist · 10+ years experience explaining and delivering personal student loan forgiveness: settlement negotiation with major private lenders (Sallie Mae Bank NYSE:SLM, Navient/Earnest Operations LLC, Discover/Firstmark Services, SoFi Bank NA, Citizens Bank NA, Ascent), bankruptcy discharge under 11 U.S.C. §523(a)(8) with Homaidan v. Sallie Mae Second Circuit precedent, statute of limitations analysis across all 50 states, chain of assignment challenges under Article III standing (Lujan/Spokeo/TransUnion), and coordinated multi-path personal loan forgiveness strategy specifically for personal student loan debt. Last reviewed: October 2026.
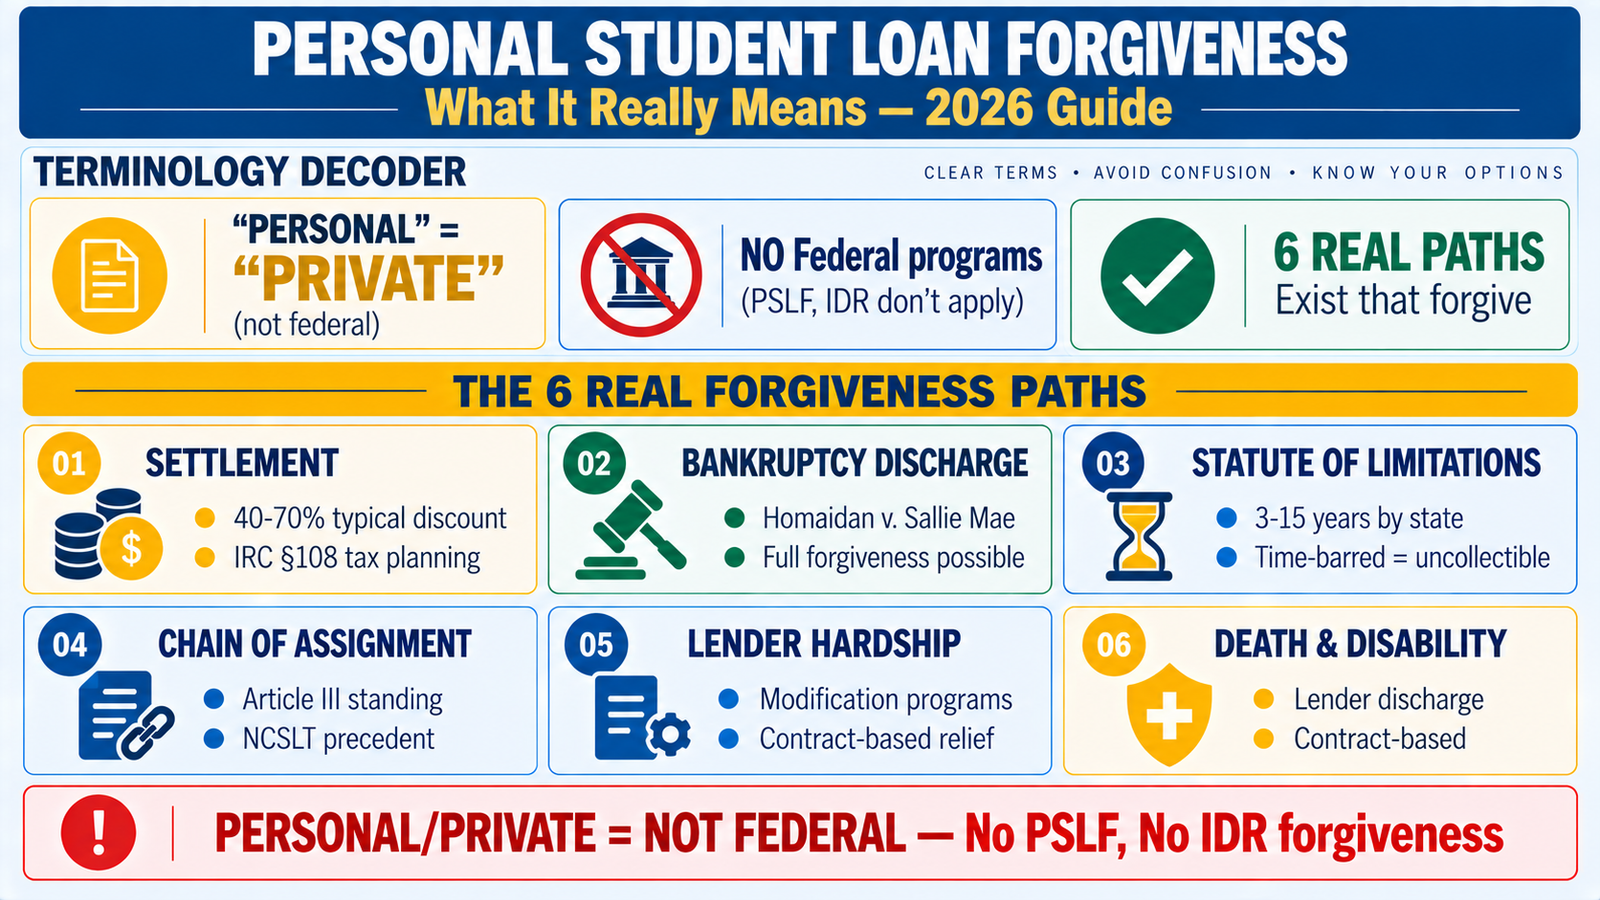
If you’ve been searching personal student loan forgiveness, you’ve probably noticed something confusing: the term means different things to different people. Some use “personal student loan forgiveness” to mean forgiveness of private student loans (as opposed to federal loans); others use “personal loan forgiveness” to describe general unsecured personal loan forgiveness that happens to involve student debt; and many borrowers mix the terms with “student forgiveness” interchangeably. This guide clarifies what personal student loan forgiveness really means in 2026, how it differs from federal forgiveness, and the 6 real legal paths that produce actual forgiveness outcomes: settlement, bankruptcy discharge under 11 U.S.C. §523(a)(8), statute of limitations expiration, chain of assignment defense, lender hardship programs, and death/disability discharge. Federal forgiveness programs (PSLF, IDR forgiveness) do NOT apply to personal/private student loans — but the 6 paths in this guide do.
Quick Answer
Personal student loan forgiveness is a commonly-used term that typically refers to forgiveness of private student loans (loans from private lenders like Sallie Mae, Navient/Earnest, Discover/Firstmark, SoFi, Citizens, Ascent) rather than federal loans. The term is used interchangeably with “private student loan forgiveness” and overlaps with “personal loan forgiveness” when applied to student debt. Federal forgiveness programs (PSLF, IDR forgiveness, Teacher Loan Forgiveness) apply ONLY to federal loans — not to personal/private student loans. Real personal student loan forgiveness works through 6 legal mechanisms: (1) settlement — negotiating with the current holder to pay reduced lump sum, forgiving the balance above payment; (2) bankruptcy discharge under 11 U.S.C. §523(a)(8) with Homaidan v. Sallie Mae Second Circuit precedent (992 F.3d 100, 2d Cir. 2021) making non-qualified loans dischargeable without undue hardship; (3) statute of limitations expiration under state SOL (3-15 years by state); (4) chain of assignment defense on Article III standing grounds; (5) lender hardship programs reducing payment burden; (6) death and disability discharge from most private lenders. The right path depends on loan status, holder, borrower circumstances, and defensive framework opportunities.
Read the complete framework below.
In this complete personal student loan forgiveness guide:
What “personal student loan forgiveness” really means
Terminology clarification and the critical federal vs private distinction
Path 1: Settlement — personal loan forgiveness through negotiation
How settlement forgives portion above payment, realistic outcomes
Path 2: Bankruptcy discharge — complete personal student loan forgiveness
Homaidan precedent, non-qualified loans, Brunner for qualified loans
Path 3: Statute of limitations — time-based student forgiveness
State SOL analysis, revival concerns, defensive application
Path 4: Chain of assignment — standing-based forgiveness
Article III challenges, NCSLT precedent, debt buyer chain defects
Path 5: Lender hardship programs
Sallie Mae, Citizens, SoFi, Earnest, Ascent, Firstmark specifics
Path 6: Death and disability discharge
Lender contract terms and estate planning considerations
What “personal student loan forgiveness” really means
The term personal student loan forgiveness is used in several related but distinct ways. Understanding what people actually mean when they use this term is essential before exploring real forgiveness options. Three common usages predominate: (1) forgiveness of private student loans (as opposed to federal); (2) general personal loan forgiveness applied to loans used for education expenses; (3) individual forgiveness scenarios where the term is used synonymously with any form of debt forgiveness that benefits the borrower personally.
Usage 1: Private student loans (“personal” = “private”)
Most commonly, personal student loan forgiveness refers to forgiveness of PRIVATE student loans — loans from private lenders like Sallie Mae Bank, Navient/Earnest Operations LLC, Discover/Firstmark Services, SoFi Bank NA, Citizens Bank NA, Ascent Student Loans, Wells Fargo (historical), and others. In this usage, “personal” is used as a contrast to “federal” — meaning loans from private sources rather than federal government programs. This is the usage this guide primarily addresses, because it covers the largest category of borrower searches and the most consequential forgiveness decisions.
Usage 2: Personal loans used for education
Some borrowers use personal loan forgiveness to refer specifically to general personal loans (unsecured consumer loans not designated as student loans) that were used to pay for education-related expenses. These loans are typically not subject to §523(a)(8) bankruptcy restrictions (which apply only to “educational loans”) and are dischargeable in bankruptcy without any undue hardship showing. Settlement of these loans follows standard consumer debt settlement principles. If your “student loan” is actually a general personal loan from a bank or online lender (not a specifically designated student loan product), the forgiveness analysis is different and often more favorable than for traditional private student loans.
Usage 3: “Student forgiveness” general term
Some borrowers simply use “student forgiveness” or “personal student loan forgiveness” as general terms for any form of student debt relief — including modifications, settlements, discharges, or other forms of debt reduction. In this usage, the term is a catch-all for any favorable outcome that reduces or eliminates student debt. The specific legal mechanism varies case-by-case.
The critical federal vs private distinction
Regardless of which usage you intended when searching personal student loan forgiveness, one fact is critical: federal forgiveness programs (PSLF, IDR forgiveness, Teacher Loan Forgiveness) apply ONLY to federal loans issued or guaranteed by the U.S. Department of Education. These programs do NOT apply to private loans (from Sallie Mae, SoFi, etc.) or to general personal loans even when used for education. If your loans are private or personal (not federal), the paths in this guide — not federal forgiveness programs — are what actually produce forgiveness outcomes.
Identifying what you actually have
Before pursuing forgiveness, confirm what type of loan you actually have: (1) check studentaid.gov NSLDS — federal loans appear here; private/personal loans do NOT; (2) check credit reports from Experian, Equifax, TransUnion for current furnisher identification; (3) contact each lender directly to confirm loan type (federal, private student loan, or general personal loan); (4) review original promissory notes for loan designation; (5) if “student loan” is actually a general personal loan from a bank, this affects the forgiveness analysis significantly. This identification determines which forgiveness paths apply.
Path 1: Settlement — personal loan forgiveness through negotiation
Settlement is often the most accessible personal loan forgiveness path for borrowers with delinquent or charged-off private/personal student loans. Rather than paying the full balance, the borrower negotiates with the current holder to pay a reduced lump sum in full satisfaction. Settlement produces immediate elimination of the debt above the settlement amount.
How settlement produces personal student loan forgiveness
In settlement, the borrower and current holder agree that payment of a specific reduced amount satisfies the entire debt. The difference between balance and settlement payment is forgiven and reported on Form 1099-C to the IRS (with potential IRC §108 exclusions). Settlement is documented in a written agreement specifying: exact settlement amount; full satisfaction release language; tradeline update instructions to Experian, Equifax, TransUnion; cosigner release for cosigned loans. Once payment is made and release executed, the debt above settlement is legally eliminated. This qualifies as real personal student loan forgiveness for the forgiven portion.
Realistic settlement outcomes
Settlement outcomes vary by loan status and lender: Current/early delinquent (0-90 days) — lenders typically prefer hardship modification over settlement; 90-180 days delinquent — settlement becomes possible as charge-off approaches; Charged-off accounts (180+ days) — often 40-60% discount from balance when approached with proper leverage; Debt-buyer accounts — sometimes 30-50% of balance given lower acquisition cost; NCSLT-held debt — additional discount when chain of assignment weaknesses documented. Approaching settlement from defensive leverage position (chain of assignment, SOL status, bankruptcy alternative) produces materially better outcomes.
Lump sum funding considerations
Settlement typically requires lump sum payment. Common funding sources: personal savings; family financial assistance with documentation; sale of non-essential assets; 401(k) loan (with careful analysis of repayment obligation); tax refund proceeds; small business loan or line of credit if applicable; coordinated timing with seasonal income patterns. Payment plans over 3-6 months can sometimes be negotiated when full lump sum unavailable.
IRC §108 tax planning for settlement forgiveness
The forgiven portion of settlement is reported on Form 1099-C and generally taxable. IRC §108 exclusions provide tax relief: Insolvency exclusion (IRC §108(a)(1)(B)) excludes cancelled debt to extent borrower was insolvent (liabilities exceeded assets) immediately before cancellation; many borrowers qualify; Bankruptcy exclusion (IRC §108(a)(1)(A)) excludes debt cancelled in Chapter 7/13 bankruptcy entirely. CPA analysis before finalizing settlement can eliminate or significantly reduce tax liability on personal student loan forgiveness amounts.
Path 2: Bankruptcy discharge — complete personal student loan forgiveness
Bankruptcy discharge is the most powerful mechanism for personal student loan forgiveness — it can eliminate the entire debt through court order. The prevailing myth that “student loans can never be discharged” is outdated, particularly for private/personal student loans following key Circuit Court precedents. Understanding when and how bankruptcy discharge produces complete forgiveness is essential.
The §523(a)(8) framework
11 U.S.C. §523(a)(8) makes certain educational loans non-dischargeable unless “undue hardship” is shown. Categories: §523(a)(8)(A)(i) — loans made, insured, or guaranteed by governmental unit (federal loans); §523(a)(8)(A)(ii) — “obligation to repay funds received as educational benefit, scholarship, or stipend”; §523(a)(8)(B) — “qualified education loan” as defined in IRC §221(d)(1). Private loans NOT falling into any category are dischargeable WITHOUT undue hardship showing. General personal loans used for education are typically NOT educational loans under §523(a)(8) at all — fully dischargeable without any special analysis.
The Homaidan Second Circuit precedent
Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) established that “educational benefit” under §523(a)(8)(A)(ii) is narrow. The Second Circuit held that Sallie Mae’s direct-to-consumer loans (made directly to students without school certification of cost of attendance) do NOT qualify as “educational benefit” and are therefore dischargeable WITHOUT undue hardship showing. Similar precedents in Fifth Circuit (Crocker v. Navient 941 F.3d 206, 5th Cir. 2019) and Tenth Circuit (McDaniel v. Navient 973 F.3d 1083, 10th Cir. 2020). This precedent is critical to personal student loan forgiveness for private loan borrowers.
Which personal/private loans discharge under Homaidan
Private loans potentially dischargeable without undue hardship: (1) direct-to-consumer loans without school certification of cost of attendance; (2) loans exceeding “cost of attendance” limit for enrollment period; (3) loans for non-title IV eligible programs (vocational, bar prep, non-degree); (4) loans to students not enrolled at least half-time; (5) loans failing other IRC §221(d)(1) requirements. Many Sallie Mae, Navient/Earnest, and other private loans meet these criteria.
Qualified loans and Brunner test
Private loans qualifying under §523(a)(8) require undue hardship showing. Most circuits apply Brunner test from Brunner v. New York State Higher Education Services Corp. 831 F.2d 395 (2d Cir. 1987): (1) debtor cannot maintain minimal standard of living while repaying; (2) additional circumstances indicate this will persist for significant portion of repayment period; (3) debtor has made good faith efforts to repay. Recent case law (In re Rosenberg 594 B.R. 22, Bankr. S.D.N.Y. 2020) and DOJ guidance (November 2022) have moderated application.
General personal loans — easier bankruptcy discharge
If your “student loan” is actually a general personal loan (unsecured consumer loan from a bank or online lender, not a specifically designated student loan), the bankruptcy analysis is substantially easier. General personal loans are typically fully dischargeable in Chapter 7 bankruptcy without any §523(a)(8) analysis — they are standard unsecured debt subject only to normal bankruptcy discharge rules. This provides a clearer and faster path to personal loan forgiveness through bankruptcy for borrowers whose “student loan” is actually a general personal loan.
Chapter 7 vs Chapter 13 selection
Chapter 7 provides discharge of qualifying debts in 3-4 months. Chapter 13 involves 3-5 year payment plan with discharge under 11 U.S.C. §1328 at completion. Chapter selection depends on: means test qualification (Chapter 7 requires income below state median or successful means test under 11 U.S.C. §707(b)(2)); asset preservation needs; whether payment plan restructuring benefits overall situation. Bankruptcy counsel familiar with §523(a)(8) adversary proceeding practice is essential for private student loans.
Path 3: Statute of limitations — time-based student forgiveness
Statute of limitations expiration creates time-based student forgiveness for older personal/private student loan debt. When state SOL expires, the current holder loses the legal ability to file a lawsuit to collect the debt. While the debt still legally exists, it becomes uncollectible through litigation — effectively producing forgiveness in practical terms.
State SOL periods for personal/private student loan debt
SOL periods for written contract debt (private/personal student loans) by common borrower states: Texas 4 years under Tex. Civ. Prac. & Rem. Code §16.004(a)(3); New York 3 years under CPLR §214(2) per Consumer Credit Fairness Act (CCFA) effective April 7, 2022; Pennsylvania 4 years under 42 Pa.C.S. §5525; Ohio 6 years under Ohio R.C. §2305.06 (reduced 2021); Illinois 10 years under 735 ILCS 5/13-206; Georgia 6 years under O.C.G.A. §9-3-24; California 4 years under CCP §337; Florida 5 years under Fla. Stat. §95.11(2)(b); Delaware 3 years under 10 Del. C. §8106. Accrual typically date of first default or last payment depending on state.
Revival concerns for older debt
Borrowers with older personal/private student loan debt must carefully avoid actions that could restart the SOL clock: making any payment on the debt (even small “goodwill” payments) may restart SOL; written acknowledgment of the debt (hardship applications, settlement offers, promise to pay) may create restart; new agreement resets timing. Collectors sometimes solicit small payments or written communications specifically to revive time-barred debt. Consulting counsel before communicating with creditors on old debt prevents inadvertent revival.
Defensive application when SOL expires
When SOL has expired: (1) debt legally exists but cannot be enforced through litigation; (2) collection calls and letters can be disputed under FDCPA 15 U.S.C. §1692g if third-party collector involved; (3) if lawsuit is filed on time-barred debt, motion to dismiss based on SOL expiration typically succeeds and may support FDCPA counterclaim; (4) credit reporting continues under 7-year FCRA reporting period regardless of SOL; (5) settlement of time-barred debt should proceed carefully to avoid revival. SOL expiration provides effective personal student loan forgiveness by making the debt uncollectible.
Path 4: Chain of assignment defense — standing-based forgiveness
Chain of assignment defense produces one of the most powerful forms of personal loan forgiveness — case dismissal on standing grounds that effectively eliminates the debt when the current plaintiff cannot demonstrate right to enforce. Under Article III of the U.S. Constitution, plaintiffs must have standing to bring a lawsuit.
Article III standing framework
Article III standing requires: (1) concrete and particularized injury; (2) causally connected to defendant’s conduct; (3) redressable by court decision. Established in Lujan v. Defenders of Wildlife 504 U.S. 555 (1992), refined in Spokeo, Inc. v. Robins 578 U.S. 330 (2016), and further developed in TransUnion LLC v. Ramirez 594 U.S. 413 (2021). For a plaintiff to sue on private student loan debt, they must establish complete chain of ownership from original lender to themselves. Standing is jurisdictional and can be raised at any stage, including post-judgment through motion to vacate under FRCP 60(b)(4).
NCSLT-specific application
National Collegiate Student Loan Trusts (NCSLT) hold substantial portfolios of pre-2014 Sallie Mae-originated loans, now potentially subject of enforcement by NCSLT. Third Circuit’s March 19, 2024 decision established “covered persons” analysis under the Consumer Financial Protection Act; SCOTUS cert denial in December 2024 left Third Circuit precedent in place; various stipulated resolutions through 2026. Borrowers with personal/private student loan debt held by NCSLT have documented pathways to complete debt elimination through motion to dismiss on standing grounds.
Debt buyer chain defects
Private student loan debt sold to third-party debt buyers after charge-off often has documentation gaps between original lender ownership and current debt buyer’s asserted ownership. Common defects: missing intermediate assignment documentation; assignments executed without adequate documentation of specific debts in bulk sales; blank endorsements without allonge chain; discrepancies between servicing records and asserted debt buyer ownership. These defects support standing challenges that can achieve case dismissal and effective student forgiveness.
Post-judgment vacation
Because standing is jurisdictional, chain of assignment challenges are preserved even after judgment has been entered. Motion to vacate under FRCP 60(b)(4) (void judgment) can be filed at any time if the underlying judgment was entered without proper plaintiff standing. Particularly relevant for older default judgments where the borrower did not appear at the time — the standing challenge remains available years or decades later.
Related resources — complete personal/private forgiveness ecosystem
The 7-path master framework covering all private student loans — same framework applied to personal student loan forgiveness.
Debt Forgiveness for Private Student Loans: What Works 2026
6-mechanism framework for real debt forgiveness including tax planning under IRC §108.
How to Get Rid of Private Student Loans 2026
5-path framework for getting rid of private student loans with decision framework by loan status.
Path 5: Lender hardship programs
Major private student loan lenders offer contract-based hardship programs that provide meaningful relief. While not “forgiveness” in the strictest sense, these programs can reduce overall debt cost, prevent charge-off, and support longer-term personal student loan forgiveness strategy. Understanding lender-specific programs is essential.
Sallie Mae programs
Sallie Mae Bank (NYSE:SLM) offers Loan Modification Program with reduced interest rate (often 4-6%) and reduced payments; Rate Reduction Program for shorter-term relief; Interest-Only Payment Program for 3-12 months; Hardship Forbearance up to 12 months cumulative. Cosigner release after 12 consecutive on-time principal-and-interest payments plus creditworthiness. Death discharge on all Sallie Mae loans; cosigner discharge on borrower death for 2015-and-later loans. Total and Permanent Disability discharge available.
Citizens Bank programs
Citizens Bank NA (NYSE:CFG) offers hardship forbearance and modified payment plans through Loan Servicing Center. Citizens Education Refinance Loan program for refinance. Cosigner release after 36 consecutive on-time principal-and-interest payments plus criteria. Death discharge available.
SoFi programs
SoFi Bank NA (NMLS #696891) offers Unemployment Protection Program providing up to 3 months of paused payments for qualifying job loss, plus short-term Discretionary Forbearance for other hardship. Important: SoFi does NOT offer cosigner release — cosigner status permanent absent full refinance without cosigner. Death discharge available.
Earnest programs
Earnest Operations LLC (Navient subsidiary since 2017) offers skip-a-payment feature (one skipped payment per 12-month period) and hardship forbearance. More accommodating of alternative income sources including gig work and self-employment. Cosigner release available after qualifying period. Death discharge available.
Ascent programs
Ascent Student Loans offers up to 24 months cumulative hardship forbearance plus specific programs for job loss or medical hardship. Cosigner release after 24 or 36 consecutive on-time payments. Ascent college loans originated June 5, 2023 or later have contractual §523(a)(8) discharge waiver. Death and disability discharge available.
Discover / Firstmark Services programs
Firstmark Services (Nelnet NYSE:NNI subsidiary) services former Discover student loans following July 2024 Carlyle+KKR sale of Discover’s student loan portfolio. Firstmark offers hardship deferment and modified payment programs continuing the Discover framework. Cosigner release policies continue through Firstmark. Death discharge available.
Path 6: Death and disability discharge
Death and disability discharge are contract-based mechanisms for personal student loan forgiveness offered by most major private/personal lenders. These programs operate through the loan’s own terms rather than statutory forgiveness, discharging the debt entirely on qualifying death or permanent disability.
Federal loan discharge for comparison
For comparison, federal loans have statutory discharge on death under 20 U.S.C. §1087 (Direct Loans) and 20 U.S.C. §1087dd (Perkins Loans). Federal Total and Permanent Disability discharge available for qualifying borrowers. These statutory federal protections do NOT apply to personal/private loans — discharge depends entirely on each specific lender’s contract terms.
Private lender death discharge policies
Death discharge policies vary by lender: Sallie Mae — discharges borrower’s balance on death; cosigner discharge on death for 2015-and-later loans. Discover / Firstmark — discharges on borrower death. SoFi — discharges on borrower death. Earnest — discharges on borrower death. Citizens Bank — discharges on borrower death. Ascent — discharges on borrower death. Specific terms should be verified against current lender documentation. Estate administrators should promptly notify each lender with proper documentation to activate discharge processing.
Private lender disability discharge policies
Disability discharge is less consistently offered than death discharge. Sallie Mae — Total and Permanent Disability discharge for qualifying borrowers. Ascent — disability discharge available. Other lenders have varying policies verified case-by-case. Documentation typically requires physician certification of permanent disability meeting lender-specific criteria.
Estate and family planning
Death and disability discharge policies affect family financial planning: (1) lenders offering death discharge protect family assets; (2) cosigner exposure may continue after borrower death for older cosigned loans; (3) life insurance coordination provides protection regardless of discharge policy; (4) coordinated estate planning addresses considerations comprehensively.
Choosing your personal student loan forgiveness strategy
Decision framework by loan status
The right personal student loan forgiveness path depends on specific circumstances: Current but struggling — lender hardship programs (Path 5), potential refinance, cosigner release if eligible; Recently delinquent — hardship forbearance to prevent charge-off; Charged-off — settlement negotiation (Path 1) typically most cost-effective, chain of assignment analysis (Path 4) if NCSLT/debt buyer, SOL analysis (Path 3); Lawsuit filed — motion to dismiss on standing or SOL grounds, settlement from defensive position, bankruptcy analysis (Path 2); Judgment entered — motion to vacate on standing grounds preserved under FRCP 60(b)(4); Long-standing debt near SOL — careful SOL analysis, avoid revival; Serious financial distress — bankruptcy analysis including Homaidan §523(a)(8) framework; Death or permanent disability — lender-specific discharge application (Path 6).
Combining multiple paths
Effective personal loan forgiveness outcomes often combine multiple paths: chain of assignment analysis creating settlement leverage; SOL analysis creating urgency; bankruptcy analysis under Homaidan as credible alternative; hardship program buying time; cosigner release combined with refinance. Coordinated multi-path strategy typically produces better outcomes than any single path alone.
Working with professional resources
Given the complexity of the 6 paths and their interactions, working with professional resources typically produces better outcomes than DIY approaches. Options: bankruptcy counsel familiar with Homaidan §523(a)(8) analysis; state-licensed attorneys for chain of assignment challenges; consulting firms familiar with complete defensive framework; CPAs for IRC §108 tax analysis. Private Student Relief’s attorney-backed partner provider network coordinates these resources for comprehensive private student relief analysis.
Common personal student loan forgiveness myths
Myth 1
“Personal student loan forgiveness means federal loan forgiveness”
Reality: Personal student loan forgiveness typically refers to forgiveness of PRIVATE student loans (from private lenders like Sallie Mae, SoFi, etc.), not federal loans. Federal forgiveness programs (PSLF, IDR forgiveness) apply ONLY to federal loans. If your loans are private/personal (not federal), federal forgiveness programs do not apply — you need the 6 paths in this guide. The confusion between “personal” (as in private, non-federal) and “federal” causes significant borrower frustration when they discover their loans don’t qualify for federal programs.
Myth 2
“Personal loan forgiveness doesn’t exist — only federal loans get forgiven”
Reality: Personal loan forgiveness absolutely exists through the 6 mechanisms in this guide. Settlement produces real forgiveness of the balance above the settlement payment. Bankruptcy discharge under §523(a)(8) with Homaidan precedent produces complete forgiveness for qualifying loans. SOL expiration makes debt uncollectible. Chain of assignment challenges can dismiss cases entirely. Lender hardship programs modify debt terms. Death/disability discharge forgives debt completely for qualifying situations. The absence of federal forgiveness programs does NOT mean the absence of any forgiveness — just different mechanisms.
Myth 3
“If my ‘student loan’ is actually a personal loan, I’m stuck with it forever”
Reality: General personal loans (unsecured consumer loans from banks or online lenders, not specifically designated as student loans) are typically EASIER to discharge in bankruptcy than true student loans. Because general personal loans are not “educational loans” under §523(a)(8), they are fully dischargeable in Chapter 7 bankruptcy without any undue hardship showing or special analysis — they are standard unsecured debt. If your “student loan” is actually a general personal loan, your personal loan forgiveness options through bankruptcy are substantially better than for true student loans.
Myth 4
“Student forgiveness programs will eventually include private loans”
Reality: There are no credible proposals to extend federal forgiveness programs (PSLF, IDR forgiveness) to private student loans. The legal framework for federal forgiveness is specifically tied to federal loan statutes. Expanding federal forgiveness to private loans would require federal purchase or payment to private lenders, which has no legislative support. Borrowers waiting for federal student forgiveness to be extended to private loans are waiting for something that is unlikely to happen. The real forgiveness paths — the 6 in this guide — are available now and work through existing legal frameworks.
Frequently asked questions
1. What is personal student loan forgiveness?
Personal student loan forgiveness typically refers to forgiveness of PRIVATE student loans (loans from private lenders like Sallie Mae Bank, Navient/Earnest Operations LLC, Discover/Firstmark Services, SoFi Bank NA, Citizens Bank NA, Ascent, and others) as opposed to federal loans. In this usage, “personal” means “not federal” — private sources rather than federal government programs. Real personal student loan forgiveness works through 6 legal mechanisms: settlement, bankruptcy discharge under §523(a)(8) with Homaidan precedent, statute of limitations expiration, chain of assignment defense on Article III standing grounds, lender hardship programs, and death/disability discharge. Federal forgiveness programs (PSLF, IDR forgiveness) do NOT apply.
2. Can personal loans be forgiven?
Yes, personal loan forgiveness is achievable through several mechanisms depending on loan type. For general personal loans (unsecured consumer loans from banks or online lenders): fully dischargeable in Chapter 7 bankruptcy; settlement typically achieves 30-60% discount; statute of limitations expiration makes debt uncollectible; chain of assignment challenges for debt-buyer-held loans. For private student loans specifically (loans designated as student loans): the 6-path framework in this guide applies, with the §523(a)(8) analysis adding complexity but still producing real forgiveness outcomes through Homaidan precedent and other mechanisms.
3. What’s the difference between personal and private student loan forgiveness?
The terms personal student loan forgiveness and private student loan forgiveness are used interchangeably in most contexts — both refer to forgiveness of student loans from private lenders rather than federal programs. “Personal” in this context is a colloquial synonym for “private” (not federal). The legal framework and forgiveness mechanisms are identical: the same 6 paths in this guide apply whether you call it personal student loan forgiveness or private student loan forgiveness. The distinction matters only when the term “personal loan” refers to a general personal loan (not a specifically designated student loan), in which case bankruptcy discharge is easier.
4. Is there any student forgiveness for private loans?
Yes, real student forgiveness for private loans works through 6 mechanisms (federal programs like PSLF/IDR do NOT apply to private loans): (1) settlement negotiation producing partial forgiveness of balance above settlement payment; (2) bankruptcy discharge under §523(a)(8) with Homaidan Second Circuit precedent for non-qualified loans (dischargeable without undue hardship) and Brunner test for qualified loans; (3) statute of limitations expiration making debt uncollectible; (4) chain of assignment defense on Article III standing grounds for case dismissal; (5) lender hardship programs modifying debt terms; (6) death and disability discharge from most private lenders. Which path works depends on specific circumstances.
5. How do I get my personal student loans forgiven?
Steps to get my personal student loans forgiven: (1) confirm loans are private/personal (not federal) via studentaid.gov NSLDS check; (2) identify current holder and servicer for each loan; (3) evaluate loan status (current, delinquent, charged-off, in litigation); (4) analyze which of the 6 paths apply — settlement for delinquent/charged-off, bankruptcy under Homaidan for qualifying loans, SOL for old debt, chain of assignment for NCSLT/debt buyer debt, hardship programs for current difficulty, discharge for death/disability; (5) work with attorney or specialist to develop coordinated strategy; (6) execute the plan through appropriate legal or negotiation processes. Professional guidance produces materially better outcomes.
6. Does personal loan forgiveness exist as a government program?
No, there is NO government program that forgives private/personal student loans or general personal loans. Federal forgiveness programs (PSLF, IDR forgiveness, Teacher Loan Forgiveness) apply ONLY to federal loans. Any company claiming “government-approved” personal loan forgiveness is misrepresenting the law. Real personal loan forgiveness works through the private legal mechanisms in this guide — negotiated settlement, bankruptcy discharge, statute of limitations, chain of assignment defense, lender programs. Be alert to scam operators exploiting confusion about federal versus private loan forgiveness.
7. How long does personal student loan forgiveness take?
Timelines vary by mechanism: settlement typically 2-6 months from initial negotiation to completion; bankruptcy Chapter 7 typically 3-4 months from filing to discharge (plus 60-90 days for §523(a)(8) adversary proceeding if needed); Chapter 13 typically 3-5 years to plan completion; chain of assignment challenges typically 6-18 months for motion practice; statute of limitations timing depends on state law (3-15 years); lender program applications typically 30-90 days. Realistic expectations are essential — unlike the 20-25 year federal IDR forgiveness timeline, private/personal student loan forgiveness through these mechanisms can produce results much faster.
Need Personal Student Loan Forgiveness?
Free specialist review of all 6 paths for your personal loan situation.
Settlement negotiation analysis, bankruptcy discharge evaluation under §523(a)(8) with Homaidan precedent, statute of limitations analysis by state, chain of assignment defensive framework for NCSLT-held debt, lender hardship program qualification, and coordinated approach across all six paths to personal student loan forgiveness. Free eligibility review with attorney-backed partner provider — no upfront fees.
Get a free eligibility review →
5-minute review · No obligation · Zero upfront fees · Since 2015 · 48 states served
About the author
Henry Silva — Private Student Loan Debt Specialist
10+ years experience delivering real personal student loan forgiveness outcomes: settlement negotiation with major private lenders (Sallie Mae Bank NYSE:SLM, Navient/Earnest Operations LLC, Discover/Firstmark Services after July 2024 Carlyle+KKR sale, SoFi Bank NA NMLS #696891, Citizens Bank NA NYSE:CFG, Ascent Student Loans), bankruptcy discharge analysis under 11 U.S.C. §523(a)(8) with Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) precedent, Crocker v. Navient 941 F.3d 206 (5th Cir. 2019), McDaniel v. Navient 973 F.3d 1083 (10th Cir. 2020), Brunner v. New York State Higher Education Services Corp. 831 F.2d 395 (2d Cir. 1987) framework for qualified loans, In re Rosenberg 594 B.R. 22 (Bankr. S.D.N.Y. 2020) updated application, statute of limitations analysis across all 50 states, hardship program qualification, cosigner release strategy, chain of assignment challenges under Article III standing doctrine (Lujan/Spokeo/TransUnion), NCSLT Third Circuit precedent application, IRC §108(a)(1)(A) bankruptcy and IRC §108(a)(1)(B) insolvency tax exclusion analysis, and coordinated multi-path strategy for maximum personal loan forgiveness outcomes. Henry works with Private Student Relief’s attorney-backed partner provider network to review individual scenarios across all 6 forgiveness mechanisms.
Legal Disclaimer and Sources
This article is provided for informational purposes only and does not constitute legal, tax, or financial advice. Private Student Relief is a consulting and matching organization operated by Joco (555 Anton Blvd, Suite 368, Costa Mesa, CA 92626) — not a law firm, debt settlement company, debt consolidation company, or loan provider. Debt validation services are performed by an attorney-backed partner provider (Panamerican Consulting LLC, Las Vegas, NV) under independent business credentials. Ratings, BBB accreditation, and AADR membership referenced on the PSR website belong to the partner provider. Personal/private student loan forgiveness pathway availability depends on loan characteristics, lender terms, borrower circumstances, and jurisdiction. Individual results vary. Since 2015. 48 states served. Not available in South Carolina or Mississippi.
Federal student loan program citations (for comparison, these do NOT apply to personal/private student loans): Higher Education Act (20 U.S.C. §1001 et seq.); Public Service Loan Forgiveness (20 U.S.C. §1087e(m)); Income-Driven Repayment forgiveness (federal loan regulatory framework); Direct Loan death discharge (20 U.S.C. §1087); Perkins Loan death discharge (20 U.S.C. §1087dd). These federal programs apply ONLY to federal loans.
Bankruptcy Code references: 11 U.S.C. §523(a)(8) (student loan discharge exceptions with §523(a)(8)(A)(i) governmental unit, §523(a)(8)(A)(ii) educational benefit, §523(a)(8)(B) qualified education loan categories); 11 U.S.C. §362 (automatic stay); 11 U.S.C. §707(b)(2) (means test); 11 U.S.C. §1328 (Chapter 13 discharge). Key bankruptcy precedent: Homaidan v. Sallie Mae 992 F.3d 100 (2d Cir. 2021) — direct-to-consumer private education loans dischargeable without undue hardship; Brunner v. New York State Higher Education Services Corp. 831 F.2d 395 (2d Cir. 1987) — undue hardship test; Crocker v. Navient Solutions LLC 941 F.3d 206 (5th Cir. 2019); McDaniel v. Navient Solutions LLC 973 F.3d 1083 (10th Cir. 2020); In re Rosenberg 594 B.R. 22 (Bankr. S.D.N.Y. 2020). Article III standing precedent: Lujan v. Defenders of Wildlife 504 U.S. 555 (1992); Spokeo, Inc. v. Robins 578 U.S. 330 (2016); TransUnion LLC v. Ramirez 594 U.S. 413 (2021). Federal Rules of Civil Procedure: FRCP 60(b)(4) (void judgment). Internal Revenue Code: IRC §221(d)(1) (qualified education loan definition); IRC §108(a)(1)(A) (bankruptcy exclusion); IRC §108(a)(1)(B) (insolvency exclusion). FDCPA: 15 U.S.C. §1692g (debt validation).
Statute of limitations for written contract debt (personal/private student loans) by state: Texas 4 years under Tex. Civ. Prac. & Rem. Code §16.004(a)(3); New York 3 years under CPLR §214(2) per Consumer Credit Fairness Act (CCFA) effective April 7, 2022; Pennsylvania 4 years under 42 Pa.C.S. §5525; Ohio 6 years under Ohio R.C. §2305.06 (reduced 2021); Illinois 10 years under 735 ILCS 5/13-206; Georgia 6 years under O.C.G.A. §9-3-24; California 4 years under CCP §337; Florida 5 years under Fla. Stat. §95.11(2)(b); Delaware 3 years under 10 Del. C. §8106. Complete state SOL analysis should be verified against current statutes for each specific borrower situation.
Lender information current as of October 2026 per publicly available documentation: Sallie Mae Bank NYSE:SLM; Navient/Earnest Operations LLC (subsidiary since 2017); Discover student loans acquired by Carlyle Group and KKR July 2024 with servicing transitioned to Firstmark Services (Nelnet NYSE:NNI subsidiary); SoFi Bank NA NMLS #696891 (chartered as national bank 2022); Citizens Bank NA NYSE:CFG; Ascent Student Loans with June 5, 2023 originated loans having contractual §523(a)(8) discharge waiver. Specific lender program details subject to change and should be verified directly with current lender documentation.
Personal student loan forgiveness strategy requires case-by-case analysis coordinating loan characteristics, lender identification, chain of assignment history, borrower jurisdiction, defensive framework opportunities, and specific circumstances. This article provides general framework information; specific settlement negotiations, bankruptcy filings under Homaidan precedent, chain of assignment challenges, hardship program applications, cosigner release strategies, and coordinated multi-path approaches must be evaluated for each borrower’s individual situation by counsel or consulting resources familiar with the complete personal student loan forgiveness framework. Last reviewed: October 2026.